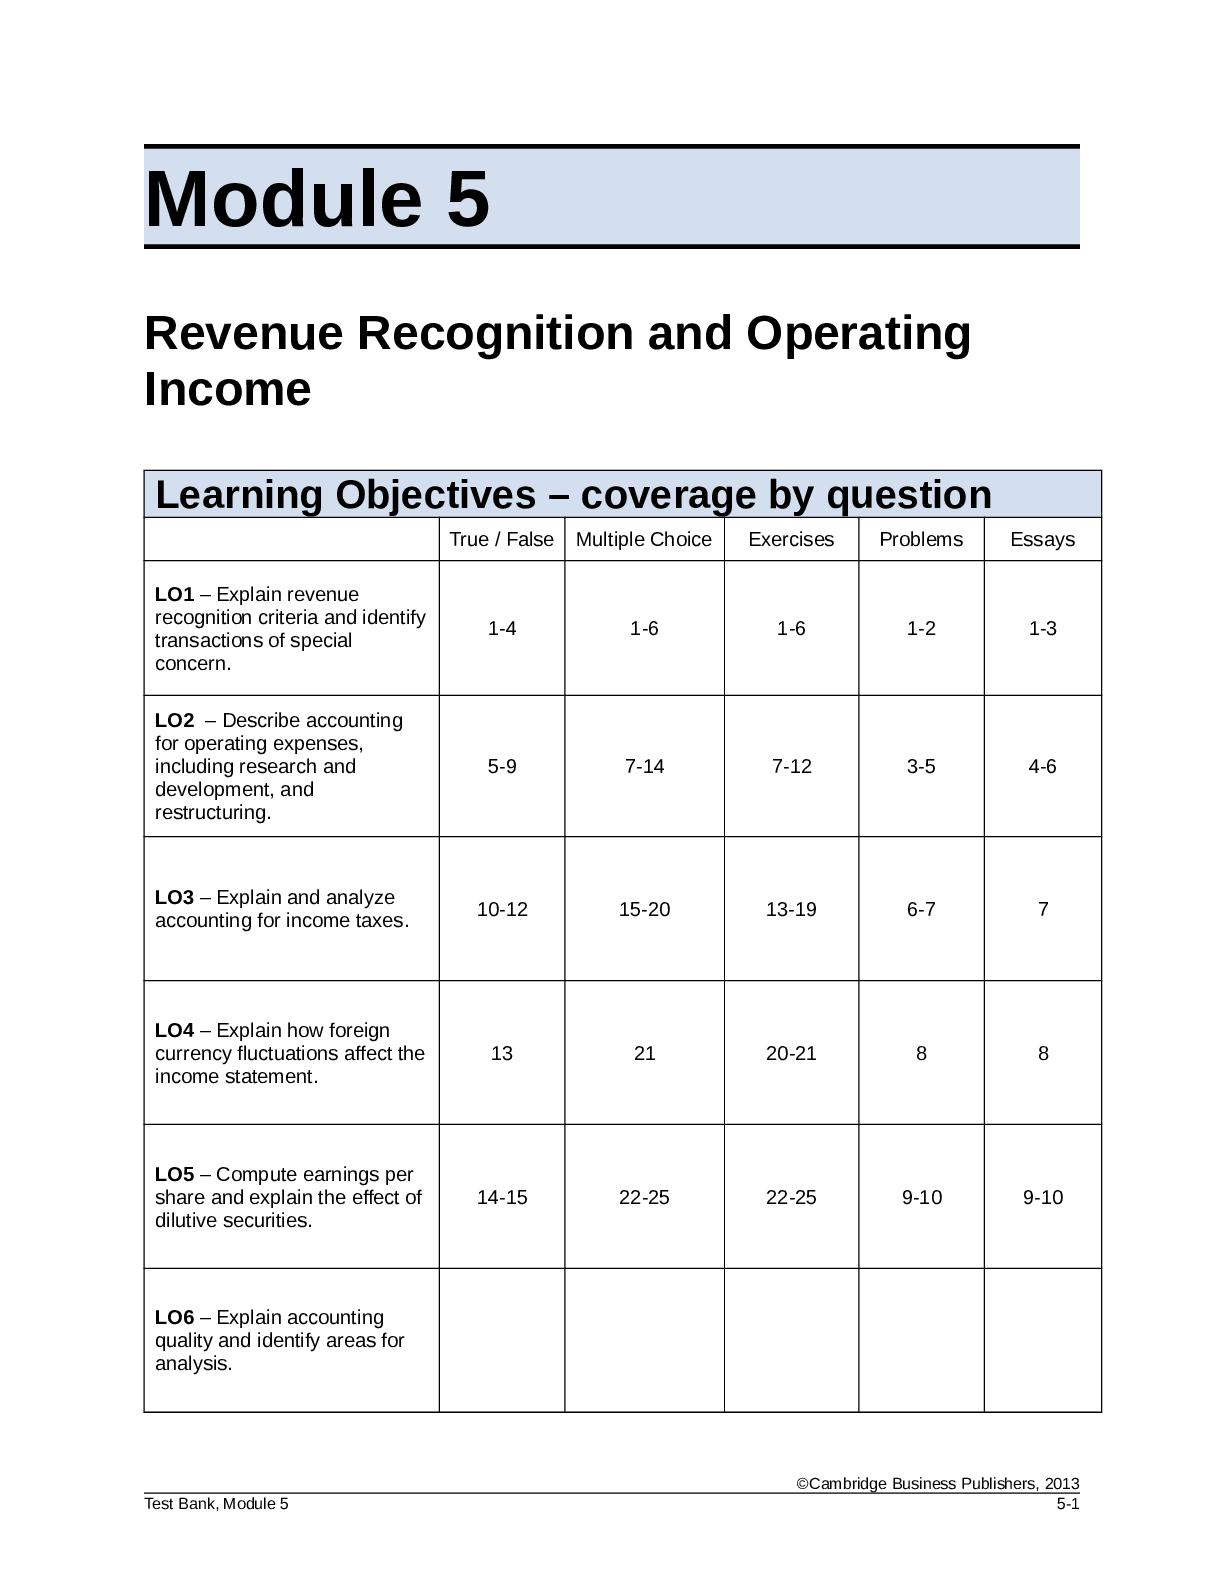
Module 5
Revenue Recognition and Operating
Income
Learning Objectives – coverage by question
True / False Multiple Choice Exercises Problems Essays
LO1 – Explain revenue
recognition criteria and identify
transac
...
Module 5
Revenue Recognition and Operating
Income
Learning Objectives – coverage by question
True / False Multiple Choice Exercises Problems Essays
LO1 – Explain revenue
recognition criteria and identify
transactions of special
concern.
1-4 1-6 1-6 1-2 1-3
LO2 – Describe accounting
for operating expenses,
including research and
development, and
restructuring.
5-9 7-14 7-12 3-5 4-6
LO3 – Explain and analyze
accounting for income taxes. 10-12 15-20 13-19 6-7 7
LO4 – Explain how foreign
currency fluctuations affect the
income statement.
13 21 20-21 8 8
LO5 – Compute earnings per
share and explain the effect of
dilutive securities.
14-15 22-25 22-25 9-10 9-10
LO6 – Explain accounting
quality and identify areas for
analysis.
©Cambridge Business Publishers, 2013
Test Bank, Module 5 5-1Module 5: Revenue Recognition and Operating Income
True/False
Topic: Revenue Recognition
LO: 1
1. According to GAAP revenue recognition criteria, in order for revenue to be recognized on the income
statement, it must be earned and realized (realizable).
Answer: True
Rationale: According to GAAP revenue recognition criteria, revenue must be both realized
(realizable) and earned, to be recognized on the income statement. The issue of when the revenue
is earned is subject to professional judgment.
Topic: Percentage of Completion
LO: 1
2. Companies that engage in long-term sales contracts such as construction projects often use the
percentage of completion method to recognize revenue. This means that revenue is recognized in
proportion to the project’s completion.
Answer: True
Rationale: Percentage of completion method recognizes revenue by determining the costs incurred
under the contract relative to its total expected costs and not evenly over time.
Topic: Sales on Consignment
LO: 1
3. Revenue from a consignment sale is recognized when the item is placed on consignment with the
middleman, if sales are probable, based on past experience.
Answer: False
Rationale: When the item is delivered to the middleman (the consignee) no title has passed therefore
no revenue has been earned. Revenue is only earned when the third party buys the item.
Topic: Revenue Recognition
LO: 1
4. Bed Bath and Beyond has a 60-day return policy. The company can report revenue on the full amount
as soon as the merchandise is sold.
Answer: False
Rationale: Revenue will be recognized as soon as the merchandise is sold but only for the portion
that the company estimates will not be returned within the 60-day return period. The estimated returns
are netted against sales and set up as a liability (reserve).
Topic: R&D Costs
LO: 2
5. R&D expense is treated as an operating expense, not a capital expenditure, unless the R&D assets
acquired have an alternative future use.
Answer: True
Rationale: Although the R&D assets are similar to regular plant assets, under GAAP, R&D costs are
expensed unless the R&D assets have alternative future uses.
©Cambridge Business Publishers, 2013
5-2 Financial Statement Analysis & Valuation, 3rd EditionTopic: R&D Costs
LO: 2
6. Next year, Dow Chemical Corporation plans to build a laboratory dedicated to a special project. The
company will not use the laboratory after the project is finished. Under GAAP, this laboratory should
be expensed.
Answer: True
Rationale: R&D costs must be expensed under GAAP unless they have alternative future uses. If
these assets do, indeed, have alternative future uses, they will be capitalized and depreciated.
Topic: Discontinued Operations
LO: 2
7. Revenues from discontinued operations of a company are reported separately from revenues from
continuing operations in the income statement.
Answer: True
Rationale: Discontinued operations refer to any identifiable business unit that the company intends to
sell. The income (loss) of the discounted operation (net of tax), and the after-tax gain (loss) on sale of
the unit, are reported in a separate section of the income statement below income from continuing
operations.
Topic: Restructuring Costs
LO: 2
8. Employee severance costs, as part of board-approved restructuring plans, are reported in the income
statement even if the actual payment for these costs occurs in subsequent periods.
Answer: True
Rationale: Employee severance costs are reported in the income statement as accrued costs. Total
estimated costs of terminating or relocating a targeted employee group are recorded as an expense
in the period in which these costs are estimated.
Topic: Extraordinary Items
LO: 2
9. For an item to be classified as extraordinary, it needs to be both unusual and infrequent. However,
there is an exception for material items – for one-time items that are extremely large, firms have the
option of classify these items as extraordinary to provide better information to investors.
Answer: False
Rationale: Both of the above conditions need to be fulfilled for an item to be categorized
extraordinary. There is no materiality exception.
Topic: Income Taxes
LO: 3
10. Income tax expense is not recorded at the amount owing to the tax authorities even if this is the most
objectively measured amount.
Answer: True
Rationale: Income tax expense is based on GAAP numbers. The amount paid is based on tax rules.
The difference between the two is recorded as deferred tax expense (benefit).
©Cambridge Business Publishers, 2013
Test Bank, Module 5 5-3Topic: Deferred Taxes
LO: 3
11. When a company reports a deferred tax asset it means that the company will receive a tax benefit in
the future.
Answer: False
Rationale: The deferred tax asset may be recorded if the future benefit is more likely than not. The
company does not have to be absolutely certain only relatively certain that future taxes will be lower
(a benefit).
Topic: Depreciation and Taxes
LO: 3
12. For tax reporting purposes, companies typically transfer more of the asset’s cost from the balance
sheet to the income statement in the earlier years of the asset’s life. This is called accelerated
depreciation and it is a benefit to the company. Thus, companies record deferred tax assets (benefits)
for this accelerated depreciation.
Answer: False
Rationale: Accelerated depreciation reduces taxable income and, consequently, the current tax
liability and, thereby, increases cash flows early in the asset’s life. Over the life of the asset, the
company must make up these taxes, thus accelerated depreciation creates a deferred tax liability and
not an asset.
Topic: Foreign Currency Translation
LO: 4
13. Revenue from a foreign subsidiary will be smaller in U.S. dollars when the dollar strengthens relative
to the foreign currency.
Answer: True
Rationale: Foreign currency is weaker when the dollar strengthens. Thus, revenue in the foreign
currency is worth fewer U.S. dollars.
Topic: Earnings per Share
LO: 5
14. A company with outstanding in-the money employee stock options will report a diluted EPS that is
lower than basic EPS.
Answer: True
Rationale: Diluted EPS will only be lower than basic EPS if the outstanding employee stock options
are dilutive, which means the stock options are at or in the money.
Topic: Diluted EPS
LO: 5
15. Because diluted EPS include dilutive securities such as convertible securities and employee stock
options, it must always be less than or equal to basic EPS.
Answer: True
Rationale: Diluted EPS includes dilutive securities in the denominator of the ratio. Therefore the
diluted EPS ratio must always be less than or equal to basic EPS.
©Cambridge Business Publishers, 2013
5-4 Financial Statement Analysis & Valuation, 3rd EditionMultiple Choice
Topic: Revenue Recognition
LO: 1
1. Which of the following items do not create risk related to revenue recognition?
A) Bonuses tied to sales goals
B) Long-term construction contracts
C) Multiple element sales contracts
D) Consignment goods
E) All of the above
Answer: E
Rationale: Each of these types of revenue or business conditions creates risk associated with
revenue recognition. Each requires good internal controls to prevent and detect inappropriate
revenue recognition, as well as extra management vigilance and auditor care.
Topic: Revenue Recognition at a Service Firm
LO: 1
2. Boston Consulting Group (BCG) is a management consulting, technology services and outsourcing
organization. Which of the following actions should managers take when there is evidence that a
fixed-rate contract is over budget and will generate a loss for the firm?
A) Use the percentage of completion method to recognize the loss over the remaining term of the
engagement.
B) Recognize the loss in the current period rather than over the remaining term of the engagement.
C) Restate the financial statements and recognize the loss in the earliest period of the engagement.
D) Use the percentage of completion method and pro rate the loss over the entire term of the
engagement.
E) None of the above is an appropriate action.
Answer: B
Rationale: When contracts are over-budget, managers should estimate the new, revised, total
engagement cost. If this results in a loss on the engagement, that loss should be recognized
immediately rather than over the remaining term of the engagement.
©Cambridge Business Publishers, 2013
Test Bank, Module 5 5-5Topic: Percentage-of-Completion Method (Numerical calculations required)
LO: 1
3. On December 31, 2012, Tri-State Construction Inc. signs a contract with the state of Texas
Department of Transportation to manufacture a bridge over the Rio Grande. Tri-State anticipates the
construction will take three years. The company’s accountants provide the following contract details
relating to the project:
Contract price $420 million
Estimated construction costs $300 million
Estimated total profit $120 million
During the three-year construction period, Tri-State incurred costs as follows:
2013 $ 30 million
2014 $180 million
2015 $ 90 million
Tri-State uses the percentage of completion method to recognize revenue. Which of the following
represent the revenue recognized in 2013, 2014, and 2015?
A) $140 million, $140 million, $140 million
B) $30 million, $180 million, $90 million
C) $12 million, $72 million, $36 million
D) $42 million, $252 million, $126 million
E) None of the above
Answer: D
Rationale:
($ in millions) Year 1 Year 2 Year 3
Construction costs incurred $30 $180 $90
Percentage to total costs $30 / $300 = 10% $180 / $300 = 60% $90 / $300 = 30%
Revenue recognized 10% × $420 = $42 60% × $420 = $252 30% × $420= $126
Topic: Percentage-of-Completion Method (Numerical calculations required)
LO: 1
4. In spring 2012, Mainline Engineering Company signed an $80 million contract with the city of Duluth,
to construct a new city hall. Mainline expects to construct the building within two years and incur
expenses of $60 million. The city of Duluth paid $20 million when the contract was signed, $40 million
within the next six months, and the final $20 million exactly one year from the signing of the contract.
Mainline incurred $24 million in costs during 2012 and rest in 2013 to complete the contract on time.
Using the percentage-of-completion method how much revenue should Mainline recognize in 2012?
A) $32 million
B) $60 million
C) $20 million
D) $40 million
E) None of the above
Answer: A
Rationale: According to the percentage-of-completion method Mainline Engineering Company should
recognize the revenues as shown in the table below:
Year Total contract Percentage completed Revenue Recognized
2012 $80 million $24 million/$60 million
= 40%
40% × $80 million
= $32 million
©Cambridge Business Publishers, 2013
5-6 Financial Statement Analysis & Valuation, 3rd EditionTopic: Risk Exposures to Revenue Recognition
LO: 1
5. Sam’s Club (part of the WalMart consolidated operations) collects annual non-refundable
membership fees from customers. When should Sam’s Club recognize revenue for these
membership fees?
A) Immediately when cash is received because the fees are nonrefundable
B) Evenly over the membership year
C) Evenly over the current fiscal year
D) At the end of the membership year when Sam’s has discharged its obligation to the customer
E) Pro rata over the customer’s actual purchasing pattern
Answer: B
Rationale: Sam’s should record membership fees evenly over the year even if the fee is
nonrefundable because Sam’s has an obligation to stay open for business for a year to honor the
customer’s membership.
Topic: Revenue Recognition
LO: 1
6. Tickets Now contracts with the producer of Riverdance to sell tickets online. Tickets Now charges
each customer a fee of $4 per ticket and receives $10 per ticket from the producer. Tickets Now does
not take control of the ticket inventory. Average ticket price for the event is $150. How much revenue
should Tickets Now recognize for each Riverdance ticket sold?
A) $4 because the $10 from the producer is similar to a negative cost of goods sold
B) $14 because both the fee from the customer and the producer are earned
C) $150 because the $140 is cost of goods sold paid to the Riverdance producer
D) $186 because the $140 is cost of goods sold paid to the Riverdance producer
E) None of the above
Answer: B
Rationale: Tickets Now should record $14 revenue each time it sells a ticket. Of that $4 will be
received in cash and $10 will be recorded as receivable from the Riverdance producers.
Topic: Research and Development Expenses
LO: 2
7. On its 2011 income statement, Yahoo! reported Product development expense of $1,005,090. Which
of the following statements must be true?
A) Yahoo spent $1,005,090 in cash to develop new products and improve old products.
B) Product development expense reduced Yahoo’s 2011 net income by $1,005,090.
C) Yahoo capitalized at least $1,005,090 of product development costs in 2011.
D) The $1,005,090 included amortized product development costs from prior years that were not
previously expensed, because Yahoo incurs such expenses each year.
E) None of the above
Answer: E
Rationale: Yahoo included in product development expense certain non-cash expenses such as
depreciation on related assets, thus a is not correct. Yahoo recorded deferred tax expense on the
product development expense, thus net income was affected on an after-tax basis and b is therefore
not correct. Under US GAAP, firms may not capitalize R&D costs, thus c is not correct. All R&D
expenses must be included in the income statement in the period, thus d is wrong.
©Cambridge Business Publishers, 2013
Test Bank, Module 5 5-7Topic: Research and Development Expenses
LO: 2
8. Life Technologies Corporation reported research and development expense of $377,924 thousand on
its 2011 income statement. This expense included many types of costs. Which of the following types
of costs would not be included in the $377,924 thousand?
A) Salaries and wages for R&D personnel
B) Supplies and inventory related to R&D activities and new-product sales
C) Depreciation on equipment used in experiments
D) Costs of applying for FDA approval
E) None of the above
Answer: B
Rationale: R&D expenses exclude any costs related to sales.
Topic: Research and Development Expenses (Numerical calculations required)
LO: 2
9. Life Technologies Corporation and Affymetrix Inc. are competitors in the life sciences and clinical
healthcare industry. Following is a table of Total revenue and R&D expenses for both companies.
Life Technologies Corporation Affymetrix Inc
2011 2010 2009 2011 2010 2009
Total revenue $3,775,672 $3,588,094 $3,280,344 $241,273 $277,743 $279,186
R&D expenses $377,924 $375,465 $337,099 $63,591 $67,934 $77,358
Which of the following is true?
A) Life Technologies Corporation is the more R&D intensive company of the two.
B) Life Technologies Corporation has become more R&D intensive over the three years.
C) Affymetrix is more R&D intensive in 2011 than in 2010.
D) Affymetrix is less R&D intensive in 2011 than in 2010.
E) None of the above
Answer: C
Rationale: To make comparisons, we need to common size the R&D expenditures of both firms by
scaling by total revenues.
Life Technologies Corporation Affymetrix Inc
2011 2010 2009 2011 2010 2009
Common sized R&D 10.0% 10.5% 10.3% 26.4% 24.5% 27.7%
Affymetrix spends proportionately more on R&D than Life Technologies, thus a is not true. Life
Technologies has spent less on R&D in 2011 than in 2010 and 2009, thus b is not true. Affymetrix
increased R&D from 24.5% in 2010 to 26.4% in 2011, thus C is true, but not D.
©Cambridge Business Publishers, 2013
5-8 Financial Statement Analysis & Valuation, 3rd EditionTopic: Research and Development Expenses – Building with no Alternate Use
LO: 2
10. Dow Chemical Corporation plans to build a laboratory dedicated to a special project. The company
will not use the laboratory after the project is finished. Under GAAP, this laboratory should be:
A) Capitalized and depreciated.
B) Expensed in the current year.
C) Depreciated and expensed.
D) Capitalized only.
E) None of the above
Answer: B
Rationale: Project-directed or highly-specific research buildings and equipment with no alternate uses
must be expensed as incurred.
Topic: Research and Development Expenses (Numerical calculations required)
LO: 2
11. Yahoo! reported the following in its 2011 financial statements (in thousands):
(in millions)
December 31,
2010
December 31,
2011
Total assets $14,928,104 $14,782,786
Revenues $6,324,651 $4,984,199
Product development expense $1,082,176 $1,005,090
Net income $1,244,628 $1,062,669
What is Yahoo’s common-sized product development expense for 2011?
A) 6.8%
B) 20.2%
C) 94.6%
D) 93.7%
E) None of the above
Answer: B
Rationale: To common-size income statement items, we divide by current period sales. Commonsized product development expense for 2011 is therefore $1,005,090/ $4,984,199 = 20.2%.
Topic: Restructuring Charges (Numerical calculations required)
LO: 2
12. Mariposa Imports recorded a restructuring charge of $10.8 million during fiscal 2012 related entirely to the
closing of its California based operations in San Diego and in Tijuana, Mexico. The company’s financial
statement footnotes indicated that expected employee separation payments amounted to $8.4 million and
that fixed asset write-downs accounted for the remainder. Mariposa had never before incurred
restructuring charges. At the end of the year, the company’s balance sheet included a restructuring
accrual of $1,800,000. The cash flow effect of Mariposa’s restructuring during fiscal 2012 is:
A) $0 (there was no cash flow effect in 2012)
B) $1,800,000
C) $8,400,000
D) $6,600,000
E) $10,800,000
Answer: D
Rationale: The total restructuring charge accrued was $8.4 million because asset write-downs are not
accrued. That is there is no credit to a liability account for write-downs, the assets are credited
(reduced). Thus, the company must have paid $8,400,000 - $1,800,000 = $6,600,000 in cash during
fiscal 2012.
©Cambridge Business Publishers, 2013
Test Bank, Module 5 5-9Topic: Restructuring Charges (Numerical calculations required)
LO: 2
13. Dow Chemical recorded pretax restructuring charges of $689 million in 2009. The charges consisted
of asset write-downs of $454 million, costs associated with exit or disposal activities of $66 million,
and employee severance costs of $169 million. The company paid $72 million cash to settle these
restructuring charges during the year (2009). At year end, the restructuring accrual associated with
these charges was:
A) $689 million
B) $617 million
C) $163 million
D) $ 97 million
E) There is not enough information to determine the amount.
Answer: C
Rationale: Of the $689 million total restructuring charge, only the exit costs and severance costs
must eventually be settled in cash. The asset write downs are not accrued – they reduce the assets
on the balance sheet. The company accrued $66 million + $169 million = $235 million as a liability.
Thus, if the company paid $72 million cash, the remaining accrual is $163 million at year end.
Topic: Restructuring Charges (Numerical calculations required)
LO: 2
14. Intelligentsia Corp. recorded restructuring charges of $157,028 thousand during fiscal 2012 related
entirely to anticipated employee separation payments. Intelligentsia had never before incurred
restructuring charges. At the end of the year, the company’s balance sheet included a restructuring
accrual of $19,762. The cash flow effect of Intelligentsia’s restructuring during fiscal 2012 was:
A) $19,762 thousand
B) $157,028 thousand
C) $176,790 thousand
D) $137,266 thousand
E) None of the above
Answer: D
Rationale: The total restructuring charge accrued was $157,028 of which $19,762 was still unpaid (a
liability) at the end of the year. The difference of $137,266 must have been paid in cash during the
year. The cash flow effect is $137,266.
Topic: Tax Expense (Numerical calculations required)
LO: 3
15. In fiscal 2011, Microsoft Corp. reported a statutory tax rate of 35.0%, an effective tax rate of 17.53%
and a tax rate on operating profit of 16.94%. The 2011 income statement reported income tax
expense of $4,921 million. What did Microsoft report as income before income tax expense that year?
A) $14,060 million
B) $28,071 million
C) $29,050 million
D) $7,571 million
E) None of the above
Answer: B
Rationale: Microsoft reported income before income tax expense of $28,071 million. This is calculated
as Income tax expense / Effective tax rate = $4,921 million / 0.1753 = $28,071 million.
[Show More]

.png)

.png)


.png)
 Janice Loftus, Ken Leo, Sorin Daniliuc, Noel Boys, Belinda Luke, Hong Ang, Karyn Byrnes (Test Bank).png)
.png)
.png)

.png)