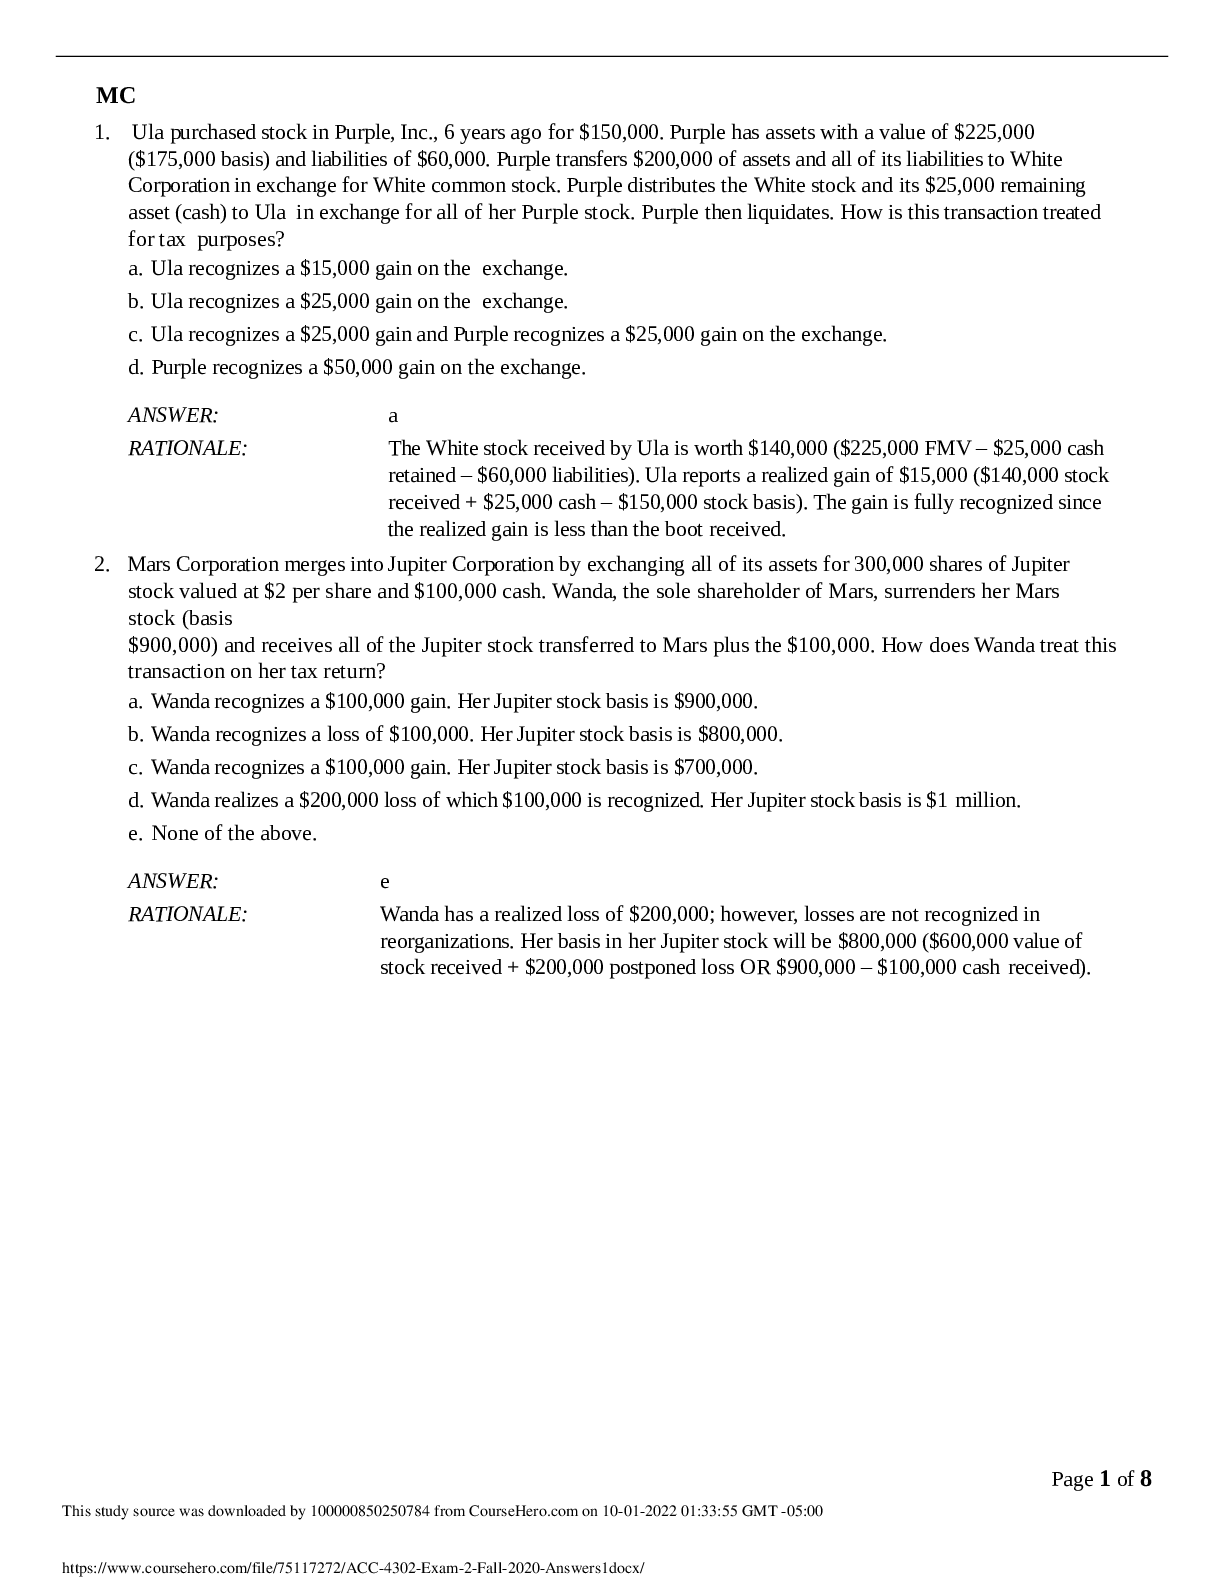
Financial Accounting > EXAM > ACC 4302 Exam # 2 Fall 2020 Question and Answers (All)
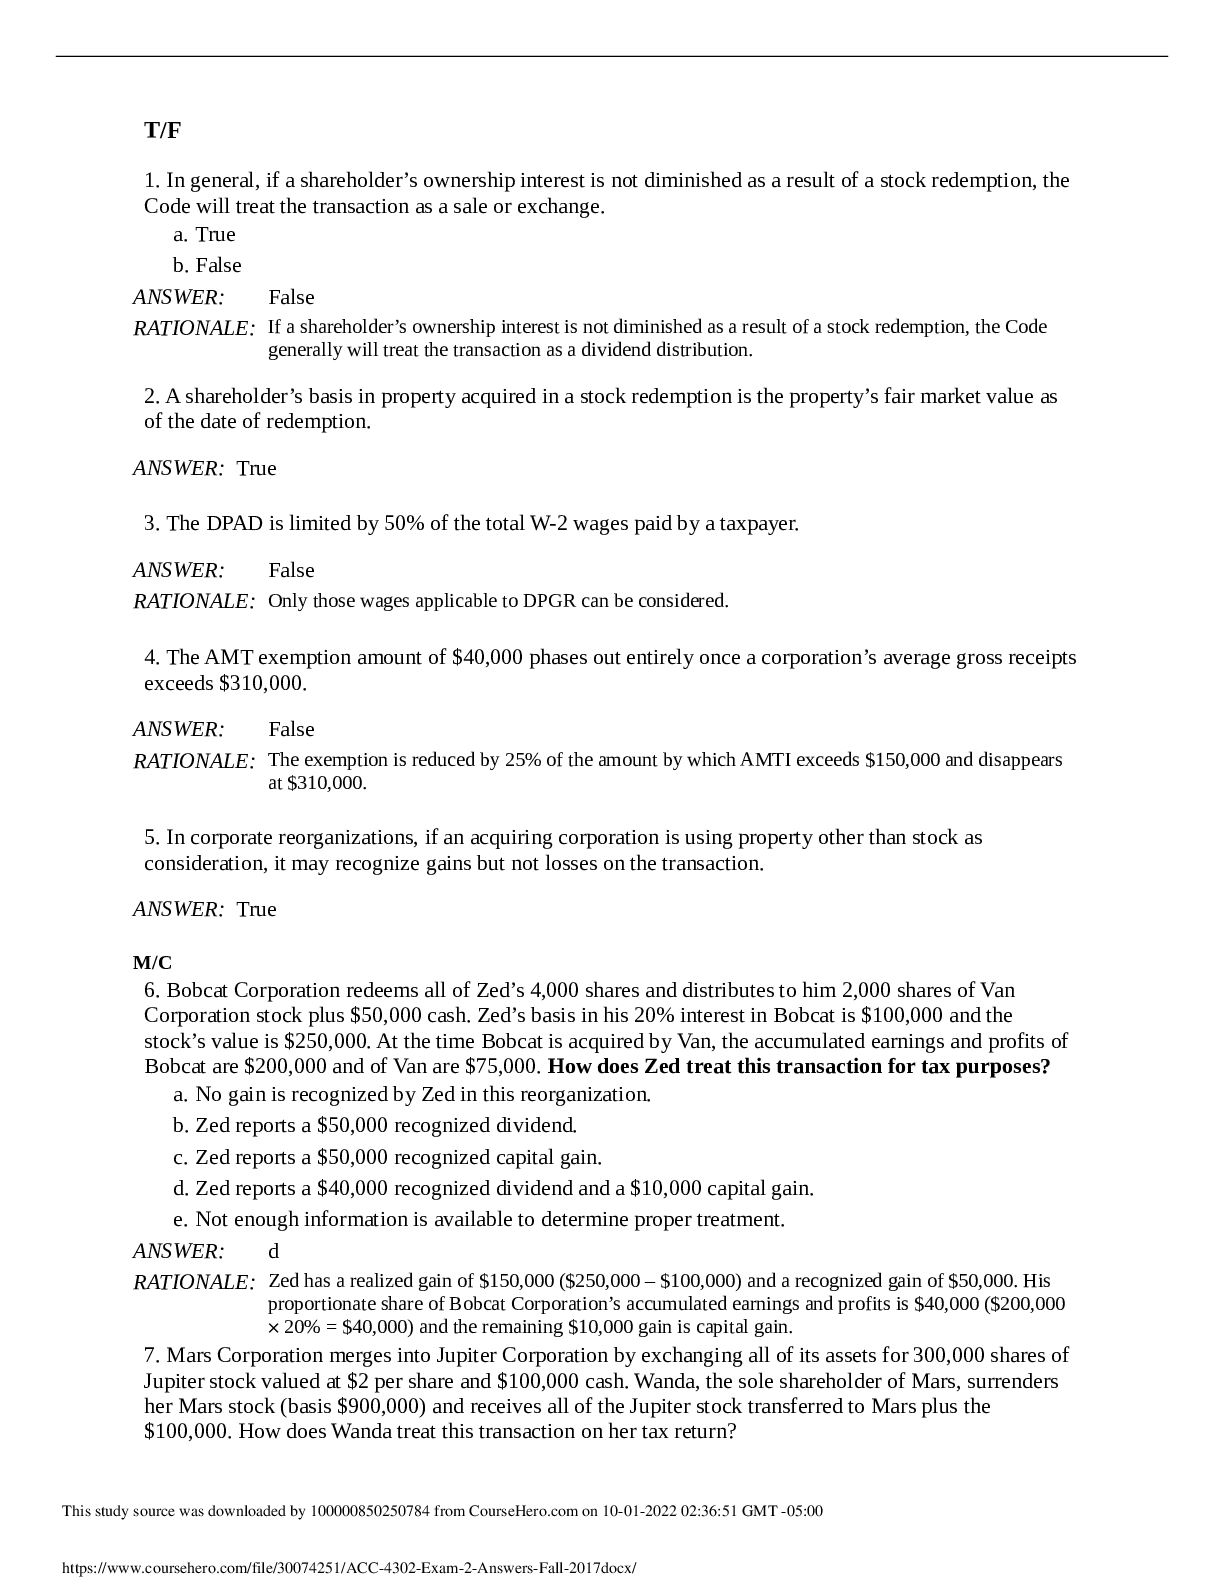
ACC 4302 Exam # 2 Fall 2020 Question and Answers
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 8 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Oct 01, 2022
Number of pages
8
Written in
All

Additional information
This document has been written for:
Uploaded
Oct 01, 2022
Downloads
0
Views
119
Topic Tags
Related Subjects & Courses
Explore similar study resources and related concepts.
Recommended For You
Get more on EXAM »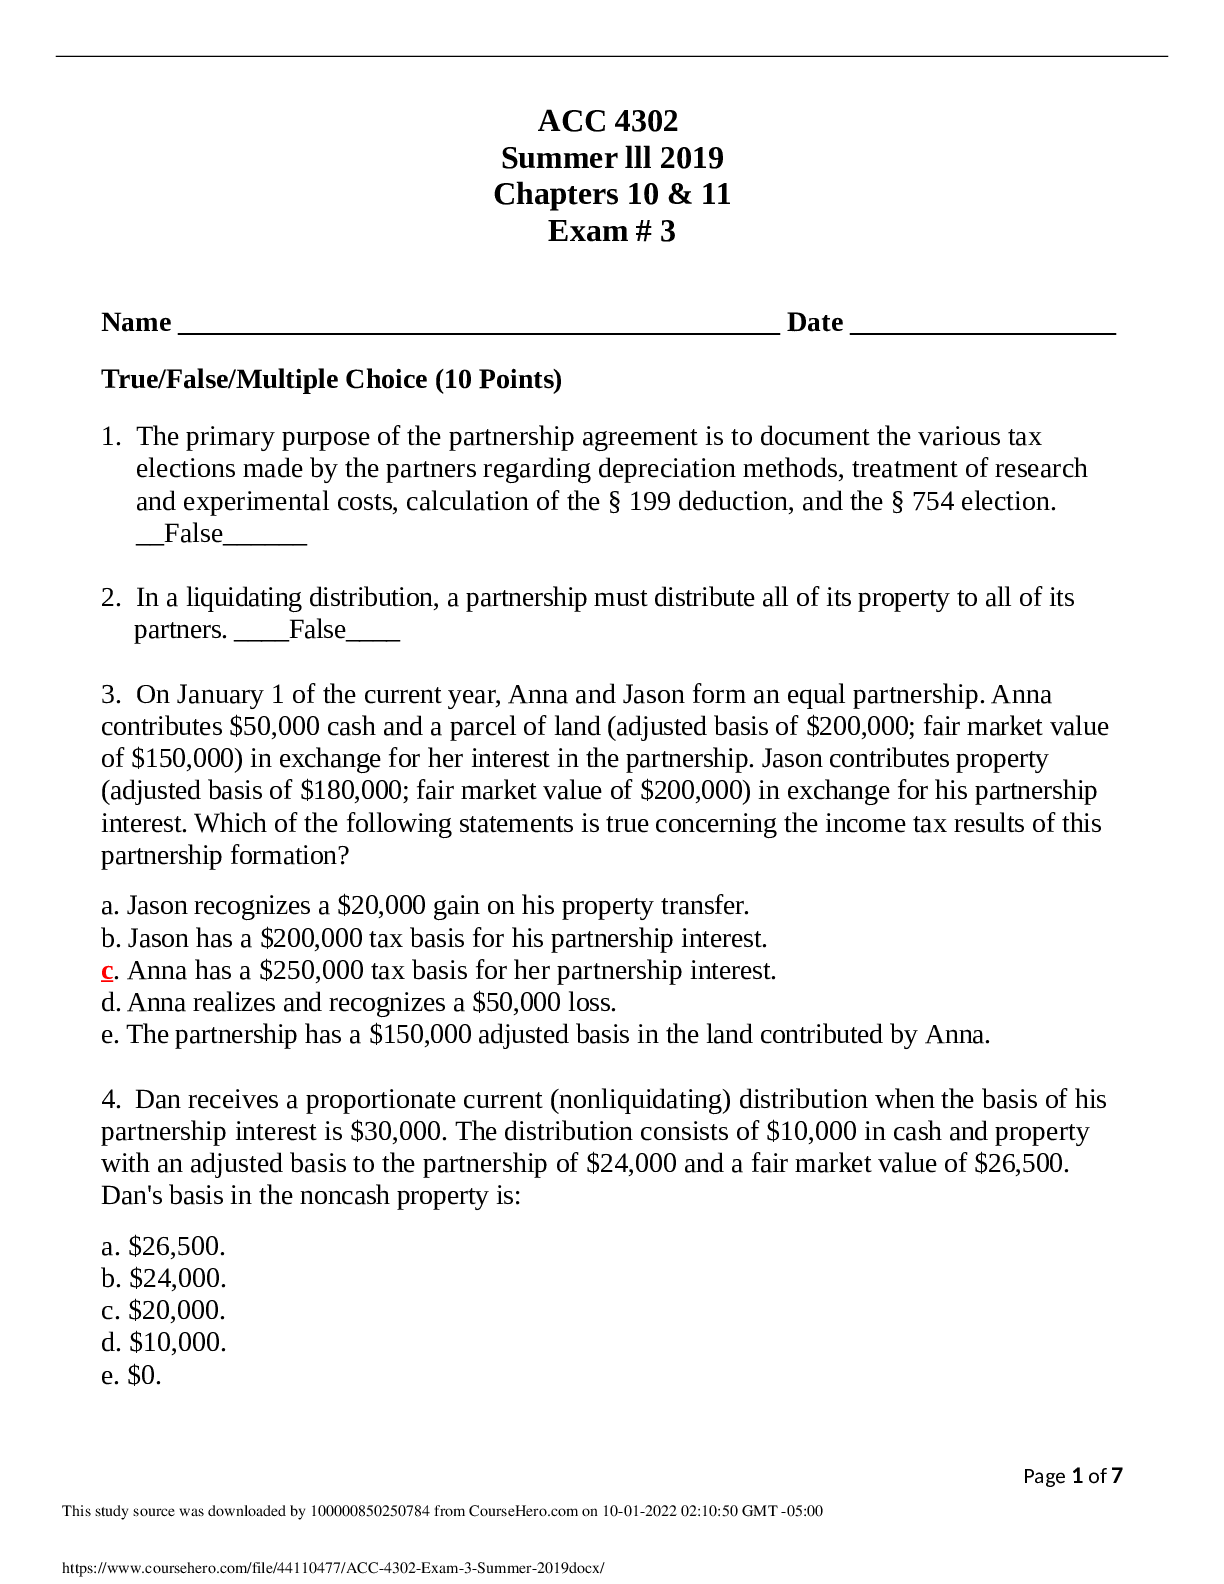
ACC 4302 Summer lll 2019 Chapters 10 & 11 Exam # 3 with CORREC...
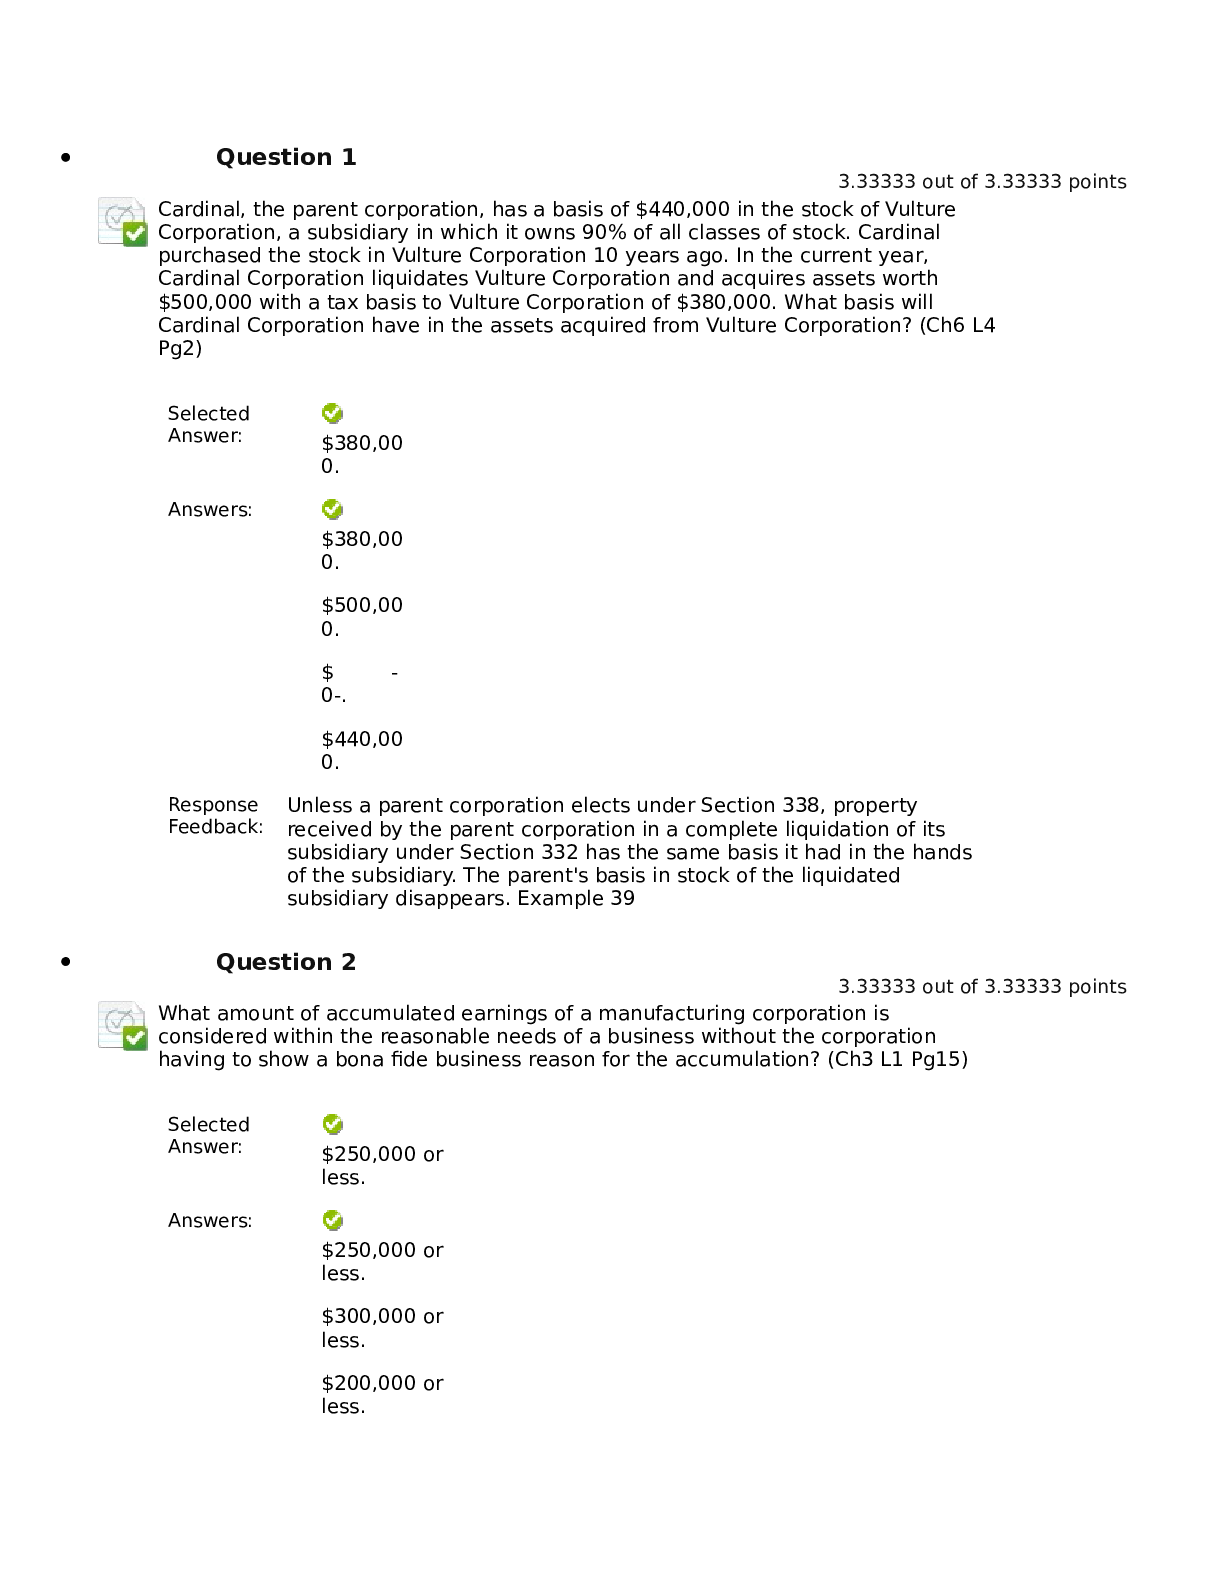

ACC 4302- Corporation Acct REVIEW EXAM 1 Questions and Answers

Financial Accounting with International Financial Reporting St...

Solutions Manual for Advanced Accounting, 8th Edition by Debra...

Advanced Accounting 4th Edition By Hamlen, Huefner, Largay (Te...
 1e Gail Fayerman.png)
Advanced Accounting, Canadian Edition (Updated Version) 1st Ed...
.png)
Test Bank for Advanced Accounting, 14th Edition by Joe Ben Hoy...
Advanced Accounting 7th Edition By Debra Jeter, Paul Chaney (T...

Advanced Accounting 5th Edition By Susan Hamlen - TEST BANK [A...

Financial Accounting Tools for Business Decision Making 8th Ca...
Understanding Financial Accounting, 3rd Canadian Edition by Ch...
Intermediate Accounting, 18th Edition by Donald E. Kieso eBook

Income Tax Fundamentals 2023, 41e Gerald Whittenburg, Steven G...
, 13th Canadian Edition by Donald Kieso.png)
Intermediate Accounting, (Volume 2), 13th Canadian Edition by...
,+13th Canadian Edition by Donald Kieso.png)
Intermediate Accounting (Volume+1), 13th Canadian Edition by D...
Financial Accounting with International Financial Reporting St...

.png)
.png)
.png)