COST ACCOUNTING
Job Order Costing
Job Order Costing – is a system for allocating costs to groups of unique product. It is applicable to the production of
customer specified products such as the manufacture of special
...
COST ACCOUNTING
Job Order Costing
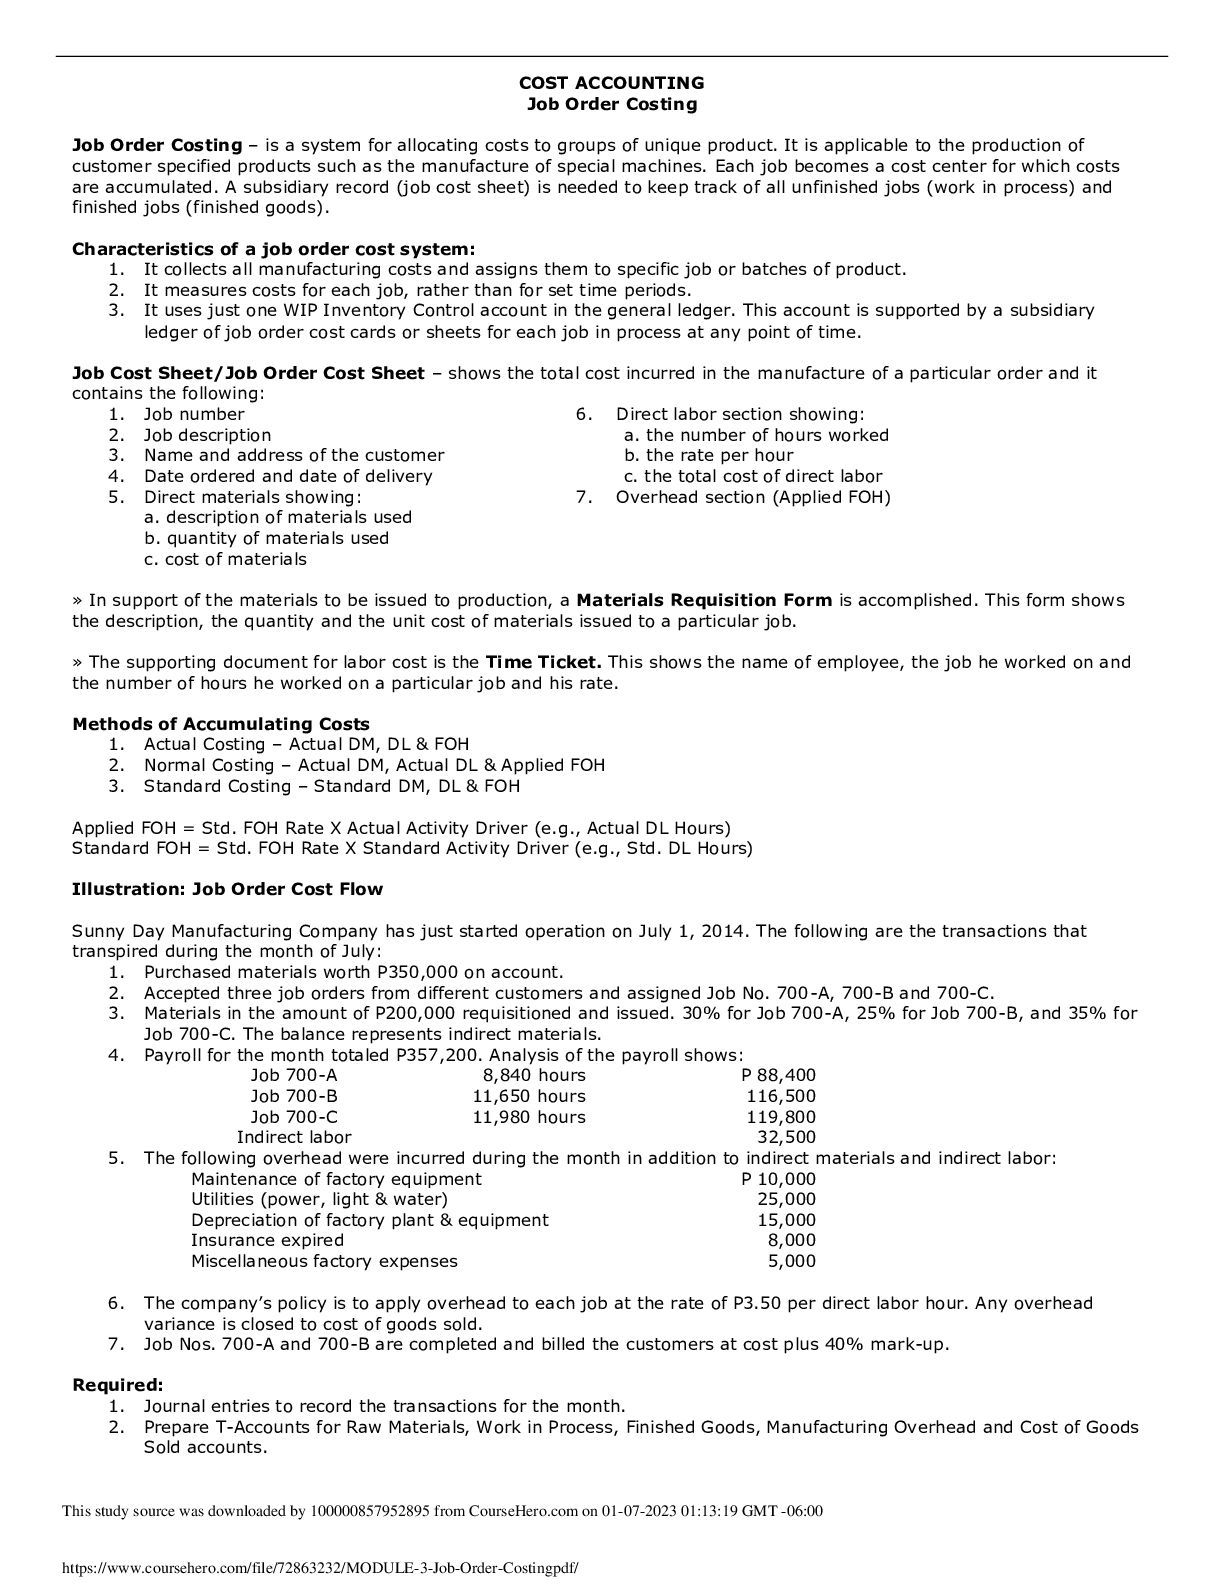
Job Order Costing – is a system for allocating costs to groups of unique product. It is applicable to the production of
customer specified products such as the manufacture of special machines. Each job becomes a cost center for which costs
are accumulated. A subsidiary record (job cost sheet) is needed to keep track of all unfinished jobs (work in process) and
finished jobs (finished goods).
Characteristics of a job order cost system:
1. It collects all manufacturing costs and assigns them to specific job or batches of product.
2. It measures costs for each job, rather than for set time periods.
3. It uses just one WIP Inventory Control account in the general ledger. This account is supported by a subsidiary
ledger of job order cost cards or sheets for each job in process at any point of time.
Job Cost Sheet/Job Order Cost Sheet – shows the total cost incurred in the manufacture of a particular order and it
contains the following:
1. Job number 6. Direct labor section showing:
2. Job description a. the number of hours worked
3. Name and address of the customer b. the rate per hour
4. Date ordered and date of delivery c. the total cost of direct labor
5. Direct materials showing: 7. Overhead section (Applied FOH)
a. description of materials used
b. quantity of materials used
c. cost of materials
» In support of the materials to be issued to production, a Materials Requisition Form is accomplished. This form shows
the description, the quantity and the unit cost of materials issued to a particular job.
» The supporting document for labor cost is the Time Ticket. This shows the name of employee, the job he worked on and
the number of hours he worked on a particular job and his rate.
Methods of Accumulating Costs
1. Actual Costing – Actual DM, DL & FOH
2. Normal Costing – Actual DM, Actual DL & Applied FOH
3. Standard Costing – Standard DM, DL & FOH
Applied FOH = Std. FOH Rate X Actual Activity Driver (e.g., Actual DL Hours)
Standard FOH = Std. FOH Rate X Standard Activity Driver (e.g., Std. DL Hours)
Illustration: Job Order Cost Flow
Sunny Day Manufacturing Company has just started operation on July 1, 2014. The following are the transactions that
transpired during the month of July:
1. Purchased materials worth P350,000 on account.
2. Accepted three job orders from different customers and assigned Job No. 700-A, 700-B and 700-C.
3. Materials in the amount of P200,000 requisitioned and issued. 30% for Job 700-A, 25% for Job 700-B, and 35% for
Job 700-C. The balance represents indirect materials.
4. Payroll for the month totaled P357,200. Analysis of the payroll shows:
Job 700-A 8,840 hours P 88,400
Job 700-B 11,650 hours 116,500
Job 700-C 11,980 hours 119,800
Indirect labor 32,500
5. The following overhead were incurred during the month in addition to indirect materials and indirect labor:
Maintenance of factory equipment P 10,000
Utilities (power, light & water) 25,000
Depreciation of factory plant & equipment 15,000
Insurance expired 8,000
Miscellaneous factory expenses 5,000
6. The company’s policy is to apply overhead to each job at the rate of P3.50 per direct labor hour. Any overhead
variance is closed to cost of goods sold.
7. Job Nos. 700-A and 700-B are completed and billed the customers at cost plus 40% mark-up.
Required:
1. Journal entries to record the transactions for the month.
2. Prepare T-Accounts for Raw Materials, Work in Process, Finished Goods, Manufacturing Overhead and Cost of Goods
Sold accounts.
[Show More]