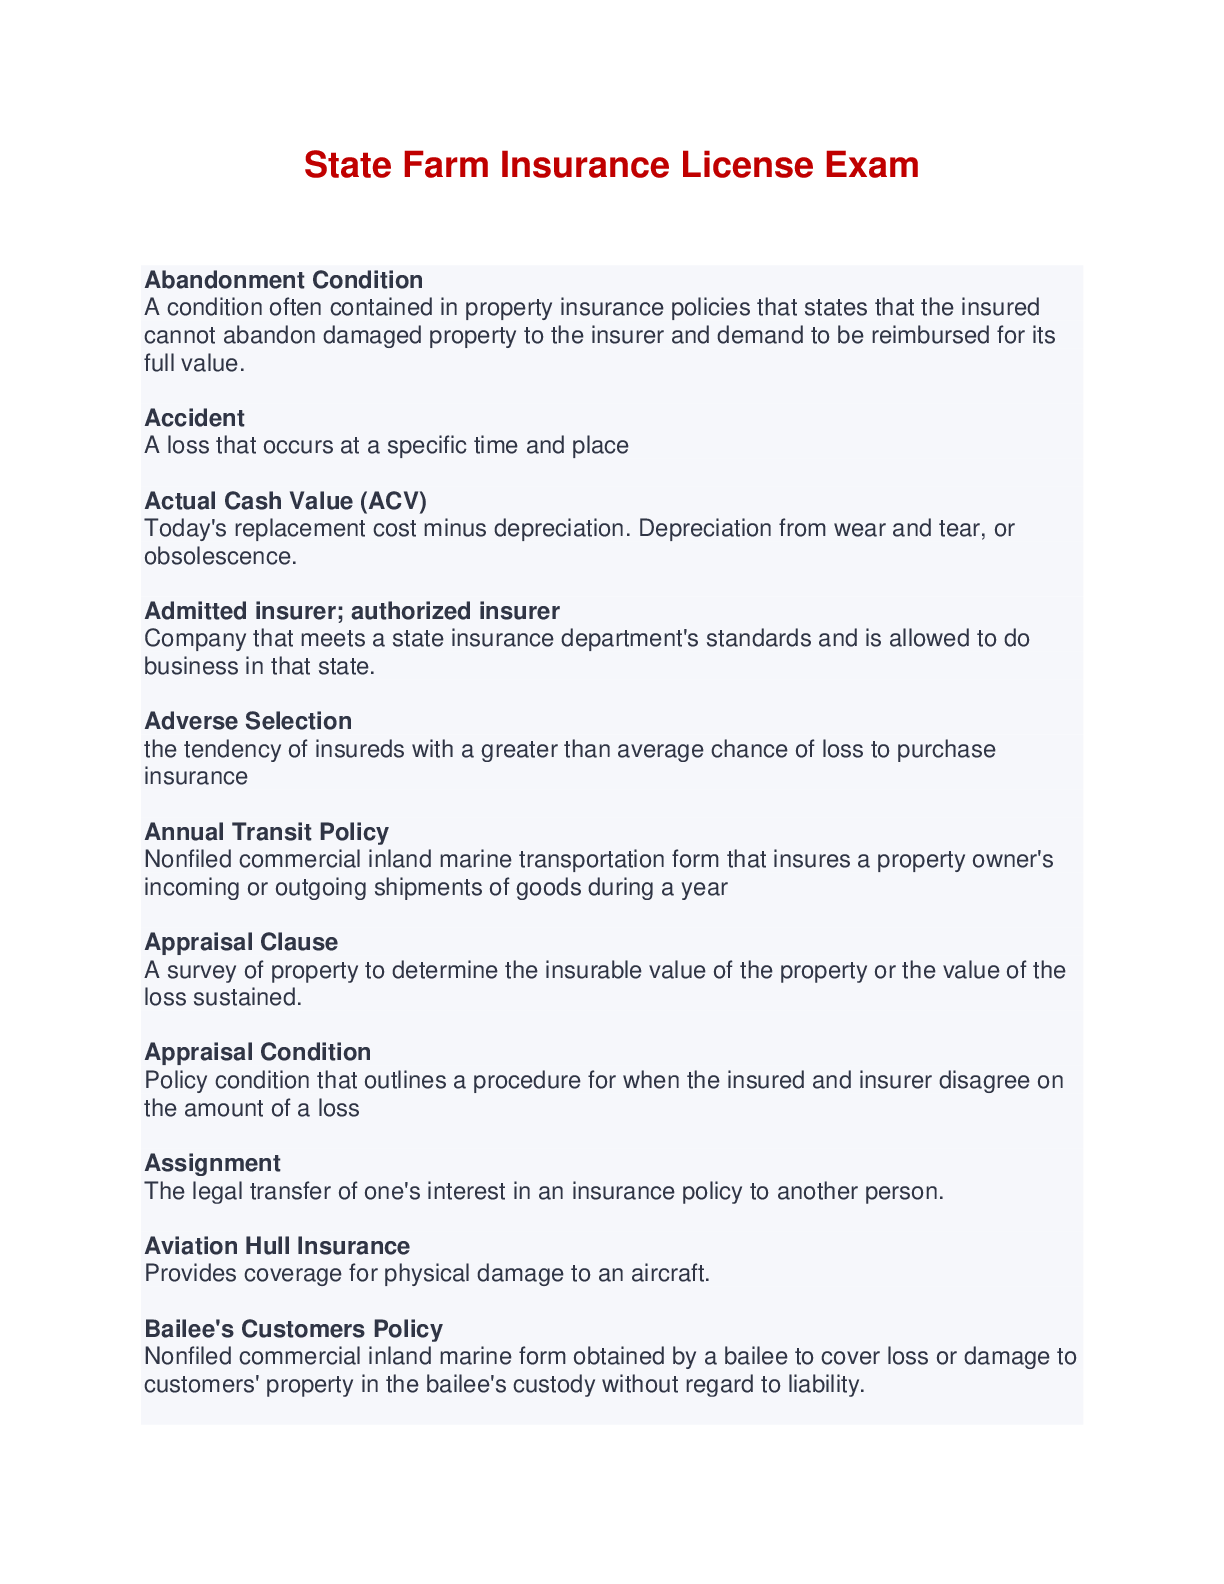
Abandonment Condition Ans- A condition often contained in property insurance policies that
states that the insured cannot abandon damaged property to the insurer and demand to be
reimbursed for its full value.
Accid
...
Abandonment Condition Ans- A condition often contained in property insurance policies that
states that the insured cannot abandon damaged property to the insurer and demand to be
reimbursed for its full value.
Accident Ans- A loss that occurs at a specific time and place
Actual Cash Value (ACV) Ans- Today's replacement cost minus depreciation. Depreciation from
wear and tear, or obsolescence.
admitted insurer; authorized insurer Ans- Company that meets a state insurance department's
standards and is allowed to do business in that state.
Adverse Selection Ans- the tendency of insureds with a greater than average chance of loss to
purchase insurance
Annual Transit Policy Ans- Nonfiled commercial inland marine transportation form that insures
a property owner's incoming or outgoing shipments of goods during a year
Appraisal Clause Ans- A survey of property to determine the insurable value of the property or
the value of the loss sustained.
Appraisal Condition Ans- Policy condition that outlines a procedure for when the insured and
insurer disagree on the amount of a loss
Assignment Ans- The legal transfer of one's interest in an insurance policy to another person.
Aviation Hull Insurance Ans- Provides coverage for physical damage to an aircraft.
Bailee's Customers Policy Ans- Nonfiled commercial inland marine form obtained by a bailee to
cover loss or damage to customers' property in the bailee's custody without regard to liability.
Appurtenant Structures Ans- Buildings of lesser value that are on the same premises as the main
building insured under a property policy; they are usually covered by the policy.
Assignment Condition Ans- Condition in insurance policies that specifies that the policy cannot
be transferred to another unless the company consents to the transfer in writing.
Bailee Ans- A person or organization that has temporary possession of someone else's personal
property.
Basic Perils in Homeowners Policy Ans- There are 14 perils. Fire, lightening, riot, explosion,
vehicles, volcanic eruption, civil commotion, smoke, hail, aircraft, windstorm, vandalism,
malicious mischief, theft.
Basic Property Policy Structure (DICEE) Ans- D - Declarations
I - Insuring agreement
C - Conditions
E - Exclusions
E - Endorsements
Blanket Insurance Ans- Type of insurance policy that covers more than one item of property at a
single location or one or more items of property at multiple locations
Builders Risk Coverage Form Ans- Commercial property coverage forms that covers
commercial, residential, or farm buildings that are under construction or during remodeling.
Cargo Insurance Ans- Type of ocean marine insurance that covers goods while they are in transit
over water.
Binder Ans- Oral or written statement that provides immediate insurance protection for a
specified period; designed to provide temporary coverage until a policy is issued or denied.
BOP Ans- Package policy designed to provide broad property and liability coverage for small
businesses; eligibility requirements are stricter than the CPP.
Business Income Policy Ans- Pays for loss of income that the insured sustains due to a direct
physical loss from a covered peril that forces the insured to suspend operations until the property
can be repaired, rebuilt, or replaced with reasonable speed; available with or without extra
expense coverage.
Causes of Loss Form Ans- Separate form used with the commercial property coverage part of the
commercial package policy that lists covered perils and exclusions. Several different versions
provide increasingly broader coverage from basic to broad to special.
Condominium Association Coverage Form Ans- Commercial Property coverage form that covers
the buildings in a condominium complex. Does not cover condominium owner's personal
property.
Coverage D on a HO Policy - Loss of Use Ans- If property loss makes the residence premises
uninhabitable, the additional living expenses are covered; or if a covered loss to the insured's
property makes a part of the residence premises uninhabitable that is rented to others or held for
rental by the insured, this coverage will pay the fair rental value.
coverages excluded on dwelling policy Ans- Theft, vandalism, and malicious mischief excluded
on basic policy. Liability excluded on all policies.
Coverage B of homeowners pol
[Show More]


.png)

.png)


.png)
.png)