Auditing > TEST BANKS > Test Bank Auditing and Assurance Services, 17e Arens Elder Beasley (All)
Test Bank Auditing and Assurance Services, 17e Arens Elder Beasley
Document Content and Description Below
Last updated: 10 months ago
Preview 5 out of 1049 pages
Instant download

Loading document previews ...
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Oct 31, 2025
Number of pages
1049
Written in
All

Additional information
This document has been written for:
Uploaded
Oct 31, 2025
Downloads
0
Views
45
Topic Tags
Related Subjects & Courses
Explore similar study resources and related concepts.
Recommended For You
Get more on TEST BANKS »
Solution Manual for Auditing & Assurance Services: A Systemati...
Auditing & Assurance Services, 9e Louwers, Bagley, Blay, Straw...
Auditing and Assurance Services An Integrated Approach (Global...

TEST BANK for Auditing and Assurance Services, 17th Global Edi...
test bank for Auditing assurance services 5th edition louwers
Auditing assurance services william messier 11th edition test...
Auditing & Assurance Services 8th Edition Timothy Louwers | Te...
Auditing & Assurance Services, 9e Louwers, Bagley, Blay, Straw...
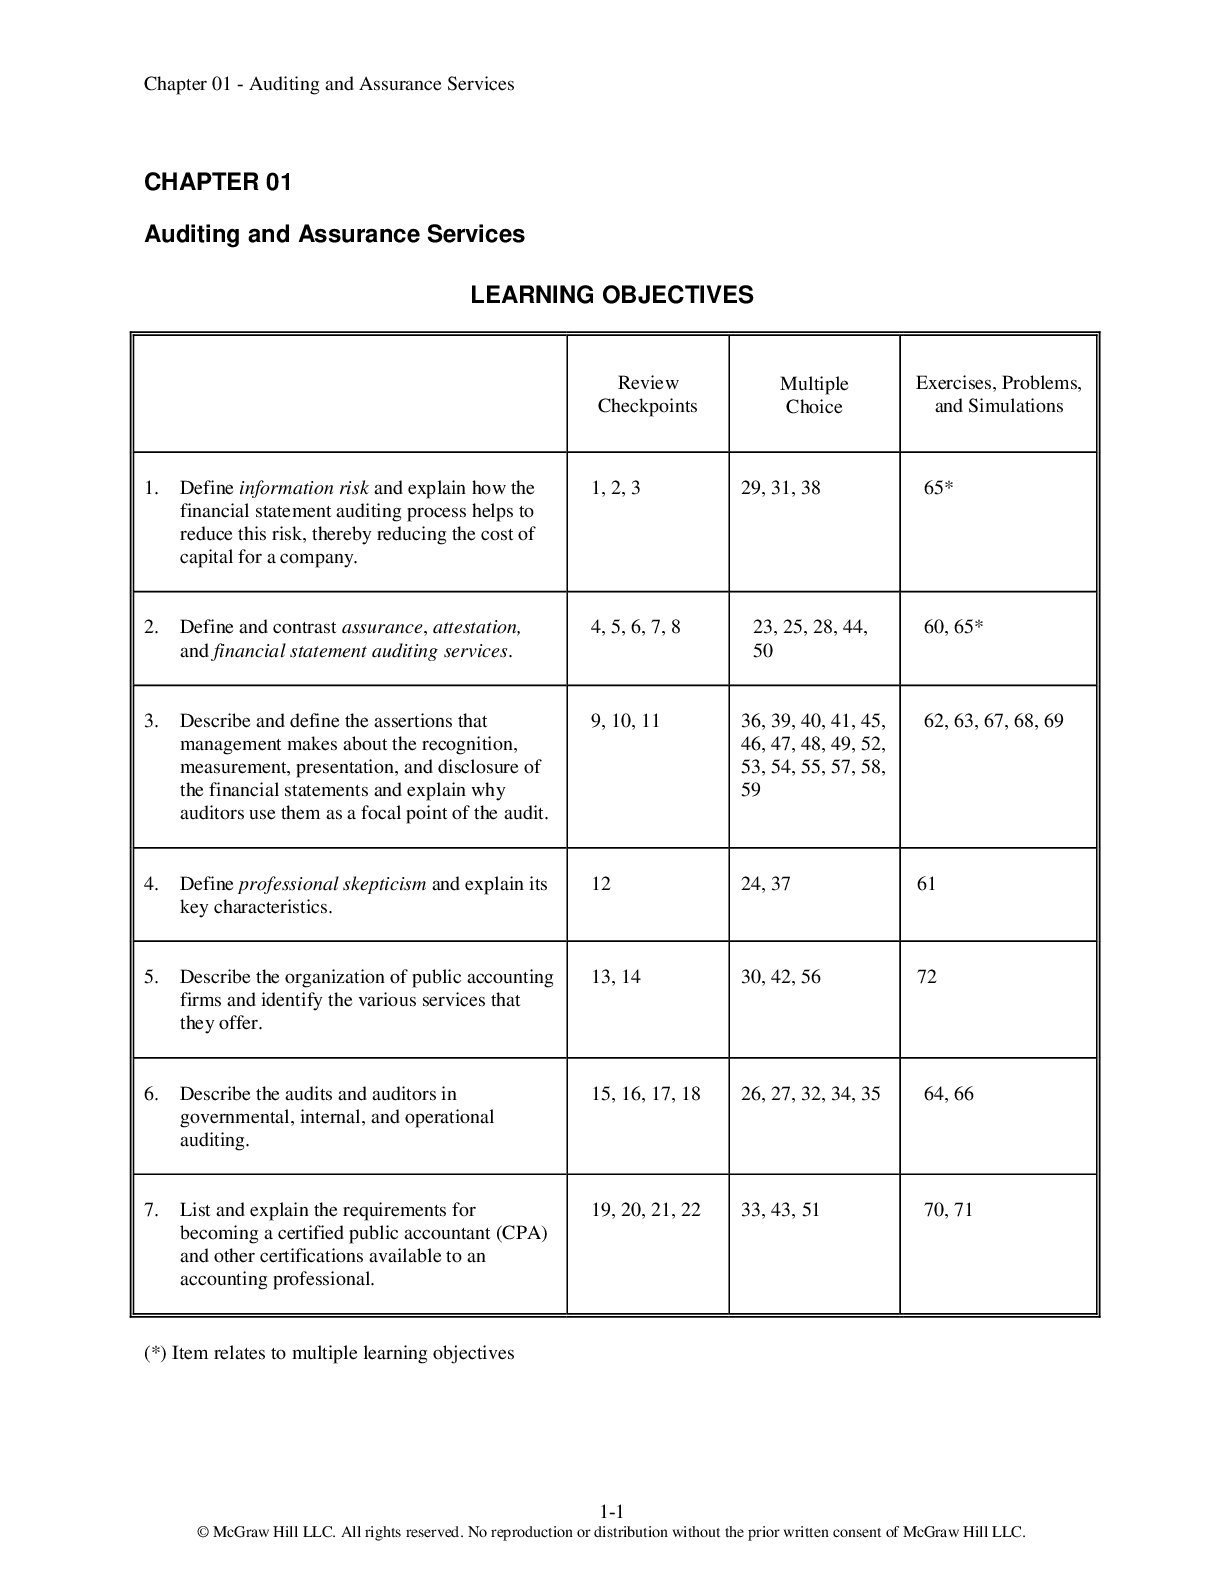
Solution Manual For Auditing Assurance Services 9th Edition By...
SOLUTIONS MANUAL for Auditing & Assurance Services 9th Editio...
SOLUTIONS MANUAL for Auditing & Assurance Services 8th Edition...
eBook AUDITING ASSURANCE SERVICES 8th Edition By Timothy Louwe...


Solution Manual for Principles of Auditing & Other Assurance S...