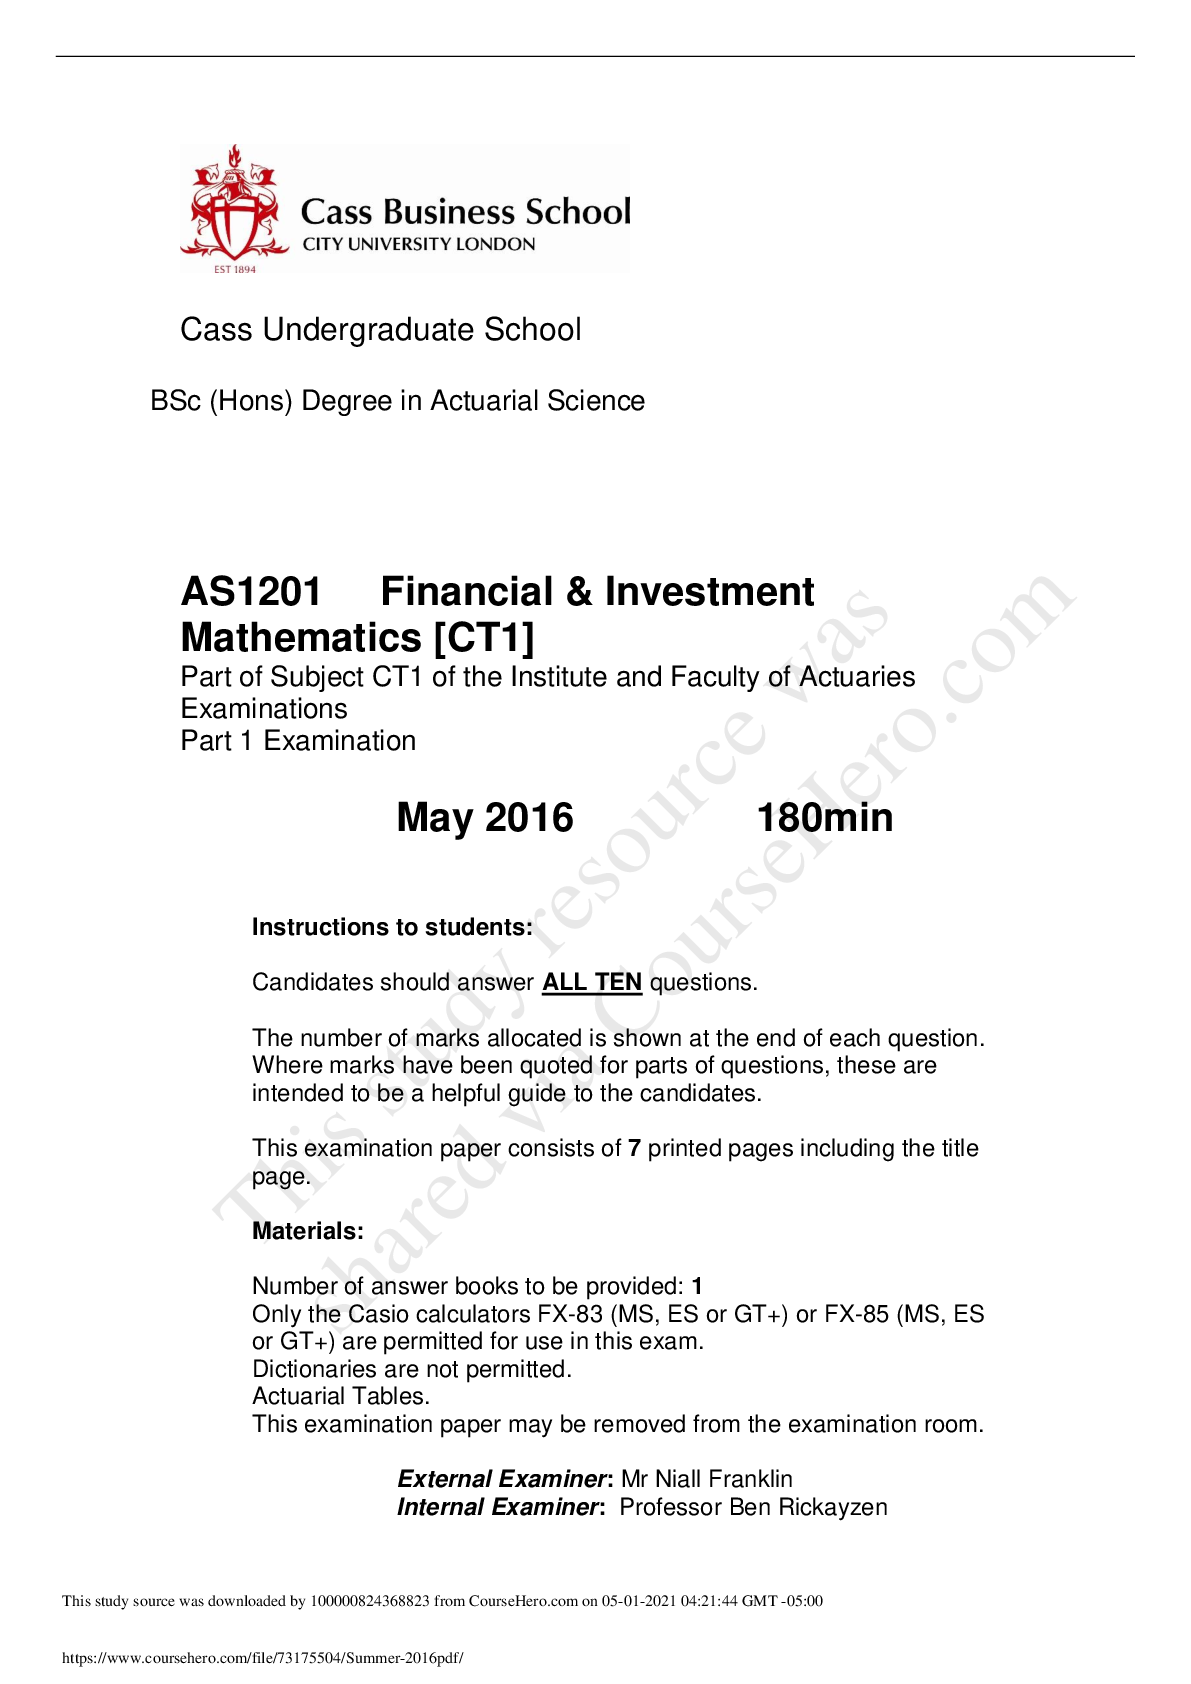
FINAL EXAM FOR AS1201 Financial & Investment Mathematics [CT1]...SUMMER 2019
Document Content and Description Below
Part of Subject CT1 of the Institute and Faculty of Actuaries Examinations
Part 1 Examination
26th May 2020 10:00 – 13:00
Instructions to students:
Candidates should answer ALL NINE questions.
The number of marks al
...
[Show More]
Last updated: 4 years ago
Preview 1 out of 7 pages
Instant download

Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
May 01, 2021
Number of pages
7
Written in
All

Additional information
This document has been written for:
Uploaded
May 01, 2021
Downloads
0
Views
134
Topic Tags
Recommended For You
Get more on EXAM »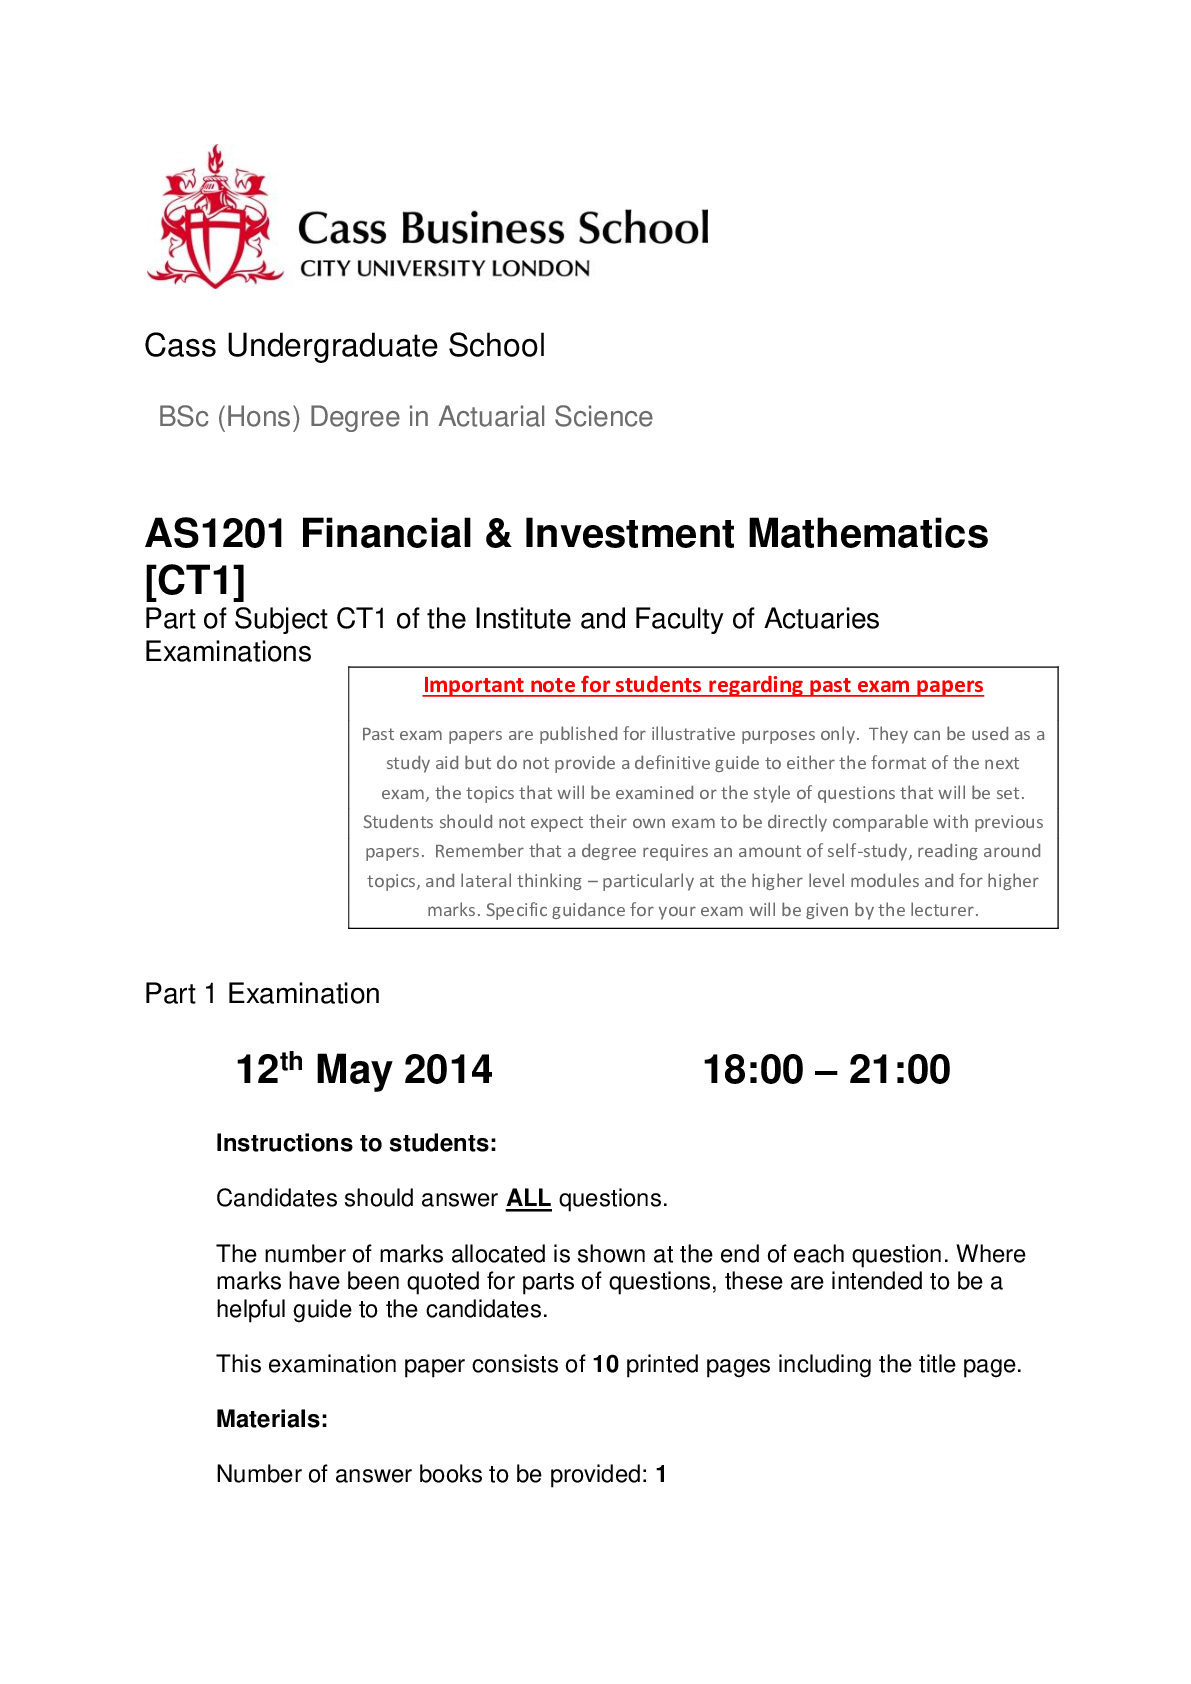
$7
11 Pages
The City College of New York, CUNY<<<FINANCE AS1201 Financial...
$5
7 Pages
FINAL EXAM FOR AS1201 Financial & Investment....EDITED 2021

$6
3 Pages
FINM 1001 Foundations of Finance: Financial Mathematics: Solut...
$11
12 Pages
SAN DIEGO STATE UNIVERSITY (SDSU) FIN 323 TEST EXAM 1 PREP LAT...
$11
11 Pages
BA 323 FINANCE SDSU TEST EXAM 1 LATEST 2026/2027 REAL STUDY QU...
$23
94 Pages
TEST BANK for Financial Statement Analysis A Data Analytics Ap...
$30
614 Pages
Test Bank For Financial Markets and Institutions 2024 Release...

$26
450 Pages
Solution Manual For Corporate Finance (CFIN), 7th Edition By S...
$22
679 Pages
SOLUTIONS MANUAL for Income Tax Fundamentals 2023 41st Edition...

$19
276 Pages
Solution Manual with Appendix For Income Tax Fundamentals 2023...
$19
256 Pages
TEST BANK for Income Tax Fundamentals 2023 41st Edition by Ger...
$24
804 Pages
Test Bank for International Financial Management ISE 10th Edit...
$25
473 Pages
Solution Manual For Fundamentals of Corporate Finance 2024 Rel...
$30
1047 Pages
Test Bank For Fundamentals of Corporate Finance 13th Edition B...
$22
101 Pages
SOLUTION MANUAL for Financial Statement Analysis A Data Analyt...
$23
569 Pages
SOLUTIONS MANUAL for Foundations of Finance 10th Edition Arthu...

More related documents below