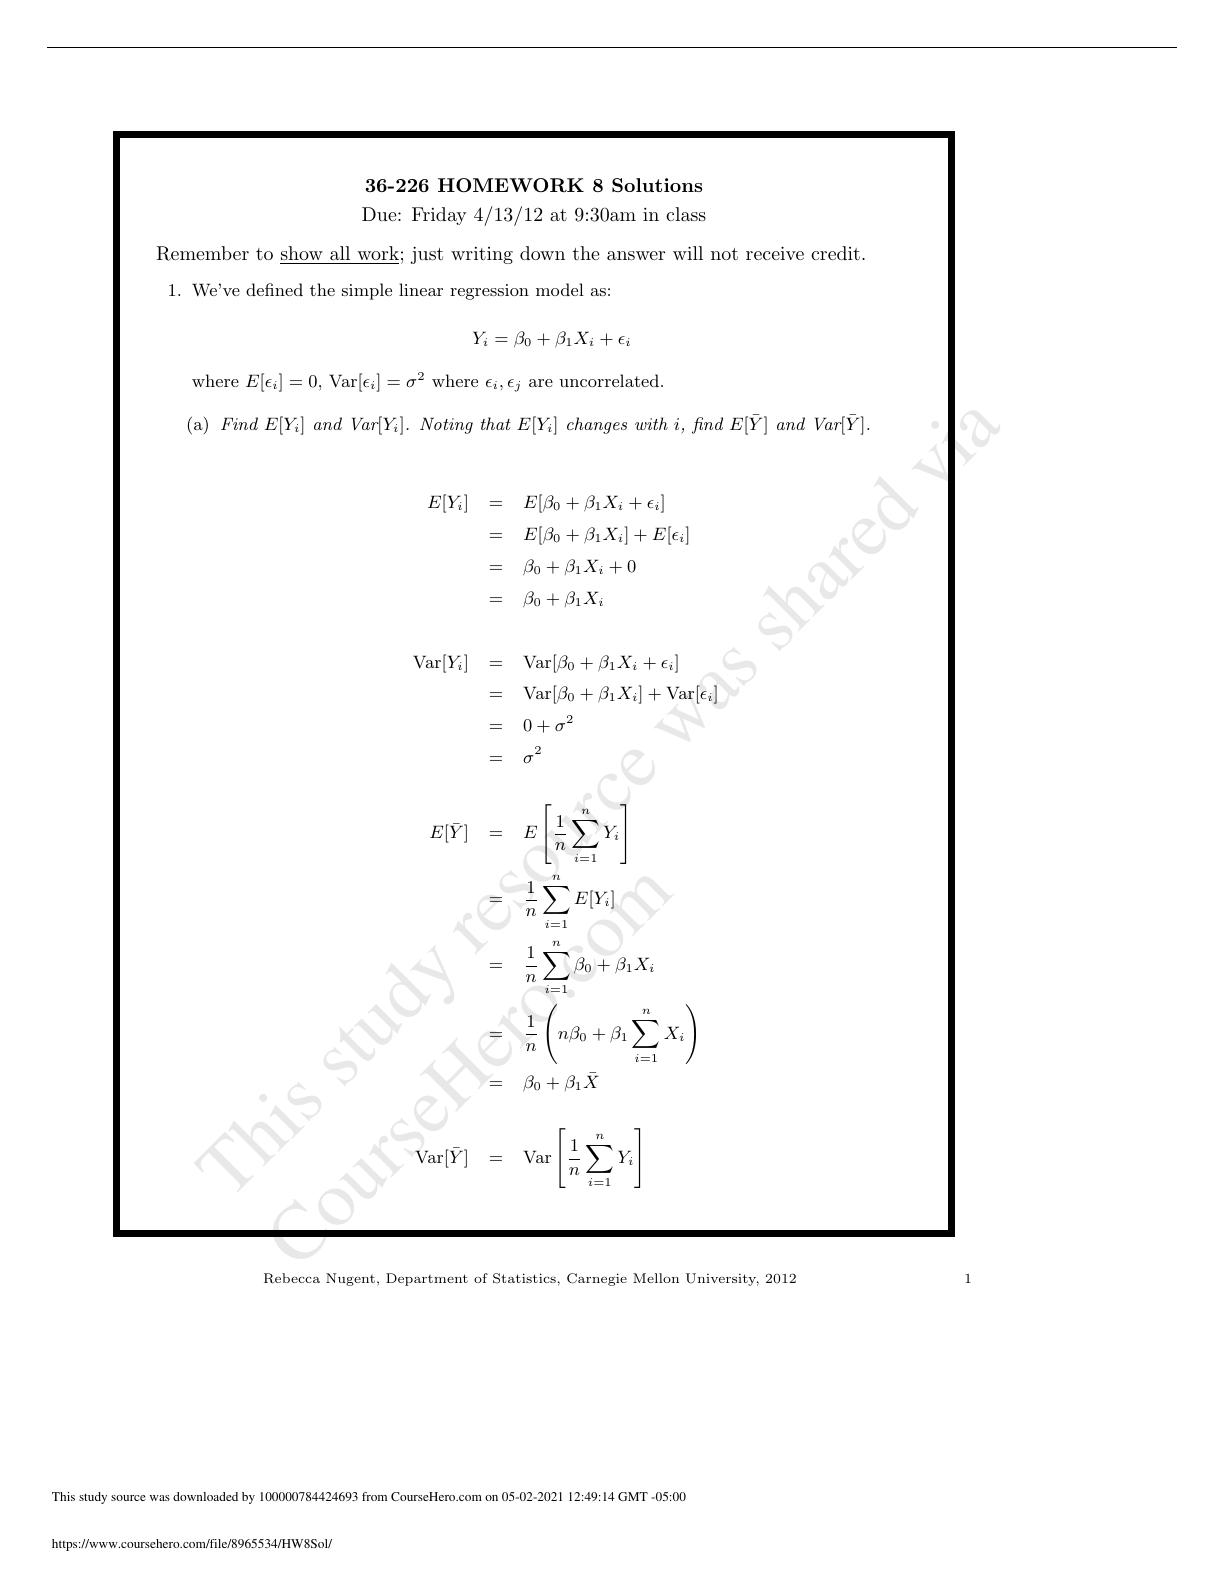
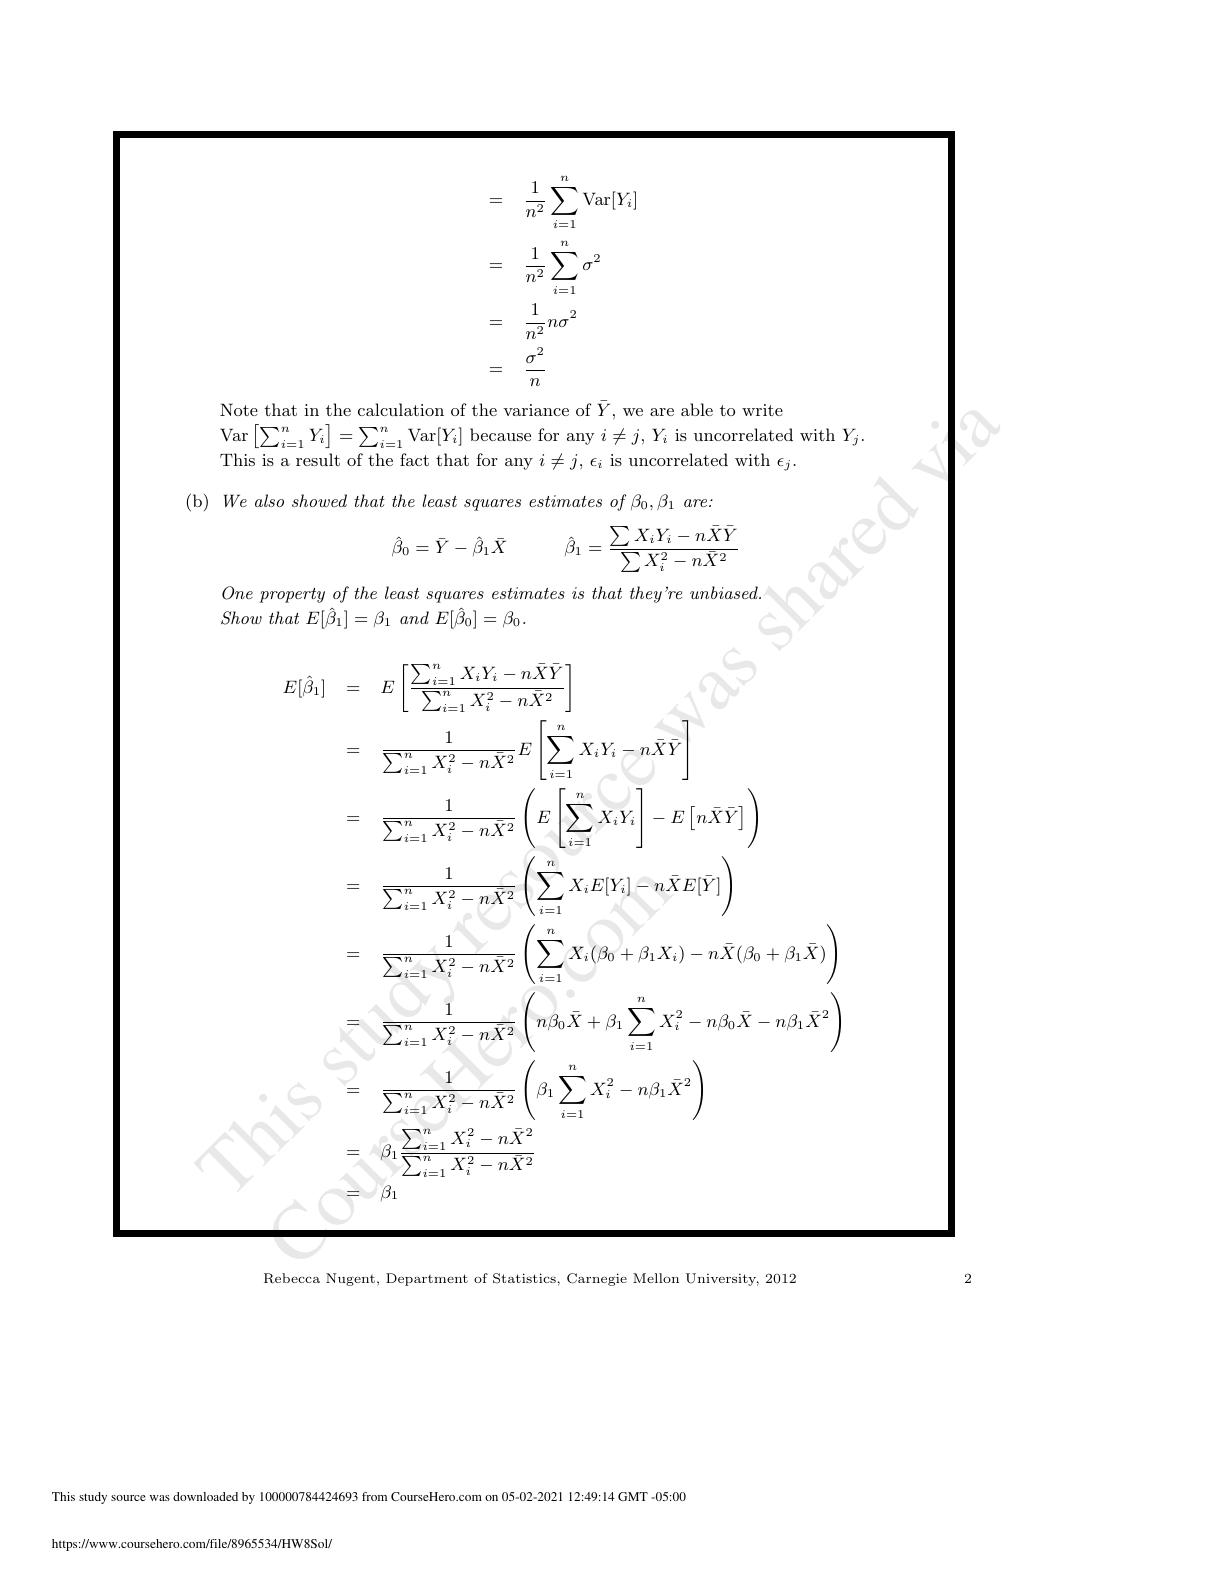
Statistics > QUESTIONS & ANSWERS > CMU 36-226: Homework 8 Solutions – Simple Linear Regression | CMU 36-226: Introduction to Statisti (All)
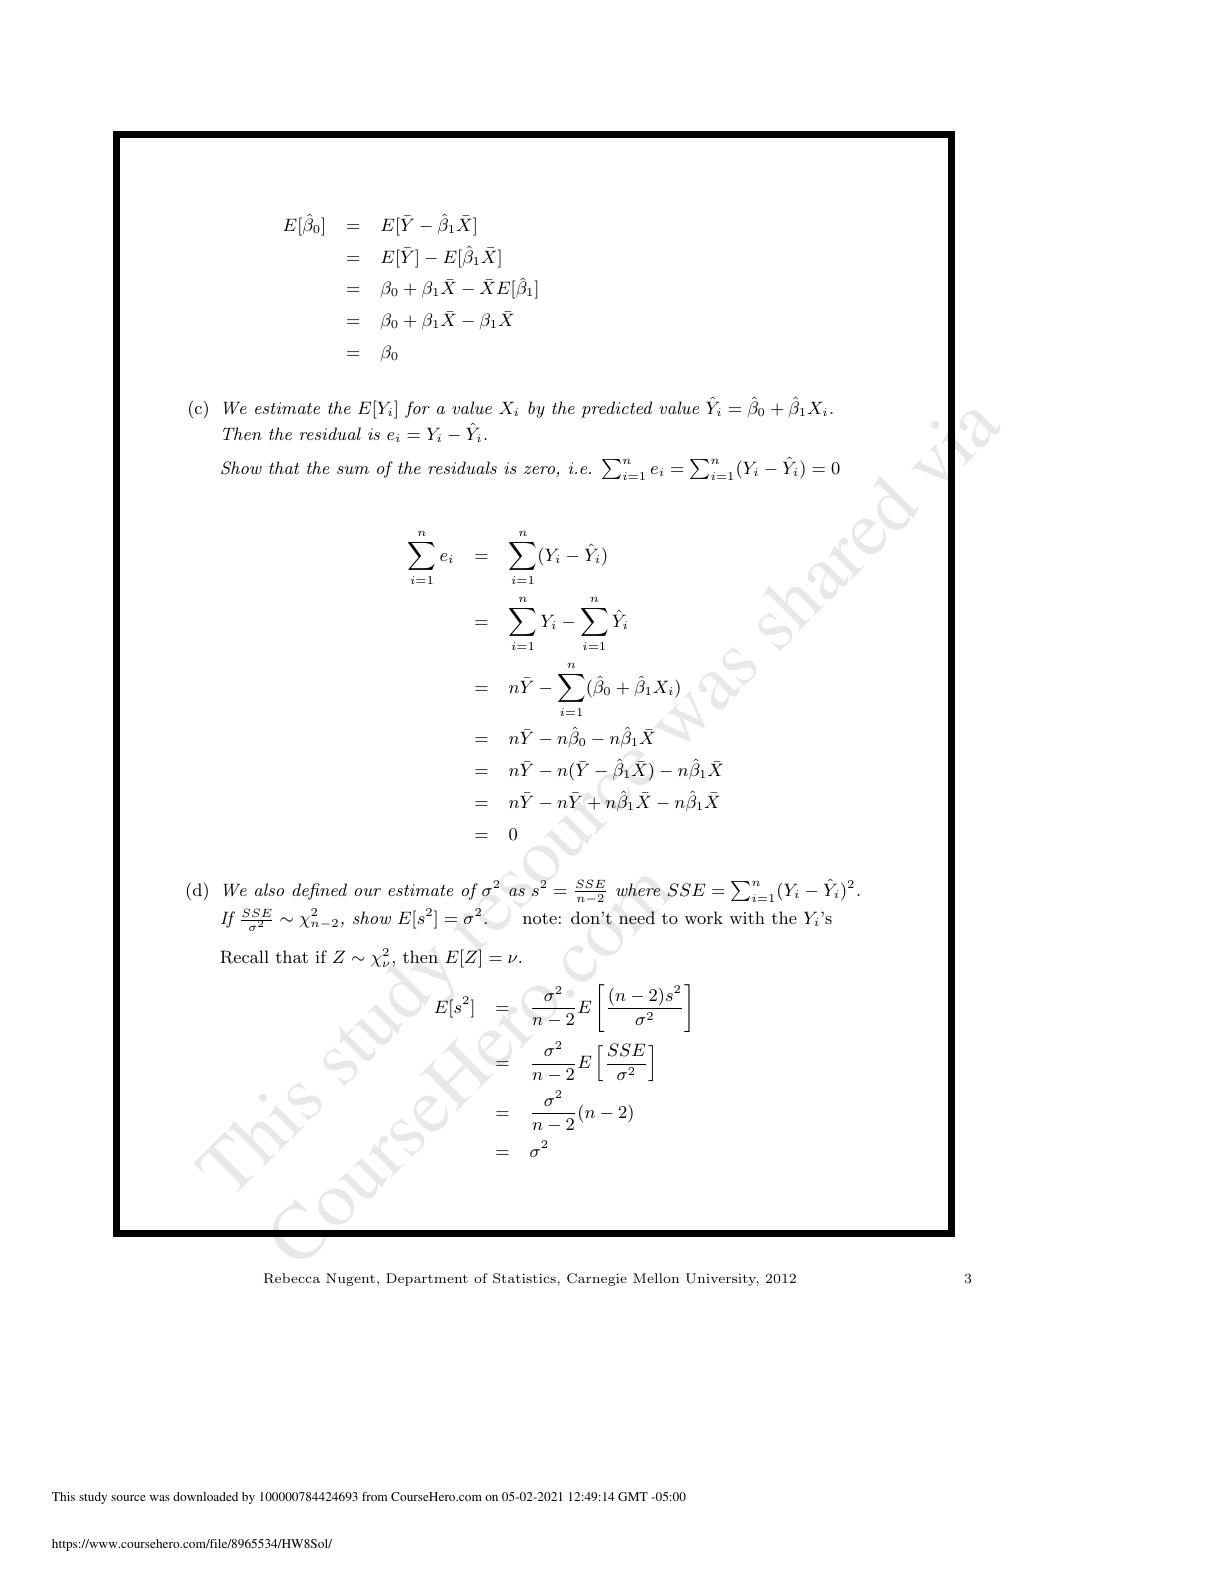
CMU 36-226: Homework 8 Solutions – Simple Linear Regression | CMU 36-226: Introduction to Statistical Inference Carnegie Mellon University
Document Content and Description Below
Last updated: 4 hours ago
Preview 3 out of 9 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Associated Textbook
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Nov 21, 2026
Number of pages
9
Written in
All

Additional information
This document has been written for:
Uploaded
Nov 21, 2026
Downloads
0
Views
8
Topic Tags
Recommended For You
Get more on QUESTIONS & ANSWERS »
PDF(ebook) Statistical Inference ,By George Casella , Roger Be...

TEST BANK for Introduction to Statistical Investigations 2nd E...

Solutions Manual for Statistical Rethinking 2nd Edition A Baye...
Simple Linear Regression: Department of Operations, Business A...
Introductory Statistics, 10th Edition By Neil A. Weiss eBook [...
TEST BANK for Advanced and Multivariate Statistical Methods, 6...

Test Bank for Advanced and Multivariate Statistical Methods Pr...

eBook Advanced and Multivariate Statistical Methods Practical...
.png)
TEST BANK for Business Statistics, 4e Norean Sharpe, Richard V...
SOLUTIONS MANUAL for Elementary Statistics: A Step by Step App...
TEST BANK FOR Essentials Of Statistics For The Behavioral Scie...
TEST BANK FOR Essentials Of Statistics For The Behavioral Sci...
Statistics and Data Analysis for Financial Engineering 2nd Edi...
Solution Manual For Statistics for Business and Economics 8th...
Solution Manual For Elementary Statistics 13th Edition by Mari...

Solutions Manual_Fundamentals of Statistics 6th Edition By Mic...

eBook [PDF] Dynamic Equations on Time Scales and Applications...
An Introduction to Statistical Concepts 4th Edition By Debbi...