Financial Accounting > TEST BANKS > Test Bank-2020-Financial Accounting-Meaning.Nature & Role-Chapter 20- Accounting Changes and Errors (All)
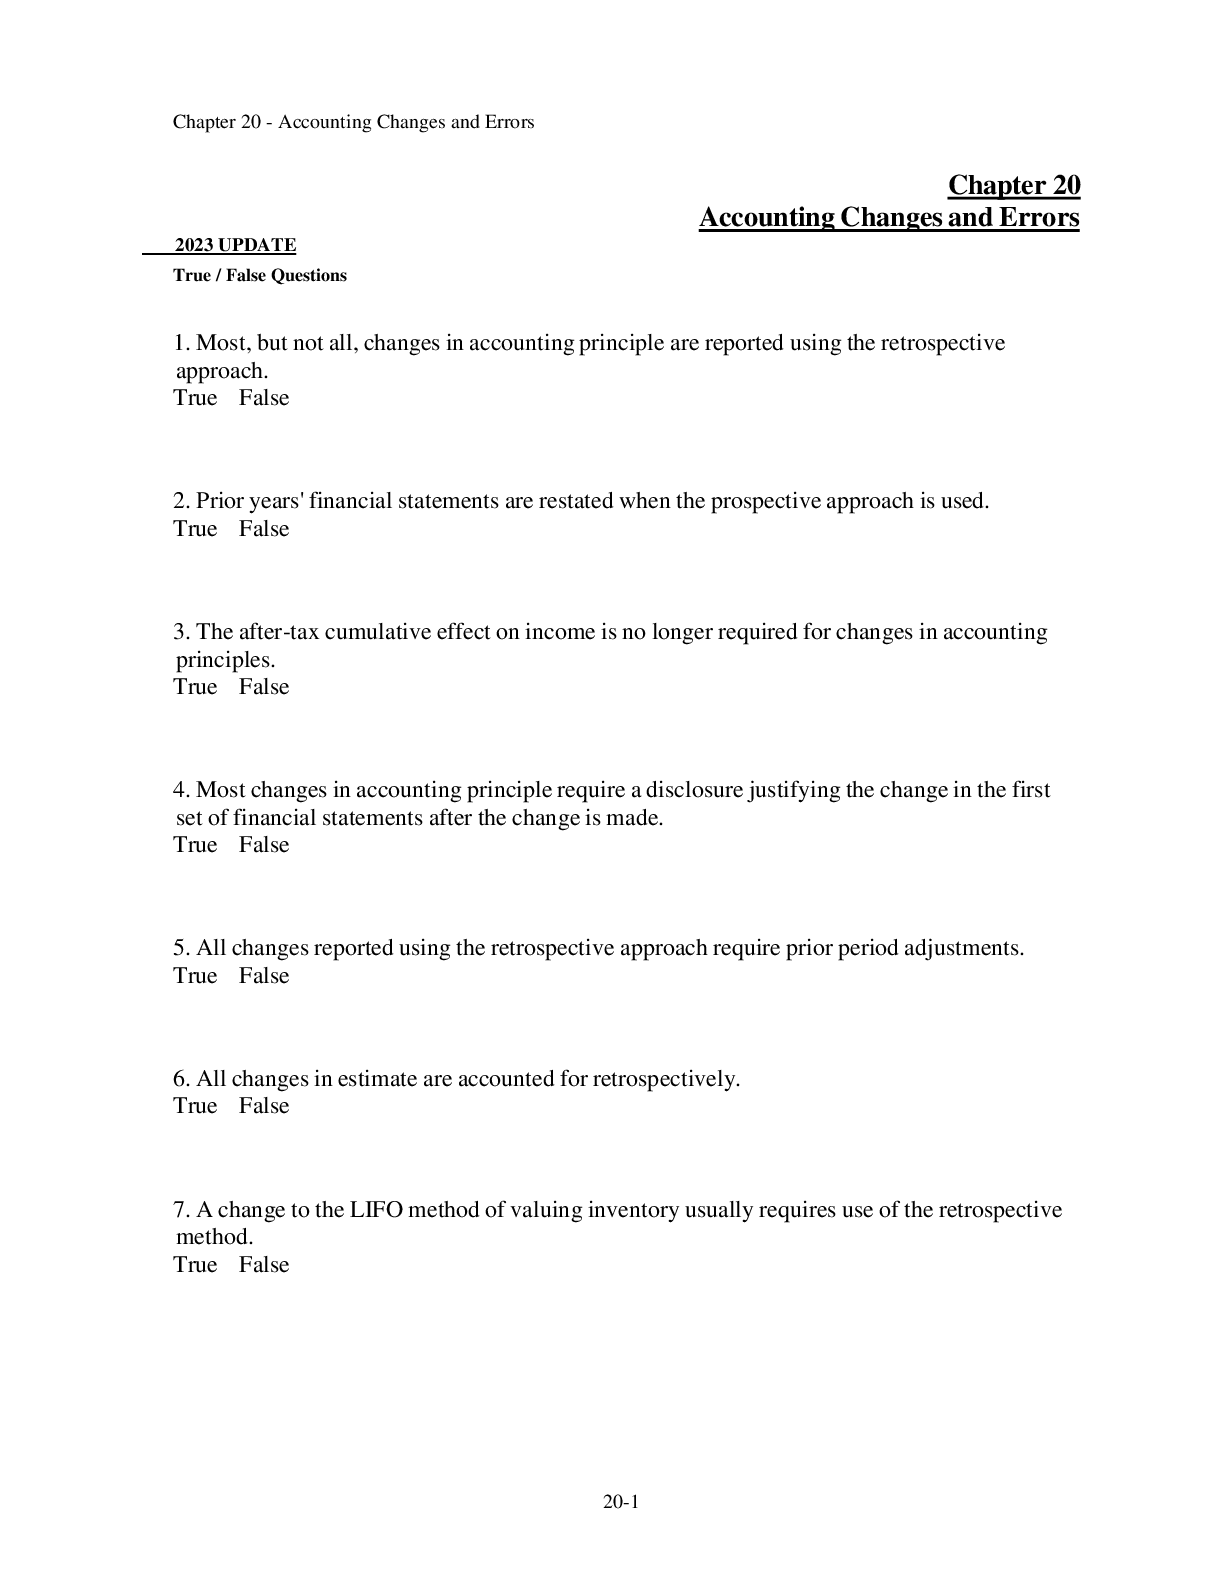
Test Bank-2020-Financial Accounting-Meaning.Nature & Role-Chapter 20- Accounting Changes and Errors
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 108 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Jun 03, 2021
Number of pages
108
Written in
All

Additional information
This document has been written for:
Uploaded
Jun 03, 2021
Downloads
0
Views
90
Topic Tags
Recommended For You
Get more on TEST BANKS »
Test Bank-2020-Financial Accounting-Meaning.Nature & Role-Chap...

Test Bank-2020-Chapter 20- Accounting Changes and Errors
TEST BANK Chapter 20: Heart and Neck Vessels PHYSICAL EXAMINAT...

Chapter 8- Cancers of the Female Reproductive Tract: Test Bank...
.png)
Burns and Grove's The Practice of Nursing Research: Appraisal,...
 (1).png)
Test Bank Chapter 20- Heart Failure and Circulatory Shock
Chapter 20: NURS 340 Preparation For The Nclex Questions and A...

.png)
Chapter 20: The Older Adult ; Bates’ Guide to Physical Examina...
.png)
Chapter 20: Peripheral Vascular System and Lymphatic System Ja...
NR 331 Exam 5 Chapter 20-22, 33 Questions and Answers (Verif...
BIOS 260 Chapter 20 Questions and Answers (Verified Answers)

BIOS 254 Chapter 20-21 Exam Questions and Answers (Verified...
CRCST Certification / Score 100% / Chapter 20 Quiz / 2025 Stud...
NURS 6501 / NURS6501: Advanced Pathophysiology - Chapter 20 St...

Pharmacology Exam 4 Review: Chapter 20 Anxiolytics and Hypnoti...