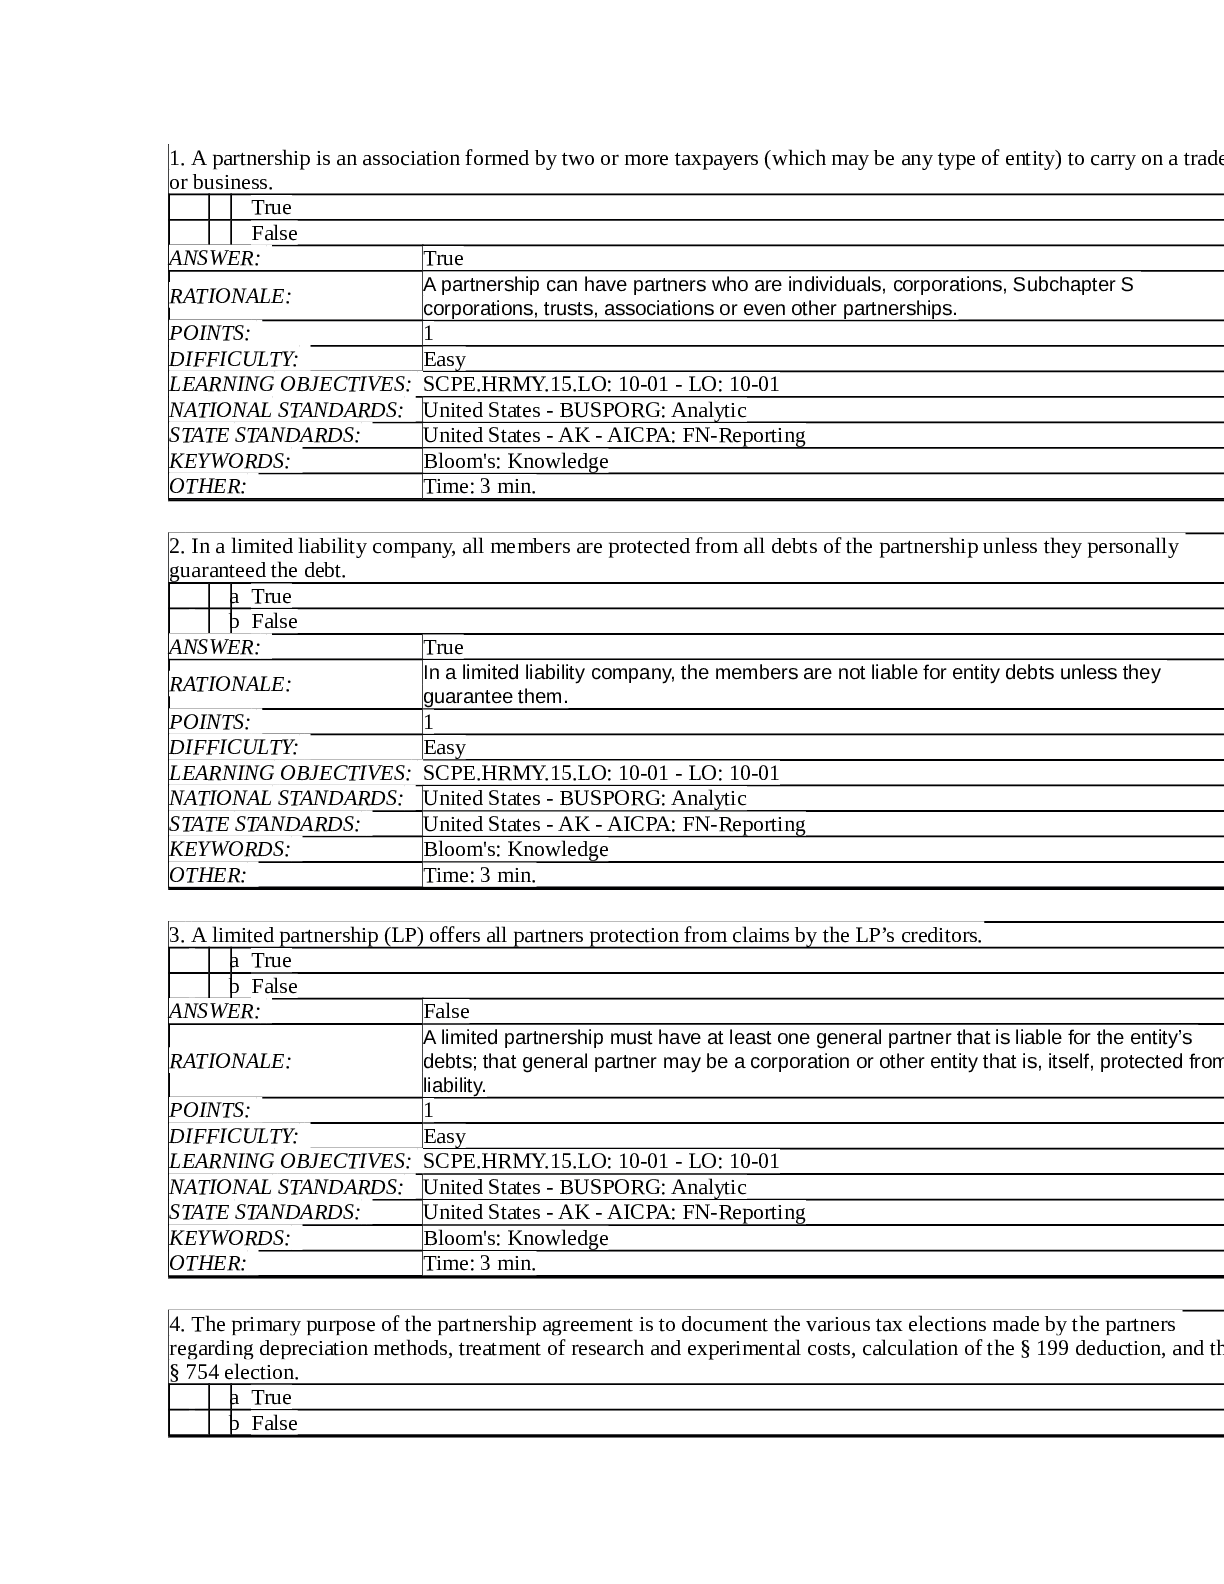
1. A partnership is an association formed by two or more taxpayers (which may be any type of entity) to carry on a trade
or business.
True
False
ANSWER: True
RATIONALE: A partnership can have partners who are indivi
...
1. A partnership is an association formed by two or more taxpayers (which may be any type of entity) to carry on a trade
or business.
True
False
ANSWER: True
RATIONALE: A partnership can have partners who are individuals, corporations, Subchapter S
corporations, trusts, associations or even other partnerships.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-01 - LO: 10-01
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
2. In a limited liability company, all members are protected from all debts of the partnership unless they personally
guaranteed the debt.
a True
b False
ANSWER: True
RATIONALE: In a limited liability company, the members are not liable for entity debts unless they
guarantee them.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-01 - LO: 10-01
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
3. A limited partnership (LP) offers all partners protection from claims by the LP’s creditors.
a True
b False
ANSWER: False
RATIONALE:
A limited partnership must have at least one general partner that is liable for the entity’s
debts; that general partner may be a corporation or other entity that is, itself, protected from
liability.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-01 - LO: 10-01
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
4. The primary purpose of the partnership agreement is to document the various tax elections made by the partners
regarding depreciation methods, treatment of research and experimental costs, calculation of the § 199 deduction, and th
§ 754 election.
a True
b FalseANSWER: False
RATIONALE:
The partnership agreement documents the arrangement among the partners regarding
formation, operation, and liquidation of the partnership; allocations of profits, losses, and
distributions; and other matters. The elections described are not typically covered in the
partnership agreement, and such elections are made by the partnership rather than the
partners.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-01 - LO: 10-01
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
5. The taxable income of a partnership flows through to the partners, who report the income on their tax returns.
a True
b False
ANSWER: True
RATIONALE: The partners, not the partnership, pay tax on partnership income.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-02 - LO: 10-02
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
6. An example of the “aggregate concept” underlying partnership taxation is the fact that the partners (rather than the
partnership) pay tax on partnership income.
a True
b False
ANSWER: True
RATIONALE: This is an example of the aggregate (or “conduit”) principle of taxation.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-02 - LO: 10-02
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Comprehension
OTHER: Time: 3 min.
7. A partner will have the same profit-sharing, loss-sharing, and capital-sharing ownership percentages.
a True
b False
ANSWER: False
RATIONALE:
Each partner’s profit-sharing, loss-sharing, and capital-sharing ratios are reported on that
partner’s Schedule K-1. In many cases, the three ratios are the same. However, if the
partnership agreement provides for special allocations or if capital contributions or
distributions differed at some point from the profit- or loss-sharing percent, these ratios may
differ for a given partner.POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-02 - LO: 10-02
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
8. The “inside basis” is defined as a partner’s basis in the partnership interest.
a True
b False
ANSWER: False
RATIONALE: The “outside basis” is defined as a partner’s basis in the partnership
interest.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-02 - LO: 10-02
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
9. The partnership reports each partner’s share of income to the partner on a Form 1099-MISC.
a True
b False
ANSWER: False
RATIONALE: The partners will receive a Schedule K-1 from the partnership that includes the partner’s
share of ordinary partnership income and each separately stated item.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-02 - LO: 10-02
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: Knowledge
OTHER: Time: 3 min.
10. Section 721 provides that, in general, no gain or loss is recognized by the partnership or the partner on contribution o
appreciated or depreciated property to a partnership in exchange for an interest in the partnership.
a True
b False
ANSWER: True
RATIONALE: Section 721 provides for nonrecognition of either gain or loss on a contribution of property t
the partnership.
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-03 - LO: 10-03
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Reporting
KEYWORDS: Bloom's: KnowledgeOTHER: Time: 3 min.
11. Ken and Lars formed the equal KL Partnership during the current year, with Ken contributing $100,000 in cash and
Lars contributing land (basis of $60,000, fair market value of $40,000) and equipment (basis of $0, fair market value of
$60,000). Lars recognizes a $40,000 gain on the contribution and his basis in his partnership interest is $100,000.
a True
b False
ANSWER: False
RATIONALE:
Under § 721, neither the partnership nor a partner will generally recognize gain or loss on
contribution of property to a partnership. Lar’s basis in his partnership interest is the $60,00
basis in the assets contributed ($60,000 basis in land plus $0 basis in equipment).
POINTS: 1
DIFFICULTY: Easy
LEARNING OBJECTIVES: SCPE.HRMY.15.LO: 10-03 - LO: 10-03
SCPE.HRMY.15.LO: 10-09 - LO: 10-09
NATIONAL STANDARDS: United States - BUSPORG: Analytic
STATE STANDARDS: United States - AK - AICPA: FN-Measurement
[Show More]









.png)

.png)


