Financial Accounting > CASE STUDY > ACCT 601 Week 2 Individual Assignment: Current Issues Paper (GRADED) (All)
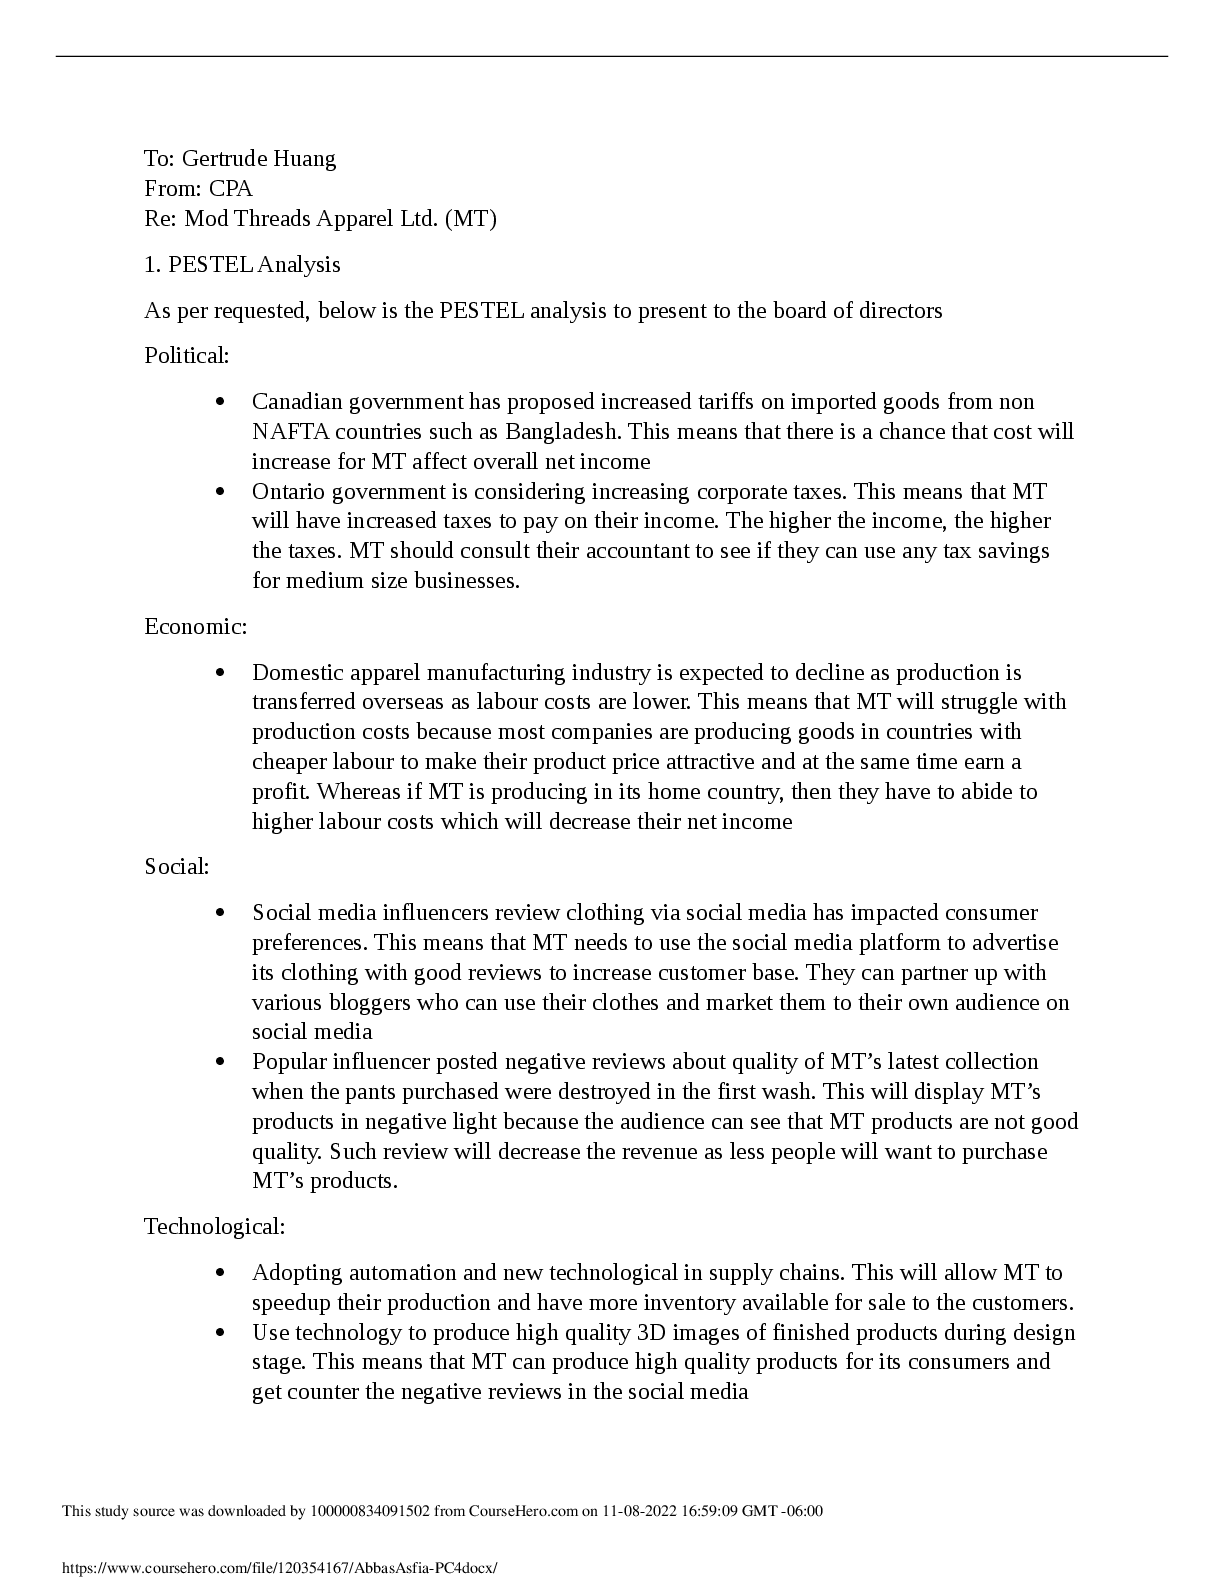
ACCT 601 Week 2 Individual Assignment: Current Issues Paper (GRADED)
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 4 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Also available in bundle (1)
Click Below to Access Bundle(s)
ACCT 601 Coursework Week 1 – 8 BUNDLE (100% Correct Solutions) | Download To Score An A
ACCT 601 Week 1 Individual Assignment: Communication Skills & Report Writing ACCT-601 Week 1 Term Paper: Proposed Topic and Problem Statement ACCT 601 Week 2 Individual Assignment: Current Issues...
By EliteStudyDocs 4 years ago
$14.5
9
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Apr 09, 2022
Number of pages
4
Written in
All

Additional information
This document has been written for:
Uploaded
Apr 09, 2022
Downloads
0
Views
176
Topic Tags
Recommended For You
Get more on CASE STUDY »
ACCT-601 Week 2 Written Assignment: IFRS Updates (Already GRAD...
ACCT 601 Week 1 Written Assignment: Important aspects of commu...
ACCT 601 Week 3 Assignment: You-decide – Ethical Issue (graded...
.png)
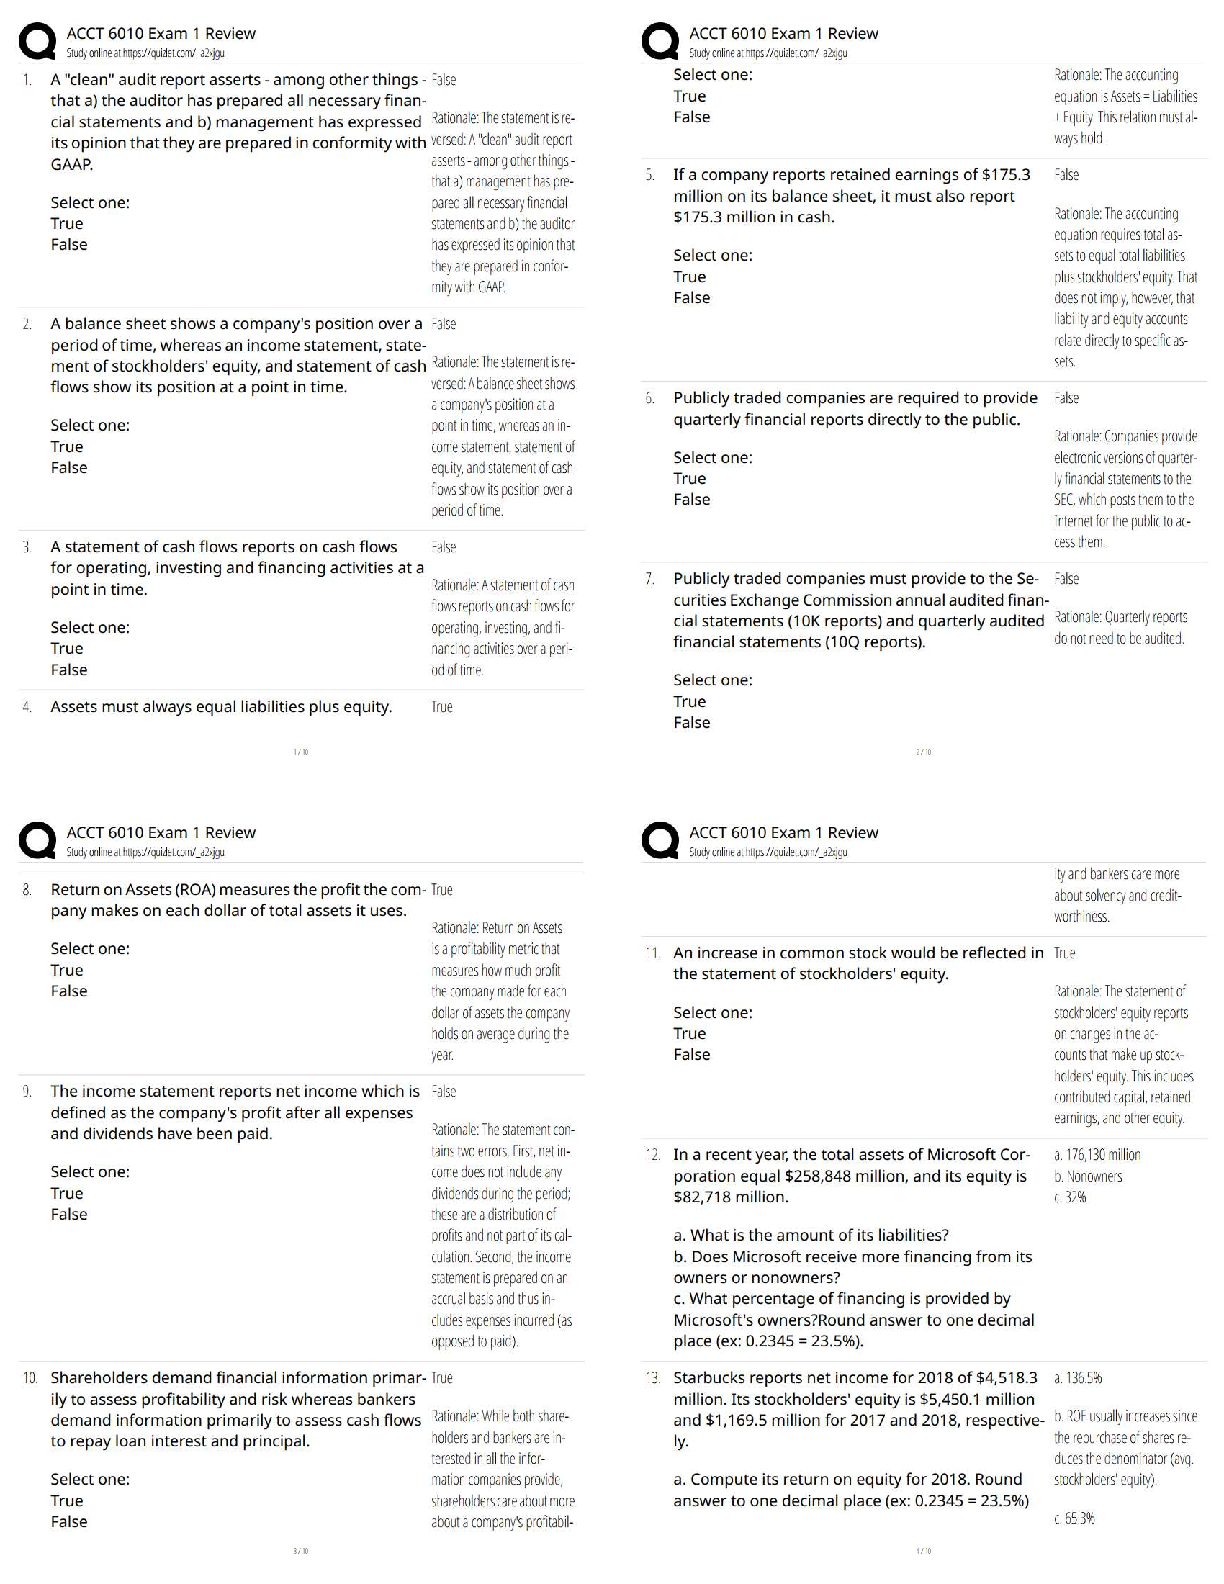
ACCT 601 MIDTERM I REVIEW ANSWERS. Contains 60 Questions and A...

Financial Accounting with International Financial Reporting St...

Solutions Manual for Advanced Accounting, 8th Edition by Debra...

Advanced Accounting 4th Edition By Hamlen, Huefner, Largay (Te...