Econ 201 WVU Final Exam 64 Questions with Correct
Answers
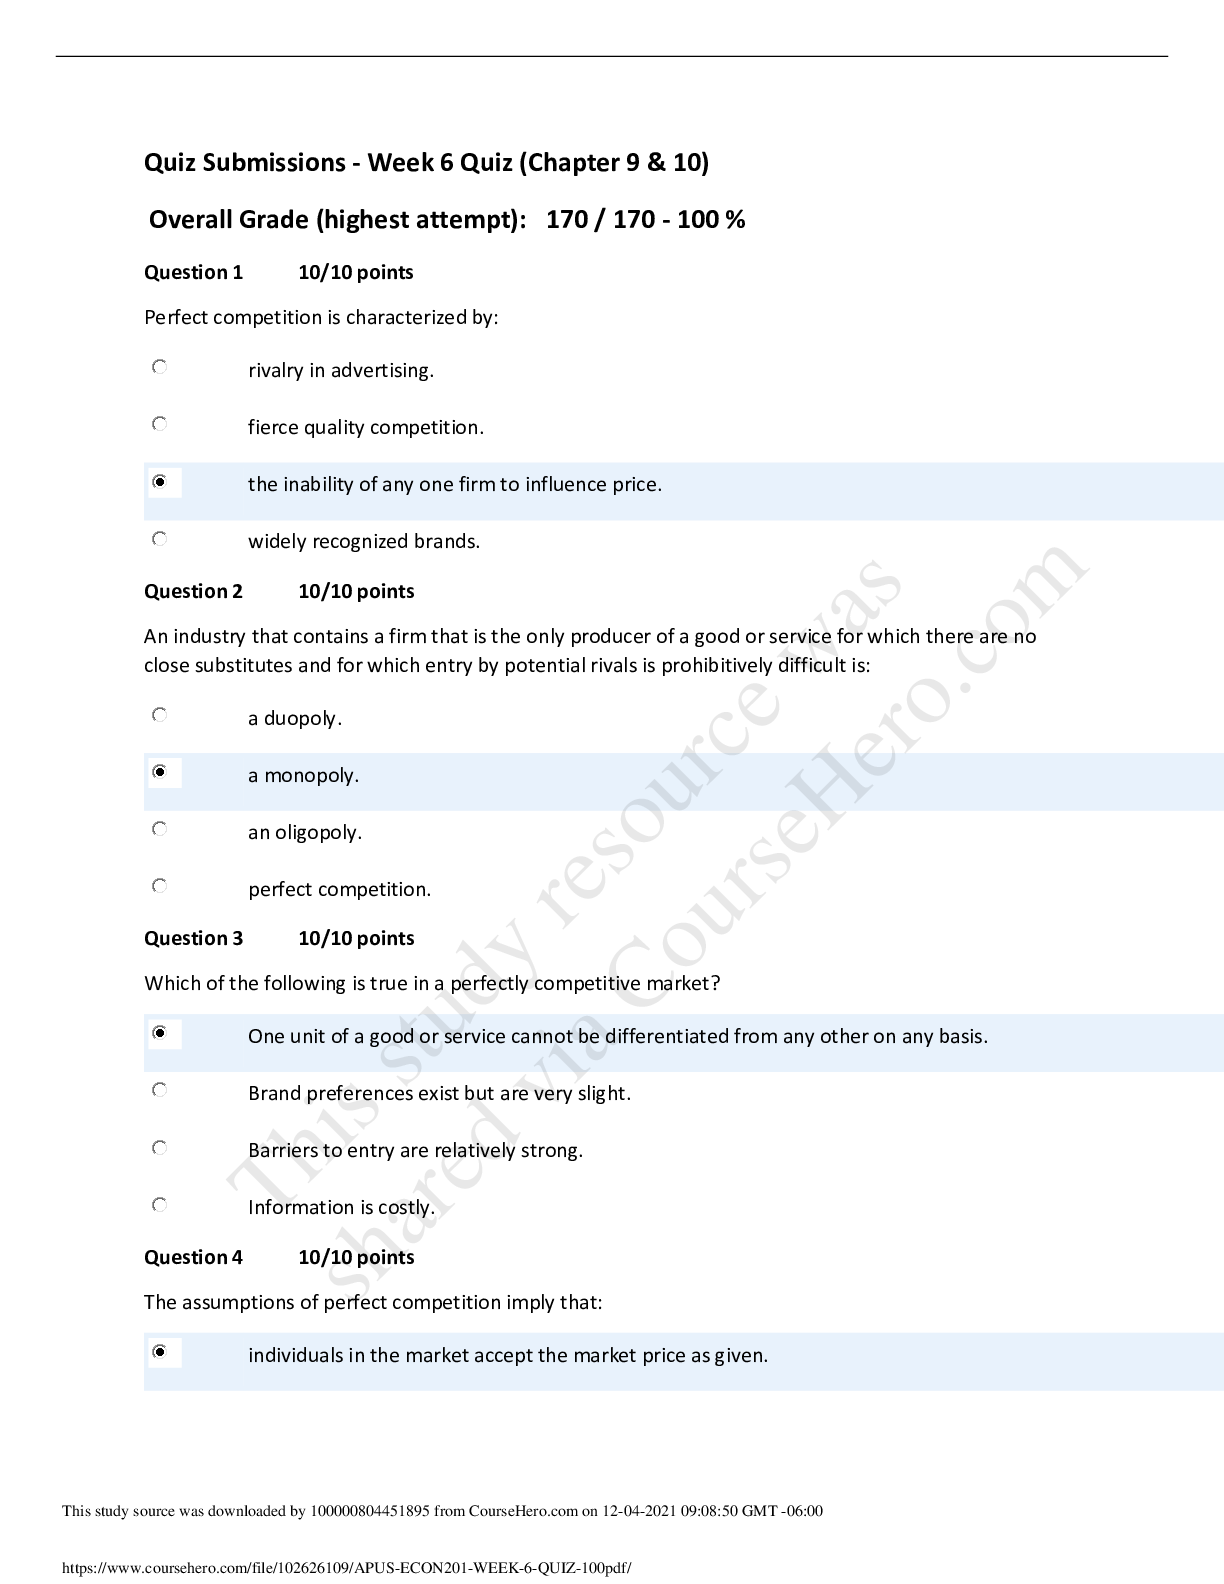
In a competitive market, no single producer can influence the market price because
a. many other sellers are offering a product that is essentially identical.
...
Econ 201 WVU Final Exam 64 Questions with Correct
Answers
In a competitive market, no single producer can influence the market price because
a. many other sellers are offering a product that is essentially identical.
b. consumers have more influence over the market price than producers do.
c. government intervention prevents firms from influencing price.
d. producers agree not to change the price. >>>a. many other sellers are offering a
product that is essentially identical.
3. The short-run supply curve for a firm in a perfectly competitive market is
a. likely to be horizontal.
b. likely to slope downward.
c. determined by forces external to the firm.
d. its marginal cost curve (above average variable cost) >>>d. its marginal cost curve
(above average variable cost)
A price-taking firm produces rubber balls. When the price of rubber balls is below the
firm's minimum
average total cost, but above the firm's minimum average variable cost, the firm
a. will experience losses but it will continue to produce rubber balls in the short run.
b. will shut down in the short run.
c. will be earning both economic and accounting profits.
d. should raise the price of its product. >>>d. should raise the price of its product.
7. The irrelevance of sunk costs is best described by which of the following business
decisions?
a. New airlines enter the market and earn accounting profits.
b. Airlines continue to sell tickets even though they are reporting large losses.
c. Airlines exit the market when they report losses.
d. All of the above are correct. >>>b. Airlines continue to sell tickets even though they
are reporting large losses.
One of the most important determinants of the success of free-market capitalism is
a. enlightened governments selecting firms that should not be allowed to exit a market.
b. free entry and exit in markets.
c. government regulation of market participants.
d. having a few large firms rather than thousands of small ones. >>>b. free entry and
exit in markets.
When new firms have an incentive to enter a competitive market, their entry will
a. increase the price of the product.
b. drive down profits of existing firms in the market.
c. shift the market supply curve to the left.d. All of the above are correct >>>b. drive down profits of existing firms in the market.
Which of the following is an implicit cost of owning a business?
(i) interest expense on existing business loans
(ii) forgone savings account interest when personal money is invested in the business
(iii) damaged or lost inventory
a. (i) only
b. (ii) only
c. (i) and (ii)
d. All of the above are correct. >>>b. (ii) only
Economists normally assume that the goal of a firm is to
a. maximize its total revenue. b. maximize its profit.
b. maximize its profit.
c. minimize its explicit costs.
d. minimize its total cost. >>>b. maximize its profit.
The marginal product of labor can be defined as
a. change in profit/change in labor.
b. change in output/change in labor.
c. change in labor/change in output.
d. change in labor/change in total cost. >>>b. change in output/change in labor.
Which of these assumptions is often realistic for a firm in the short run?
a. The firm can vary both the size of its factory and the number of workers it employs.
b. The firm can vary the size of its factory, but not the number of workers it employs.
c. The firm can vary the number of workers it employs, but not the size of its factory.
d. The firm can vary neither the size of its factory nor the number of workers it employs.
>>>c. The firm can vary the number of workers it employs, but not the size of its factory.
[Show More]