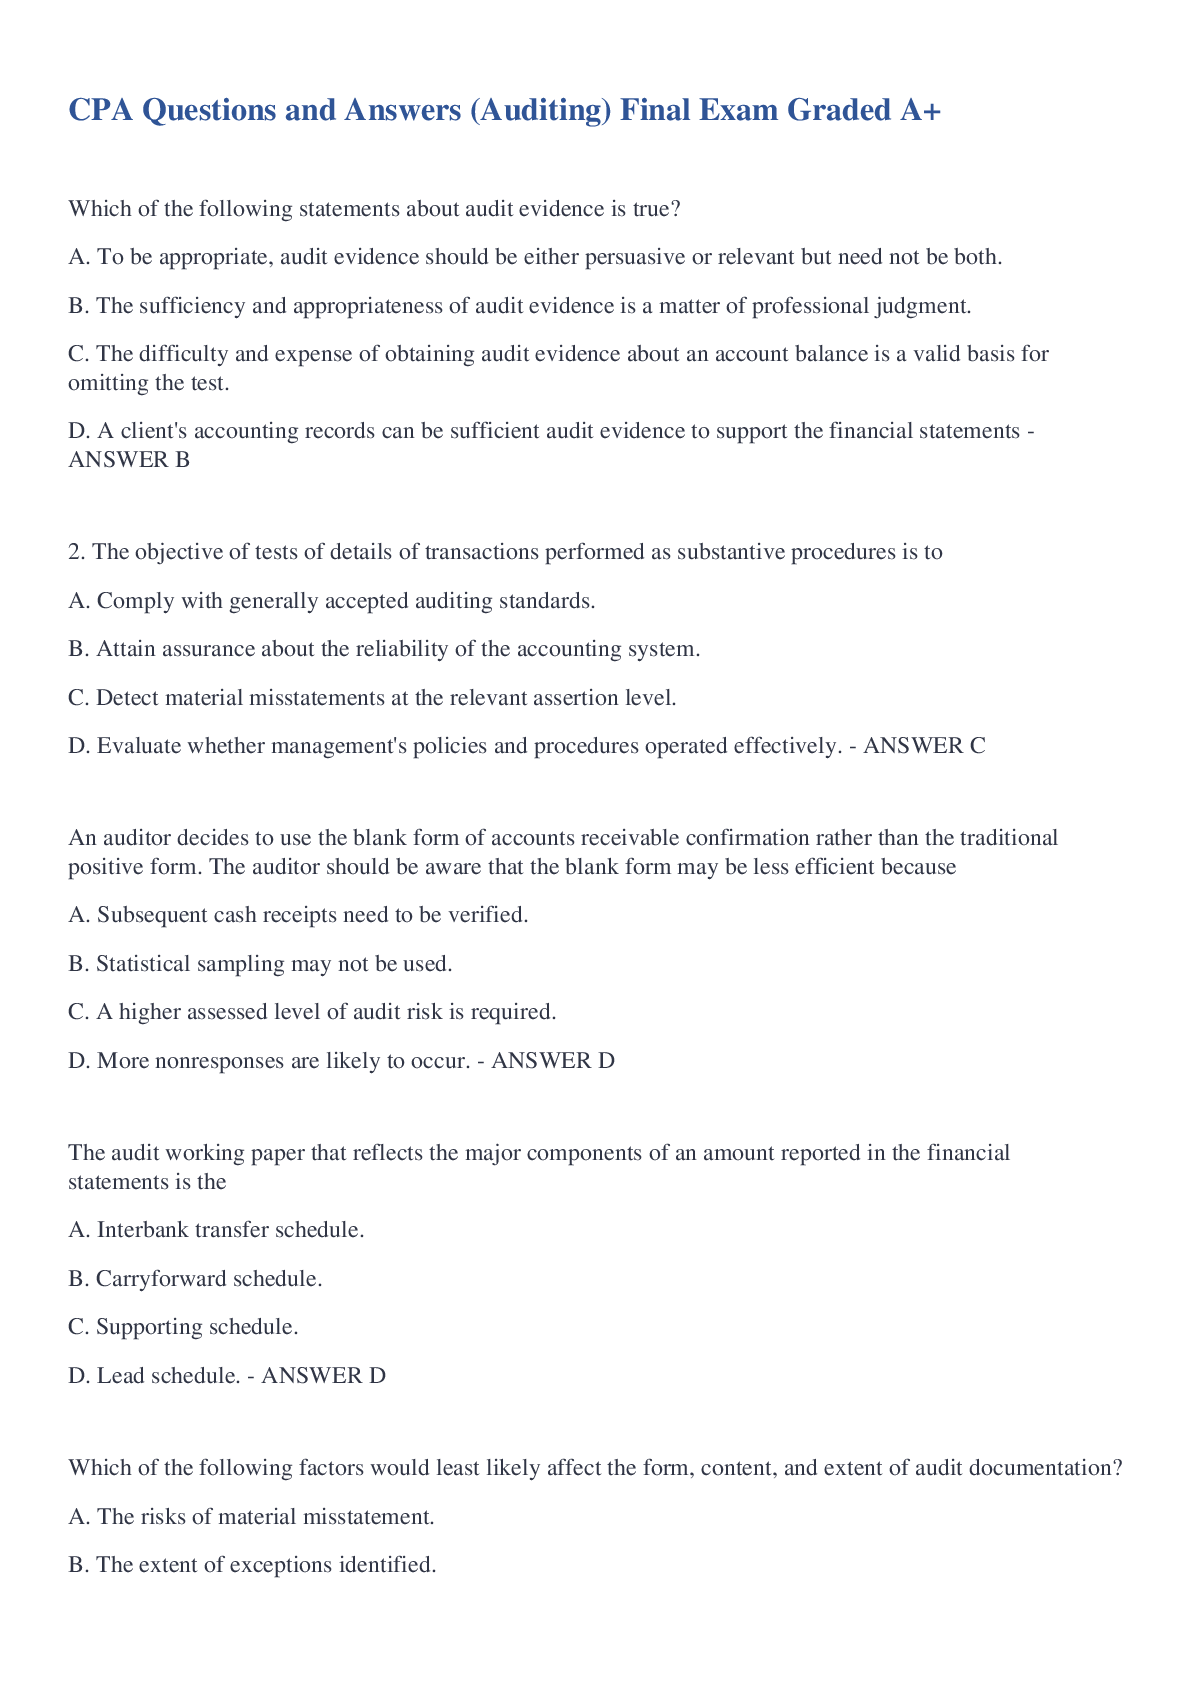
Which of the following statements about audit evidence is true?
A. To be appropriate, audit evidence should be either persuasive or relevant but need not be both.
B. The sufficiency and appropriateness of audit evidenc
...
Which of the following statements about audit evidence is true?
A. To be appropriate, audit evidence should be either persuasive or relevant but need not be both.
B. The sufficiency and appropriateness of audit evidence is a matter of professional judgment.
C. The difficulty and expense of obtaining audit evidence about an account balance is a valid basis for omitting the test.
D. A client's accounting records can be sufficient audit evidence to support the financial statements - ANSWER B
2. The objective of tests of details of transactions performed as substantive procedures is to
A. Comply with generally accepted auditing standards.
B. Attain assurance about the reliability of the accounting system.
C. Detect material misstatements at the relevant assertion level.
D. Evaluate whether management's policies and procedures operated effectively. - ANSWER C
An auditor decides to use the blank form of accounts receivable confirmation rather than the traditional positive form. The auditor should be aware that the blank form may be less efficient because
A. Subsequent cash receipts need to be verified.
B. Statistical sampling may not be used.
C. A higher assessed level of audit risk is required.
D. More nonresponses are likely to occur. - ANSWER D
The audit working paper that reflects the major components of an amount reported in the financial statements is the
A. Interbank transfer schedule.
B. Carryforward schedule.
C. Supporting schedule.
D. Lead schedule. - ANSWER D
Which of the following factors would least likely affect the form, content, and extent of audit documentation?
A. The risks of material misstatement.
B. The extent of exceptions identified.
C. The nature of the auditing procedures.
D. The medium in which it is recorded and maintained. - ANSWER D
Which of the following statements concerning audit documentation is false?
A. An auditor may support an opinion by other means in addition to audit documentation.
B. The form of audit documentation should be designed to meet the circumstances of a particular engagement.
C. Audit documentation is the property of the client.
D. Audit documentation should show that the auditor has obtained an understanding of internal control. - ANSWER C
Although the quantity and content of audit documentation vary with each engagement, an auditor's permanent files most likely include
A. Schedules that support the current year's adjusting entries.
B. Prior year's accounts receivable confirmations that were classified as exceptions.
C. Documentation indicating that the audit work was adequately planned and supervised.
D. Analyses of capital stock and other owners' equity accounts. - ANSWER D
Which of the following statements is correct concerning the use of negative confirmation requests?
A. Unreturned negative confirmation requests rarely provide significant explicit evidence.
B. Negative confirmation requests are effective when audit risk is low.
C. Unreturned negative confirmation requests indicate that alternative procedures are necessary.
D. Negative confirmation requests are effective when understatements of account balances are suspected. - ANSWER A
Which statement about audit evidence is false?
A. The auditor is seldom convinced beyond all doubt with respect to all aspects of the statements being audited.
B. The auditor should not perform a procedure that provides persuasive evidence rather than conclusive evidence.
C. The auditor evaluates the degree of risk involved in deciding the kind of evidence to gather.
D. The auditor balances the benefits of the evidence and the cost to obtain it. - ANSWER B
Audit evidence can come in different forms with different degrees of persuasiveness. Which of the following is the least persuasive type of evidence?
A. Bank statement obtained from the client.
B. Test counts of inventory made by the auditor.
C. Prenumbered purchase order forms.
D. Correspondence from the client's attorney about litigation. - ANSWER C
Which of the following checks might indicate kiting?
A. #101 and #303.
B. #202 and #404.
C. #101 and #404.
D. #202 and #303. - ANSWER B
Which of the following checks illustrate deposits or transfers in transit at December 31, Year 1?
A. #101 and #202.
B. #101 and #303.
C. #202 and #404.
D. #303 and #404. - ANSWER B
Which of the following sets of information does an auditor usually confirm on one form?
A. Accounts payable and purchase commitments.
B. Cash in bank and collateral for loans.
C. Inventory on consignment and contingent liabilities.
D. Accounts receivable and accrued interest receivable. - ANSWER B
An auditor ordinarily sends a standard confirmation request to all banks with the client has done business during the year under audit, regardless of the year-end balance. A purpose of this procedure is to
A. Provide the data necessary to prepare a proof of cash.
B. Request that a cutoff bank statement and related checks be sent to the auditor.
C. Detect kiting activities that may otherwise not be discovered.
D. Seek information about other deposit and loan amounts that come to the attention of the institution in the process of completing the confirmation. - ANSWER D
An auditor most likely would limit substantive audit tests of sales transactions when the risks of material misstatement are assessed as low for the existence and occurrence assertions concerning sales transactions
and the auditor has already gathered evidence supporting
A. Opening and closing inventory balances.
B. Cash receipts and accounts receivable.
C. Shipping and receiving activities.
D. Cutoffs of sales and purchases. - ANSWER B
An auditor most likely would review an entity's periodic accounting for the numerical sequence of shipping documents and invoices to support management's financial statement assertion of
A. Occurrence.
B. Rights and obligations.
C. Valuation and allocation.
D. Completeness. - ANSWER D
Which of the following might be detected by an auditor's review of the client's sales cutoff?
A. Excessive goods returned for credit.
B. Unrecorded sales discounts.
C. Lapping of year-end accounts receivable.
D. Inflated sales for the year. - ANSWER D
Which of the following most likely would give the most assurance concerning the valuation assertion about accounts receivable?
A. Vouching amounts in the subsidiary ledger to details on shipping documents.
B. Comparing receivable turnover ratios with industry statistics for reasonableness.
C. Inquiring about receivables pledged under loan agreements.
D. Assessing the allowance for uncollectible accounts for reasonableness. - ANSWER D
AU-C 505, External Confirmations, defines external confirmation as "a direct written response to the auditor from a third party (the confirming party), either in paper form or by electronic or other medium."
The assertions for which confirmation of accounts receivable balances provides primary evidence are
A. Completeness and valuation.
B. Valuation and rights and obligations.
C. Rights and obligations and existence.
D. Existence and completeness. - ANSWER C
Which of the following procedures would an auditor most likely perform for year-end accounts receivable confirmations when the auditor did not receive replies to second requests?
A. Review the cash receipts journal for the month prior to year end.
B. Intensify the study of internal control concerning the revenue cycle.
C. Increase the assessed level of detection risk for the existence assertion.
D. Inspect the shipping records documenting the merchandise sold to the debtors. - ANSWER D
The primary source of information to be reported about litigation, claims, and assessments is the
A. Client's legal counsel.
B. Court records.
C. Client's management.
D. Independent auditor - ANSWER A
To provide assurance that each voucher is submitted and paid only once, an auditor most likely would examine a sample of paid vouchers and determine whether each voucher is
A. Supported by a vendor's invoice.
B. Stamped "paid" by the check signer.
C. Prenumbered and accounted for.
D. Approved for authorized purchases. - ANSWER B
Which of the following accounts most likely would assist in reducing the risks of material misstatement related to the existence or occurrence of manufacturing transactions?
A. Perpetual inventory records are independently compared with goods on hand.
B. Forms used for direct materials requisitions are prenumbered and accounted for.
C. Finished goods are stored in locked limited-access warehouses.
D. Subsidiary ledgers are periodically reconciled with inventory control accounts. - ANSWER A
Which of the following situations most likely could lead to an embezzlement scheme?
A. The accounts receivable bookkeeper receives a list of payments prepared by the cashier and personally makes entries in the customers' accounts receivable subsidiary ledger.
B. Each vendor invoice is matched with the related purchase order and receiving report by the vouchers payable clerk who personally approves the voucher for payment.
C. Access to blank checks and signature plates is restricted to the cash disbursements bookkeeper who personally reconciles the monthly bank statement.
D. Vouchers and supporting documentation are examined and then cancelled by the CFO who personally mails the checks to vendors - ANSWER C
The authority to accept incoming goods in receiving should be based on a(n)
A. Vendor's invoice.
B. Materials requisition.
C. Bill of lading.
D. Approved purchase order - ANSWER D
To determine whether accounts payable are complete, an auditor performs a test to verify that all merchandise received is recorded. The population of documents for this test consists of all
A. Payment vouchers.
B. Receiving reports.
C. Purchase requisitions.
D. Vendors' invoices. - ANSWER B
Which of the following is a substantive procedure that an auditor most likely would perform to verify the existence and valuation assertions about recorded accounts payable?
A. Investigating the open purchase order file to ascertain that prenumbered purchase orders are used and accounted for.
B. Receiving the client's mail, unopened, for a reasonable period of time after year end to search for unrecorded vendor's invoices.
C. Vouching selected entries in the accounts payable subsidiary ledger to purchase orders and receiving reports.
D. Confirming accounts payable balances with known suppliers who have zero balances. - ANSWER C
Which of the following procedures would an auditor most likely perform in searching for unrecorded liabilities?
A. Trace a sample of accounts payable entries recorded just before year end to the unmatched receiving report file.
B. Compare a sample of purchase orders issued just after year end with the year-end accounts payable trial balance.
C. Vouch a sample of cash disbursements recorded just after year end to receiving reports and vendor invoices.
D. Scan the cash disbursements entries recorded just before year end for indications of unusual transactions. - ANSWER C
When performing procedures to test assertions about purchases, an auditor vouches a sample of entries in the voucher register to the supporting documents. Which relevant assertion would this procedure most
likely support?
A. Completeness.
B. Occurrence.
C. Valuation and allocation.
D. Classification. - ANSWER B
Which of the following auditing procedures most likely would provide assurance regarding a manufacturing entity's relevant assertions about inventory valuation?
A. Testing the entity's computation of standard overhead rates.
B. Obtaining confirmation of inventories pledged under loan agreements.
C. Reviewing shipping and receiving cutoff procedures for inventories.
D. Tracing test counts to the entity's inventory listing. - ANSWER A
While observing a client's annual physical inventory, an auditor recorded test counts for several items and noticed that certain test counts were higher than the recorded quantities in the client's perpetual records.
This situation could be the result of the client's failure to record
A. Purchase discounts.
B. Purchase returns.
C. Sales.
D. Sales returns. - ANSWER D
Which of the following combinations of procedures would an auditor most likely perform to obtain evidence about fixed asset additions?
A. Inspecting documents and physically examining assets.
B. Recomputing calculations and obtaining written management representations.
C. Observing operating activities and comparing balances with priorperiod balances.
D. Confirming ownership and corroborating transactions through inquiries of client personnel. - ANSWER A
In auditing intangible assets, an auditor most likely would review or recomputed amortization and determine whether the amortization period is
reasonable in support of the relevant financial statement assertion of
A. Valuation and allocation.
B. Existence.
C. Completeness.
D. Rights and obligations. - ANSWER A
Which of the following explanations most likely would satisfy an auditor who questions management about significant debts to accumulated depreciation accounts in the current year?
A. Prior years' depreciation expenses were erroneously understated.
B. Current year's depreciation expense was erroneously understated.
C. The estimated remaining useful lives of plant assets were revised upward.
D. Plant assets were retired during the current year - ANSWER D
During an audit of a company's equity accounts, the auditor determines whether restrictions have been imposed on retained earnings resulting from loans, agreements, or state law. This audit procedure most
likely is intended to verify relevant assertion about
A. Existence and occurrence.
B. Completeness.
C. Valuation and allocation.
D. Classification and understandability. - ANSWER D
An auditor usually obtains evidence of a company's equity transactions by reviewing its
A. Minutes of board of directors meetings.
B. Transfer agent's records.
C. Cancelled stock certificates.
D. Treasury stock certificate book - ANSWER A
When a client's company does not maintain its own stock records, the auditor should obtain written confirmation from the transfer agent and
registrar concerning
A. Restrictions on the payment of dividends.
B. The number of shares issued and outstanding.
C. Guarantees of preferred stock liquidation value.
D. The number of shares subject to agreements to repurchase. - ANSWER B
A weakness in internal control over recording retirements of equipment may cause an auditor to
A. Inspect certain items of equipment in the plant and trace those items to the accounting records.
B. Review the subsidiary ledger to ascertain whether depreciation was taken on each item of equipment during the year.
C. Trace additions to the "other assets" account to search for equipment that is still on hand but no longer being used.
[Show More]


, 5e Jerry Weygandt, Paul Kimmel (Test Bank).png)