AP/ADMS 4504 M&N Fixed Income Securities and Risk Management
Document Content and Description Below
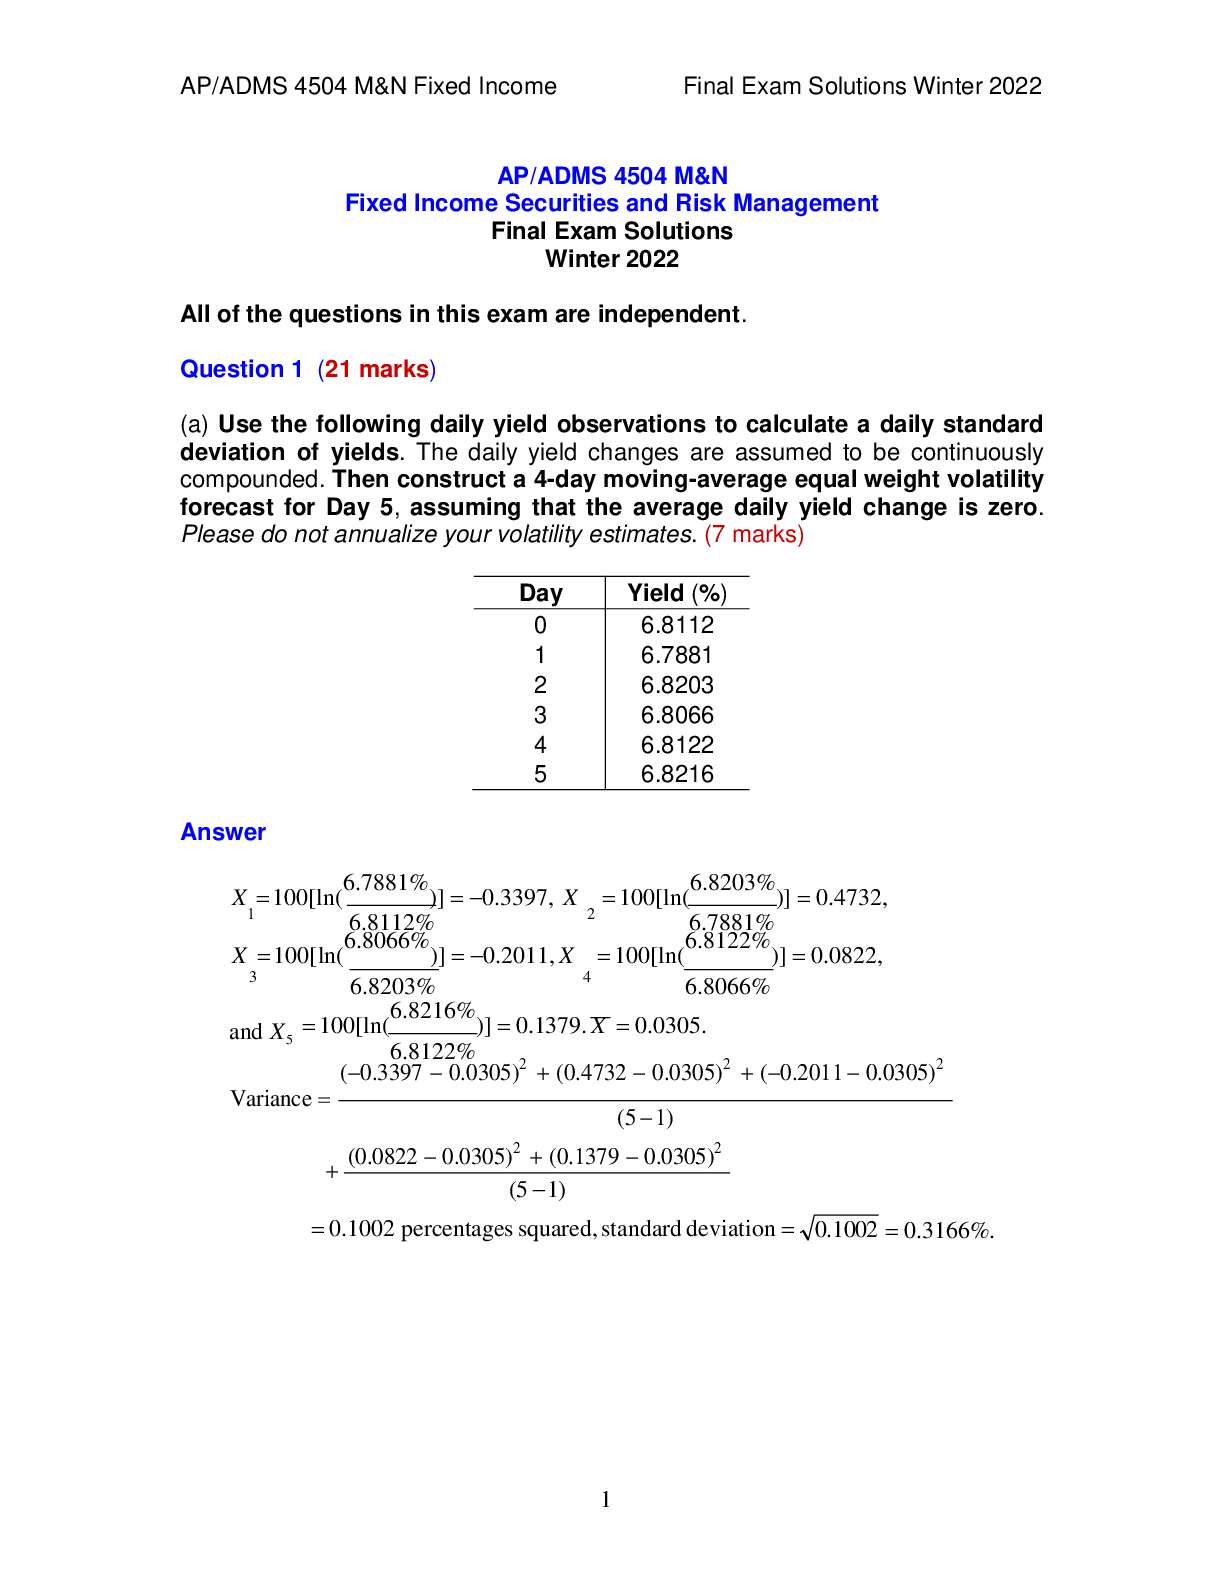
AP/ADMS 4504 M&N
Fixed Income Securities and Risk Management Final Exam Solutions
Winter 2022
All of the questions in this exam are independent. Question 1 (21 marks)
(a) Use the following daily yield observations
...
[Show More]
Last updated: 3 years ago
Preview 1 out of 12 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Feb 07, 2023
Number of pages
12
Written in
All

Additional information
This document has been written for:
Uploaded
Feb 07, 2023
Downloads
0
Views
80
Topic Tags
Recommended For You
Get more on EXAM »
$20
65 Pages
Solution Manual for Fixed Income Securities Valuation, Risk An...

$26
345 Pages
eBook [PDF] Barash, Cullen, and Stoelting's Clinical Anesthesi...

$29
1067 Pages
eBook [PDF] Burns' Pediatric Primary Care 7th Edition BY Dawn...

$16
137 Pages
Test Bank for Burns' Pediatric Primary Care 7th Edition by Daw...
$15
135 Pages
Burns Pediatric Primary Care 7th Edition All Chapters Complete...
$26
209 Pages
Burns' Pediatric Primary Care, 7th Edition by Garzon, Barber S...
$15
835 Pages
Complete Test Bank Emergency Care 14th Edition Daniel Limmer Q...
$16
835 Pages
Test Bank Emergency Care 14th Edition Daniel Limmer Questions...

$29
424 Pages
eBook [PDF] AACN Essentials of Progressive Care Nursing 5th Ed...
$25
591 Pages
AACN Essentials of Progressive Care Nursing 5th Edition By S...

$24
65 Pages
Fixed Income Securities Valuation, Risk And Risk Management 1s...
More related documents below