Mgmt 200 Final Exam 2022 -Purdue University
Document Content and Description Below
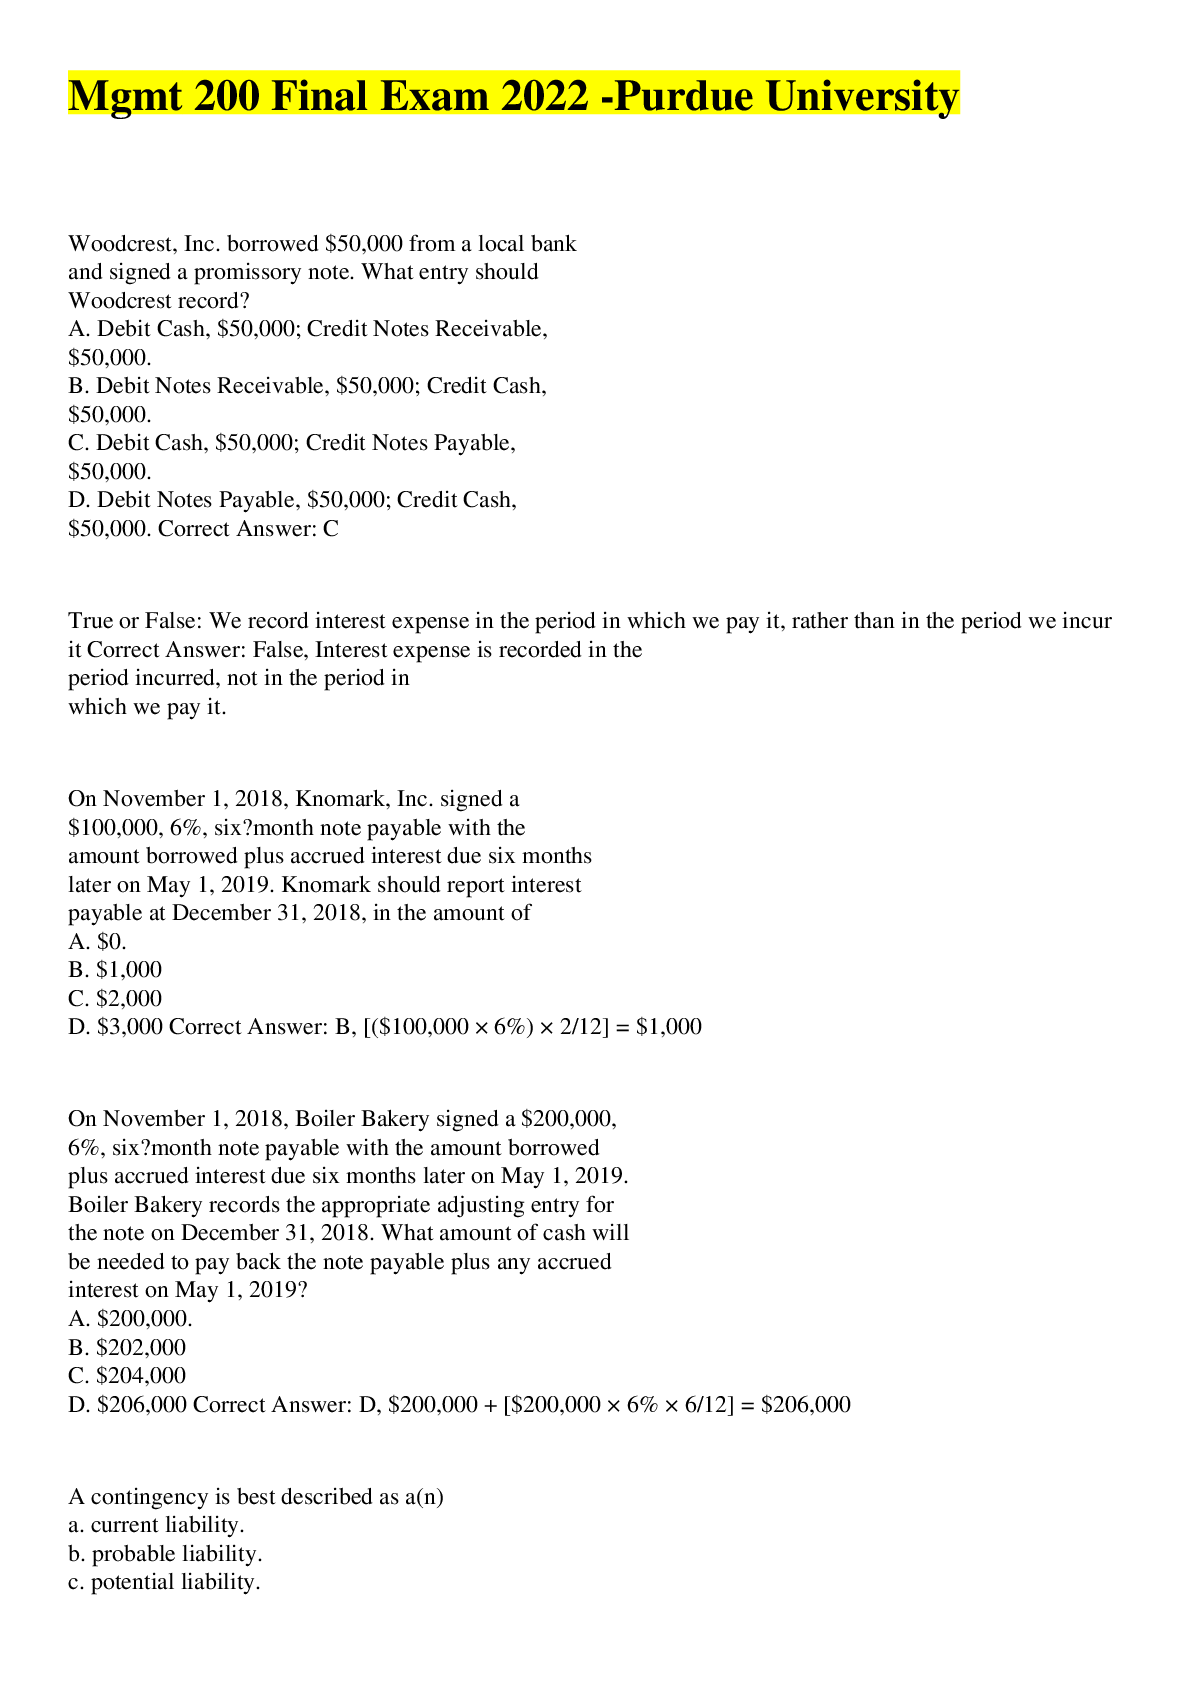
Woodcrest, Inc. borrowed $50,000 from a local bank
and signed a promissory note. What entry should
Woodcrest record?
A. Debit Cash, $50,000; Credit Notes Receivable,
$50,000.
B. Debit Notes Receivable, $50,000; Cred
...
[Show More]
Last updated: 3 years ago
Preview 1 out of 26 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Sep 30, 2022
Number of pages
26
Written in
All

Additional information
This document has been written for:
Uploaded
Sep 30, 2022
Downloads
0
Views
110
Topic Tags
Related Subjects & Courses
Explore similar study resources and related concepts.
Recommended For You
Get more on EXAM »


$55
20 Pages
ATI RN COMPREHENSIVE EXIT EXAM 2022/2023 ( LATEST VERSION GRAD...
.png)
$15
6 Pages
PALS - Red Cross Final Exam 2022, Reliable Study Materials & T...
$18
46 Pages
(AAMA)® Certification Exam 2022 | CMA (AAMA) Medical Assistant...
$20
566 Pages
Pearson’s Federal Taxation 2023 Individuals, 36e Timothy Ruper...
$20
643 Pages
McGraw-Hill's Taxation of Business Entities 2023 Edition, 14e...

$32
2186 Pages
Business Law 17th Edition Langvardt Test Bank.Answers and chea...
$25
61 Pages
Business Ethics 5th Edition Crane, Matten, Glozer, Spence | Te...
More related documents below