Mathematics > QUESTIONS & ANSWERS > Homework Assignment 1 - Ohio State University MATH 3589 (All)
Homework Assignment 1 - Ohio State University MATH 3589
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 3 pages
Instant download

Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Jan 23, 2023
Number of pages
3
Written in
All

Additional information
This document has been written for:
Uploaded
Jan 23, 2023
Downloads
0
Views
89
Topic Tags
Recommended For You
Get more on QUESTIONS & ANSWERS »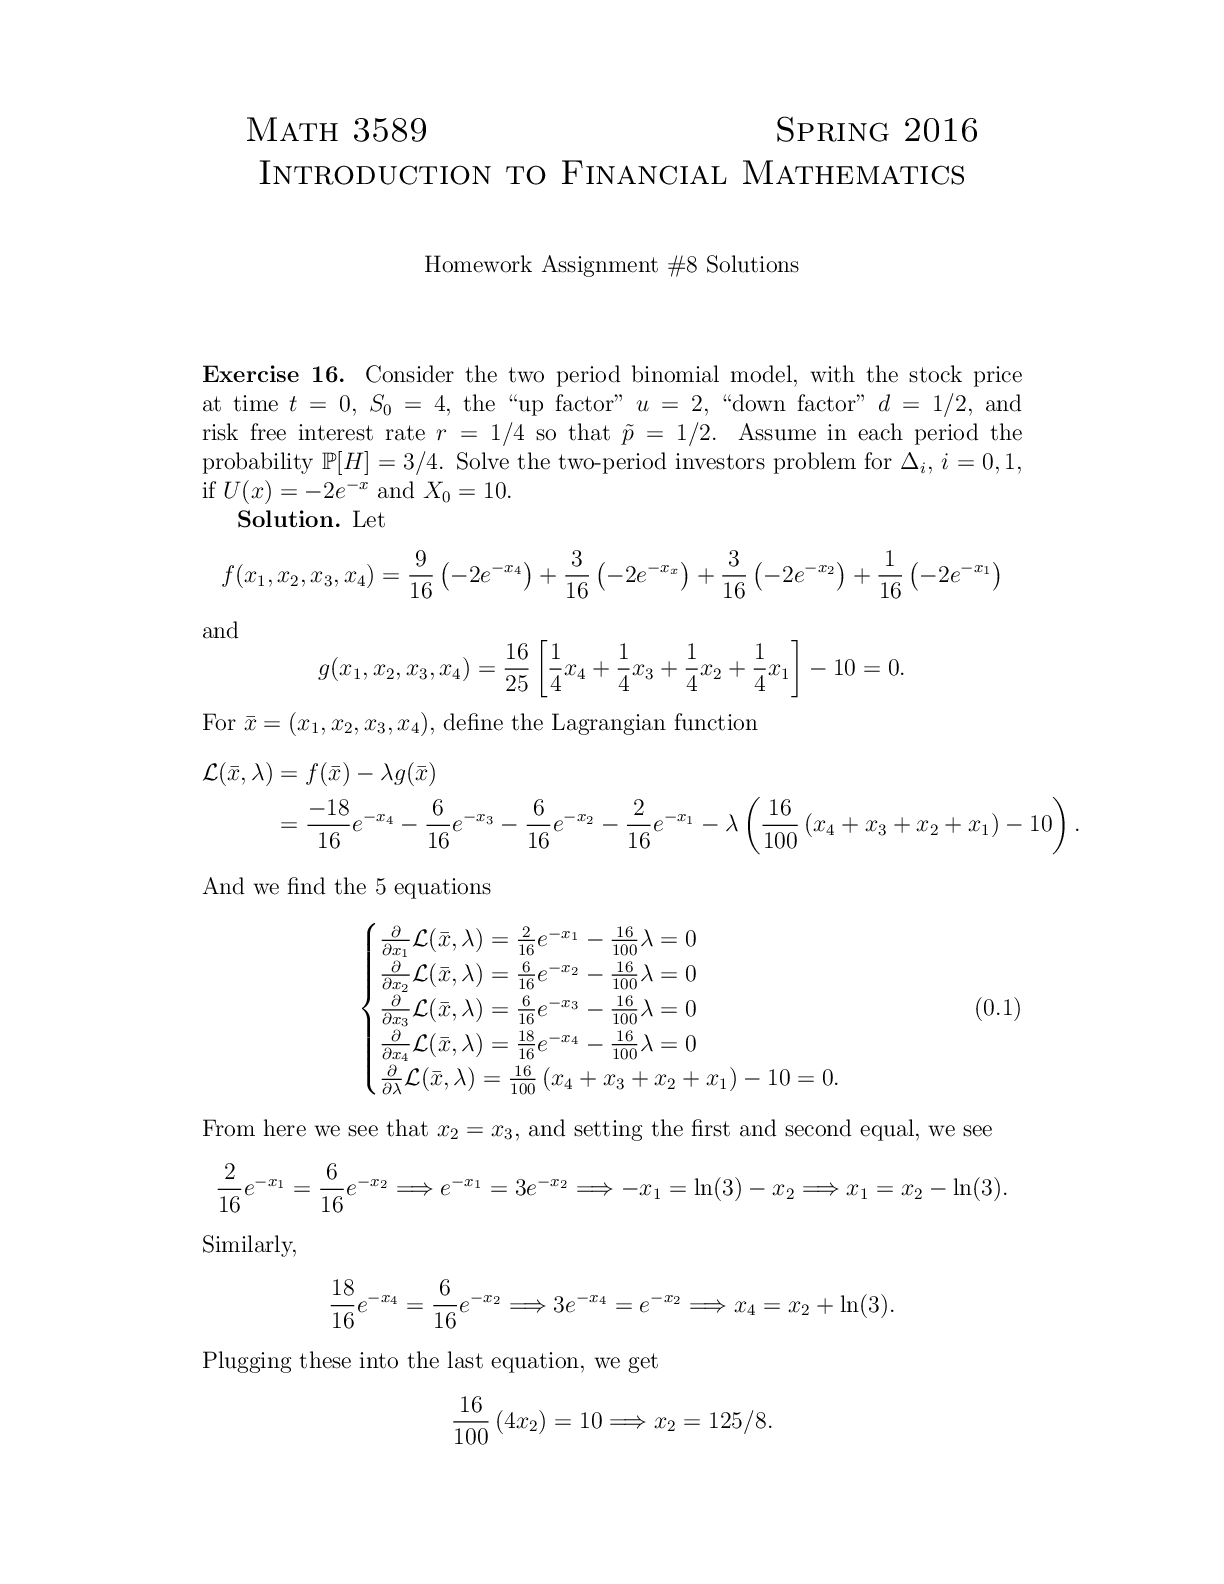
MATH 3589 Calculous - Ohio State University. Introduction to F...
Solutions Manual for Precalculus 11th Edition By Michael Sulli...
Solutions Manual For Applied Linear Algebra By Peter J. Olver,...
eBook Fractional Integrals, Potentials, and Radon Transforms 2...


.png)


.png)


