Accounting > STUDY GUIDE > Strayer University, Washington - ACC 499Biggest Merger and Acquisition Disasters (1) (All)
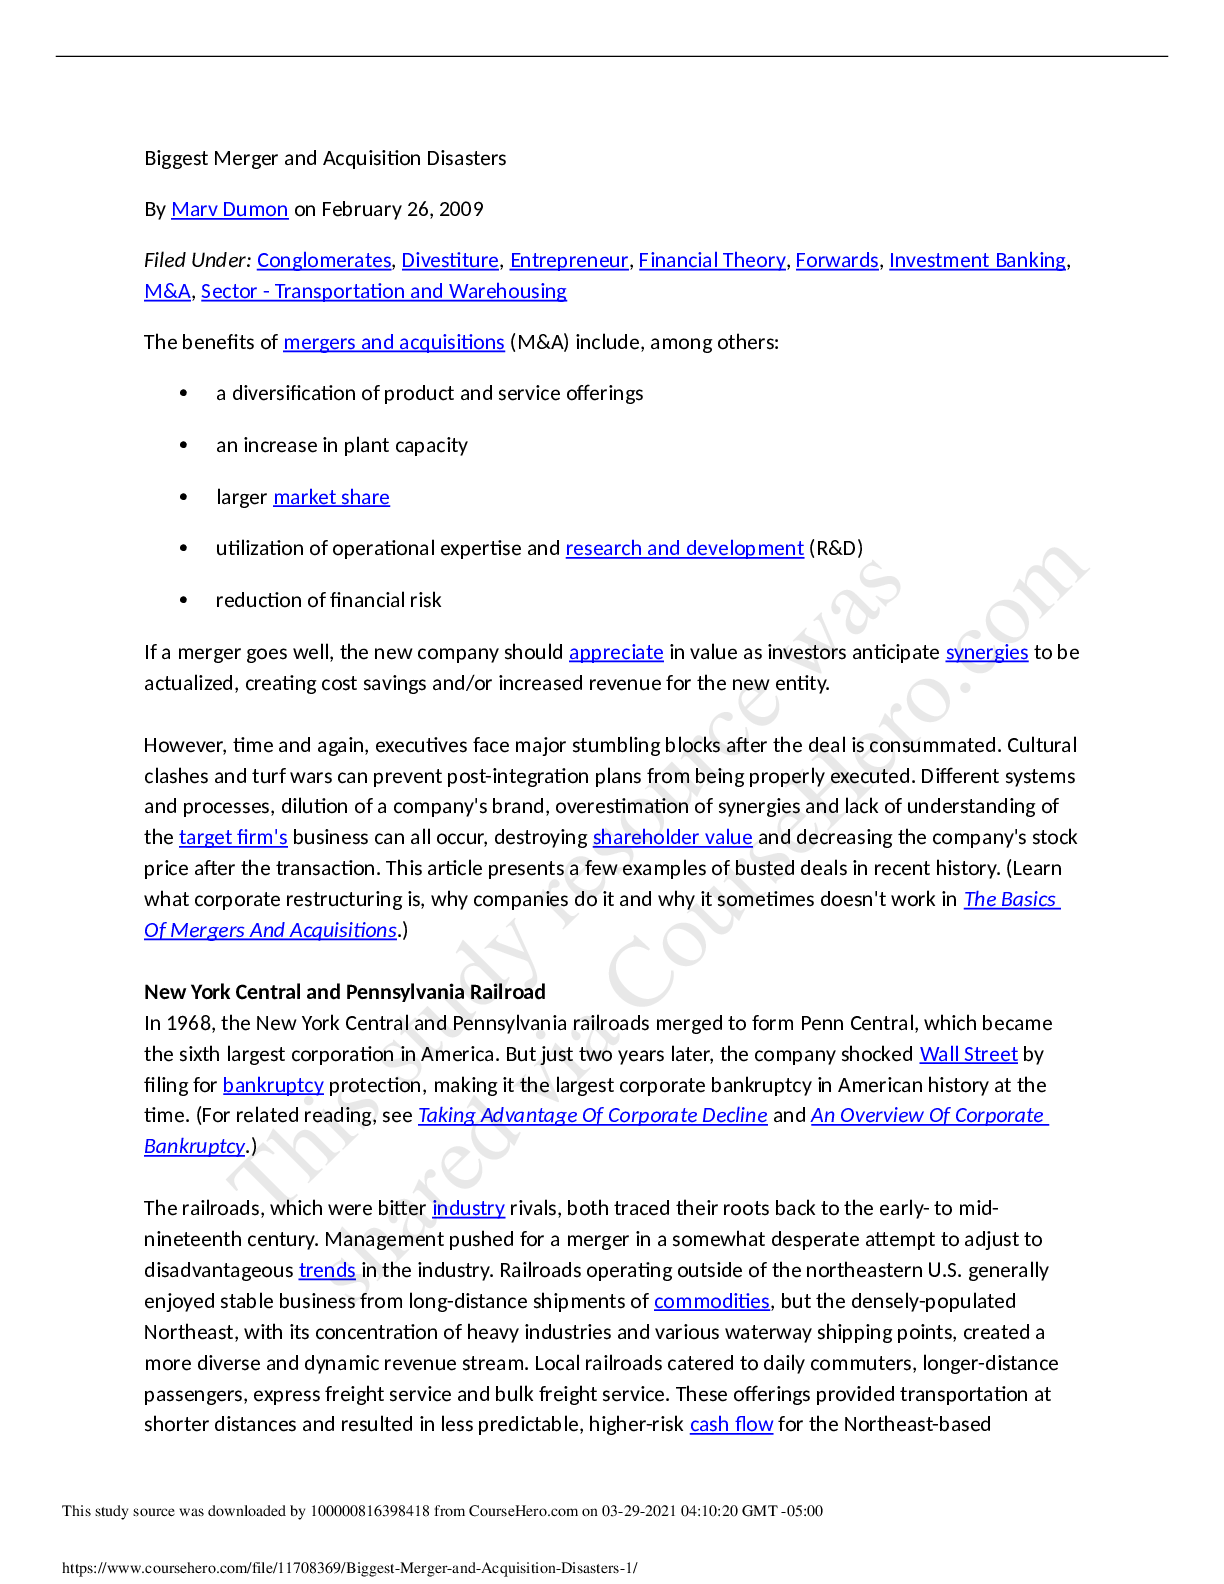
Strayer University, Washington - ACC 499Biggest Merger and Acquisition Disasters (1)
Document Content and Description Below
Last updated: 8 months ago
Preview 1 out of 5 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Mar 29, 2021
Number of pages
5
Written in
All

Additional information
This document has been written for:
Uploaded
Mar 29, 2021
Downloads
0
Views
103
Topic Tags
Recommended For You
Get more on STUDY GUIDE »
SOLUTIONS MANUAL for Advanced Accounting 8th edition by Debra...
SOLUTIONS MANUAL for Accounting and Auditing Research: Tools a...
Solutions Manual for Financial Reporting Financial Statement A...
Solutions Manual for Financial Statement Analysis and Valuatio...
Solutions Manual for Forensic Accounting and Fraud Examination...
Test Bank For Cost Management accounting andcontrol 6th Editio...

TEST BANK for Advanced Accounting 8th Edition By Debra Jeter,...
Solutions Manual For Cost Management Accounting and Control 5t...
HESI A2 REVIEW Anatomy and Physiology, HESI A2 Science, HESI A...

Psychology Exam 2 (Topics 5–9) — Class Notes, Study Guide & Te...
NSG 3500 Exam 3 Testbank – Comprehensive Nursing Practice Ques...
Med-Surg Certification Practice Questions – Comprehensive Medi...
NUR 253 Test 2 – Mental Health Nursing Questions, Answers & Co...



.png)