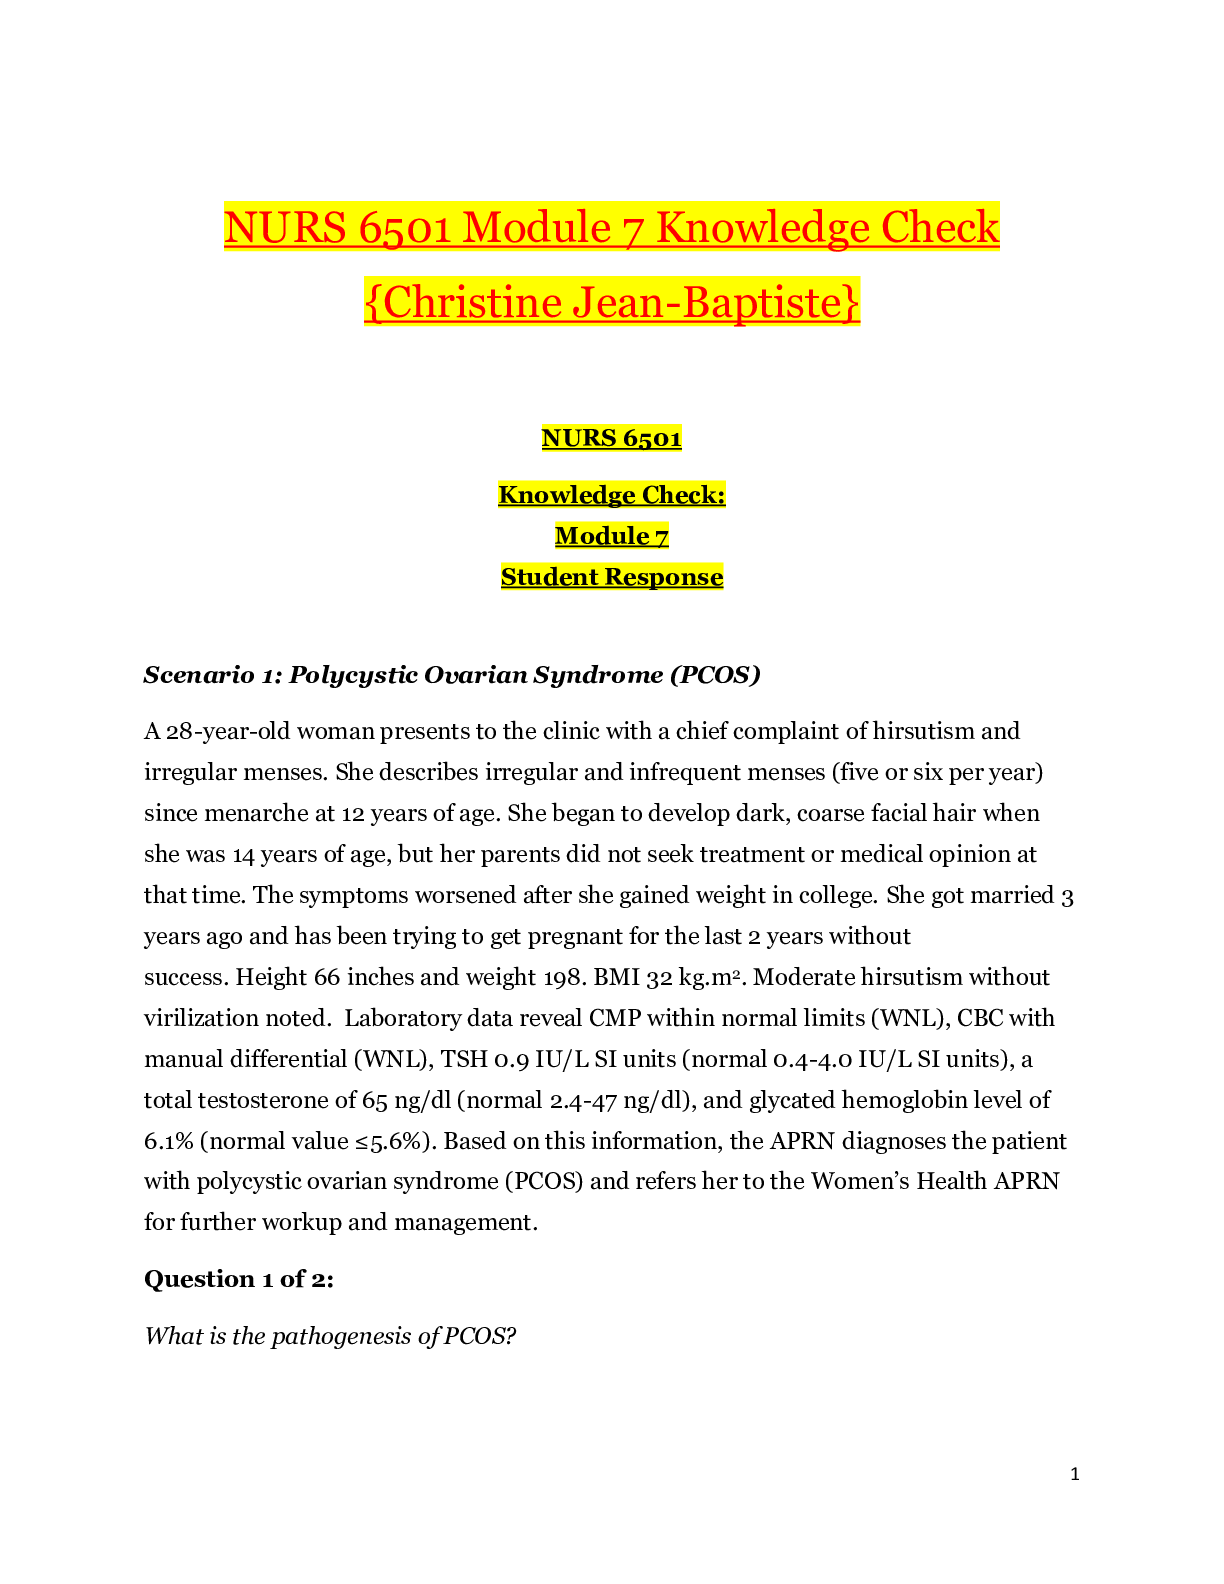
FIN 494 Homework 3 Solutions_2020 | FIN494 Homework 3 Solutions_Graded A
Document Content and Description Below
FIN 494 Homework 3 Solutions_2020
Problem 1
You are long on oil futures since May 1. On May 2, futures price on 1,000 barrels of crude oil with January 15 delivery was $50 a barrel, while spot price of crude oil wa
...
[Show More]
Last updated: 3 years ago
Preview 1 out of 11 pages
Instant download
Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Apr 16, 2021
Number of pages
11
Written in
All

Additional information
This document has been written for:
Uploaded
Apr 16, 2021
Downloads
0
Views
90
Topic Tags
Related Subjects & Courses
Explore similar study resources and related concepts.
Recommended For You
Get more on EXAM »
$13.5
16 Pages
FIN 494 Homework 7 Solutions_2020 | FIN494 Homework 7 Solution...
$11.5
9 Pages
FIN 494 Homework 2 Solutions_2020 | FIN494 Homework 2 Solution...
$13
13 Pages
FIN 494 Homework 4 Solutions_2020 | FIN494 Homework 4 Solution...

$7
11 Pages
University of Illinois, Chicago - FIN 494 exam prepared 6 ( A...
$7
16 Pages
University of Illinois, ChicagoFIN 494Final Exam prepared
$12
16 Pages
University of Illinois, Chicago - FIN 494 Final Exam prepared....
$7
14 Pages
TEST BANK FOR FIN 494(FINANCE) PERFECT FOR FINAL EXAM PREPARAT...

$7
14 Pages
University of Illinois, Chicago FIN 494exam with revised answe...

$7
8 Pages
University of Illinois, Chicago - FIN 494Homework 7 solutions.

$7
11 Pages
Exam Prepared for FIN 494exam-ALL ANSWERS CORRECT-GRADED A
$25
67 Pages
Finance for Non-Financial Managers, 7th Canadian Edition Pierr...
$24
775 Pages
Finance Applications and Theory, 6th Edition Marcia Cornett, T...
$24
360 Pages
Solution Manual for Introduction to Personal Finance Beginning...
More related documents below
.png)