Business > QUESTIONS & ANSWERS > NMLS Questions and Answers Latest Updated 2022 Graded A (All)
NMLS Questions and Answers Latest Updated 2022 Graded A
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 44 pages
Instant download

Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Also available in bundle (1)
Click Below to Access Bundle(s)

NMLS FULL SOLUTION PACK (ALL NMLS EXAMS AND STUDY QUESTIONS ARE HERE ,ALL ANSWERED CORRECTLY)
AZ NMLS Test Questions and Answers Already Passed California State NMLS Practice Test Graded A+ Loan Officer – NMLS Questions and Answers Graded A+ MLO SAFE NMLS safe test practice questions...
By Alphascore 3 years ago
$16
14
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Nov 15, 2022
Number of pages
44
Written in
All

Additional information
This document has been written for:
Uploaded
Nov 15, 2022
Downloads
0
Views
325
Topic Tags
Recommended For You
Get more on QUESTIONS & ANSWERS ».png)
BUS 375 Project management Questions and Answers Latest Update...
community health exit hesi updated 2022 & Proctored Exam
.png)
Dynatrace: Become a Jedi Master: updated 2022 Already Passed

(AAMA)® Certification Exam 2022 | CMA (AAMA) Medical Assistant...

Frances Guide Qbank to Pass Your Adult-Gerontology Acute Care...
Nursing Questions with Correct Answers, All HESI Fundamentals...

- Test Bank.png)
TESTBANK FOR HESI Extra Credit Modules 1, 2, 3, 4, 5, 6, 7, 8,...

HESI LIVE REVIEW EXAM BANK FOR THE NCLEX-PN EXAM- Updated 2022...

Pearson’s Federal Taxation 2023 Individuals, 36e Timothy Ruper...
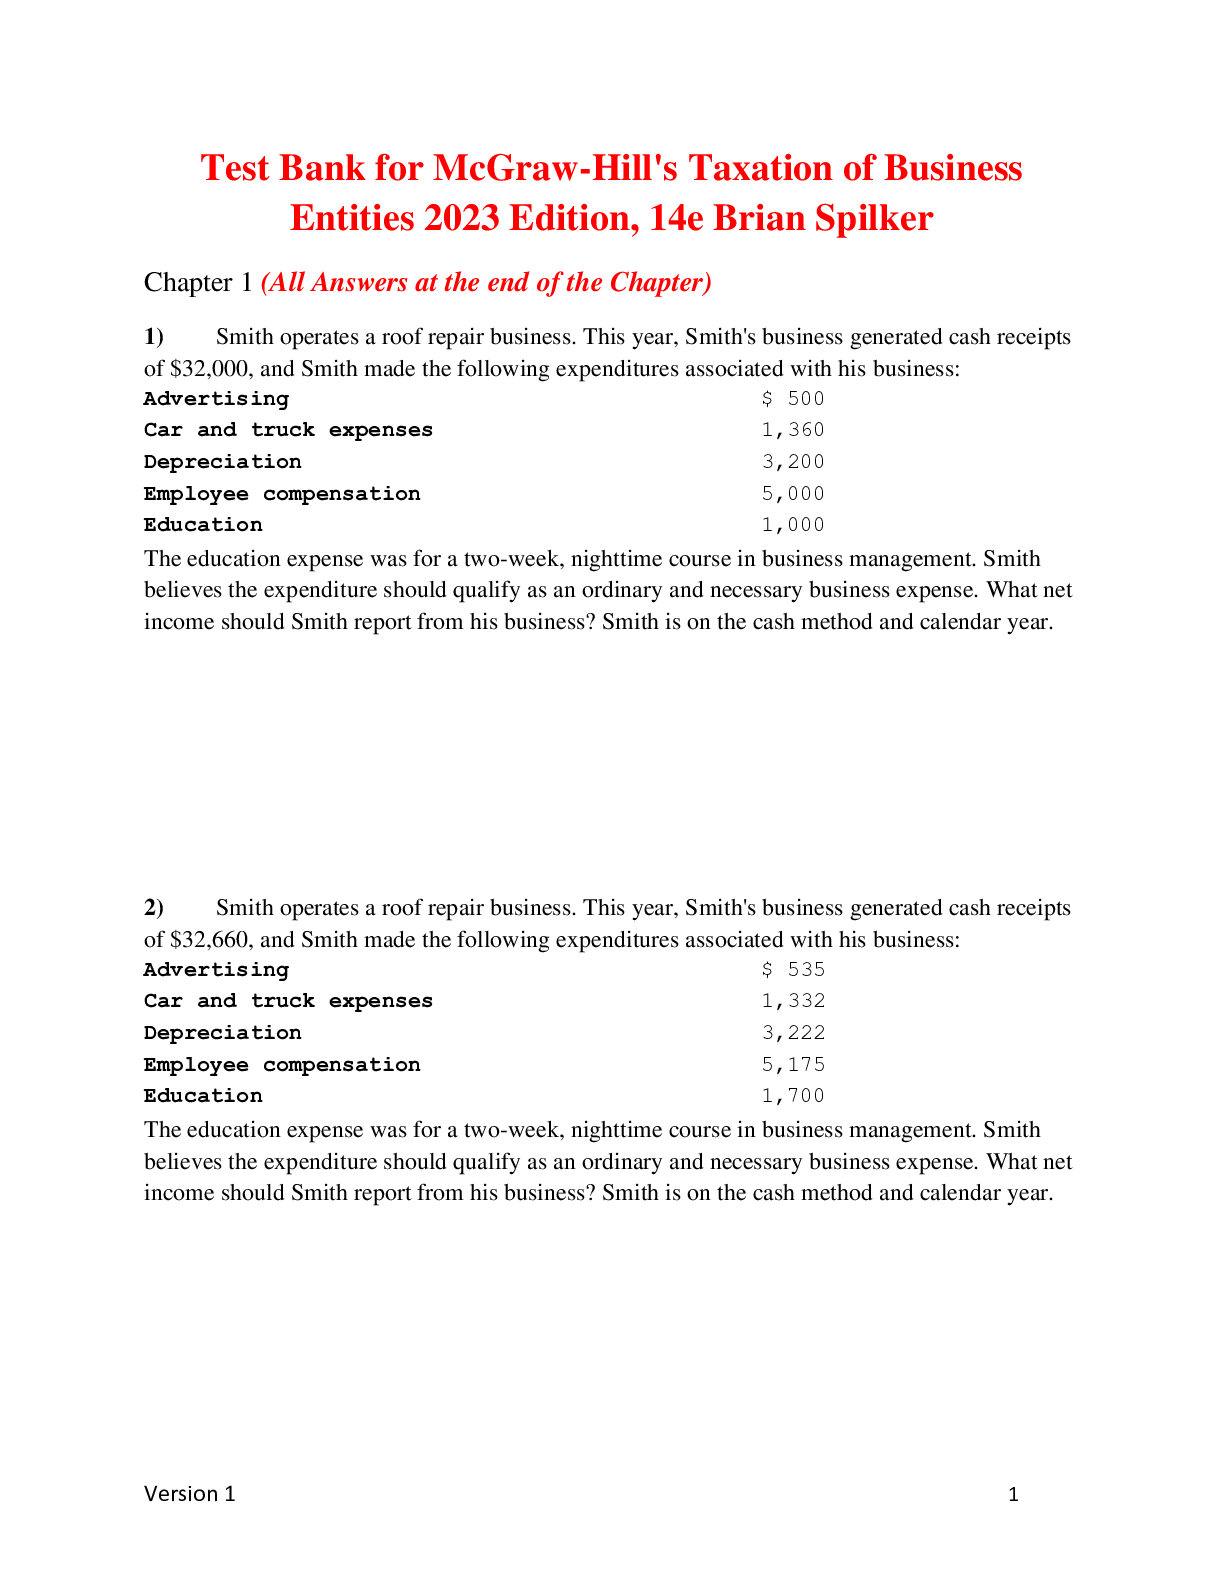
McGraw-Hill's Taxation of Business Entities 2023 Edition, 14e...
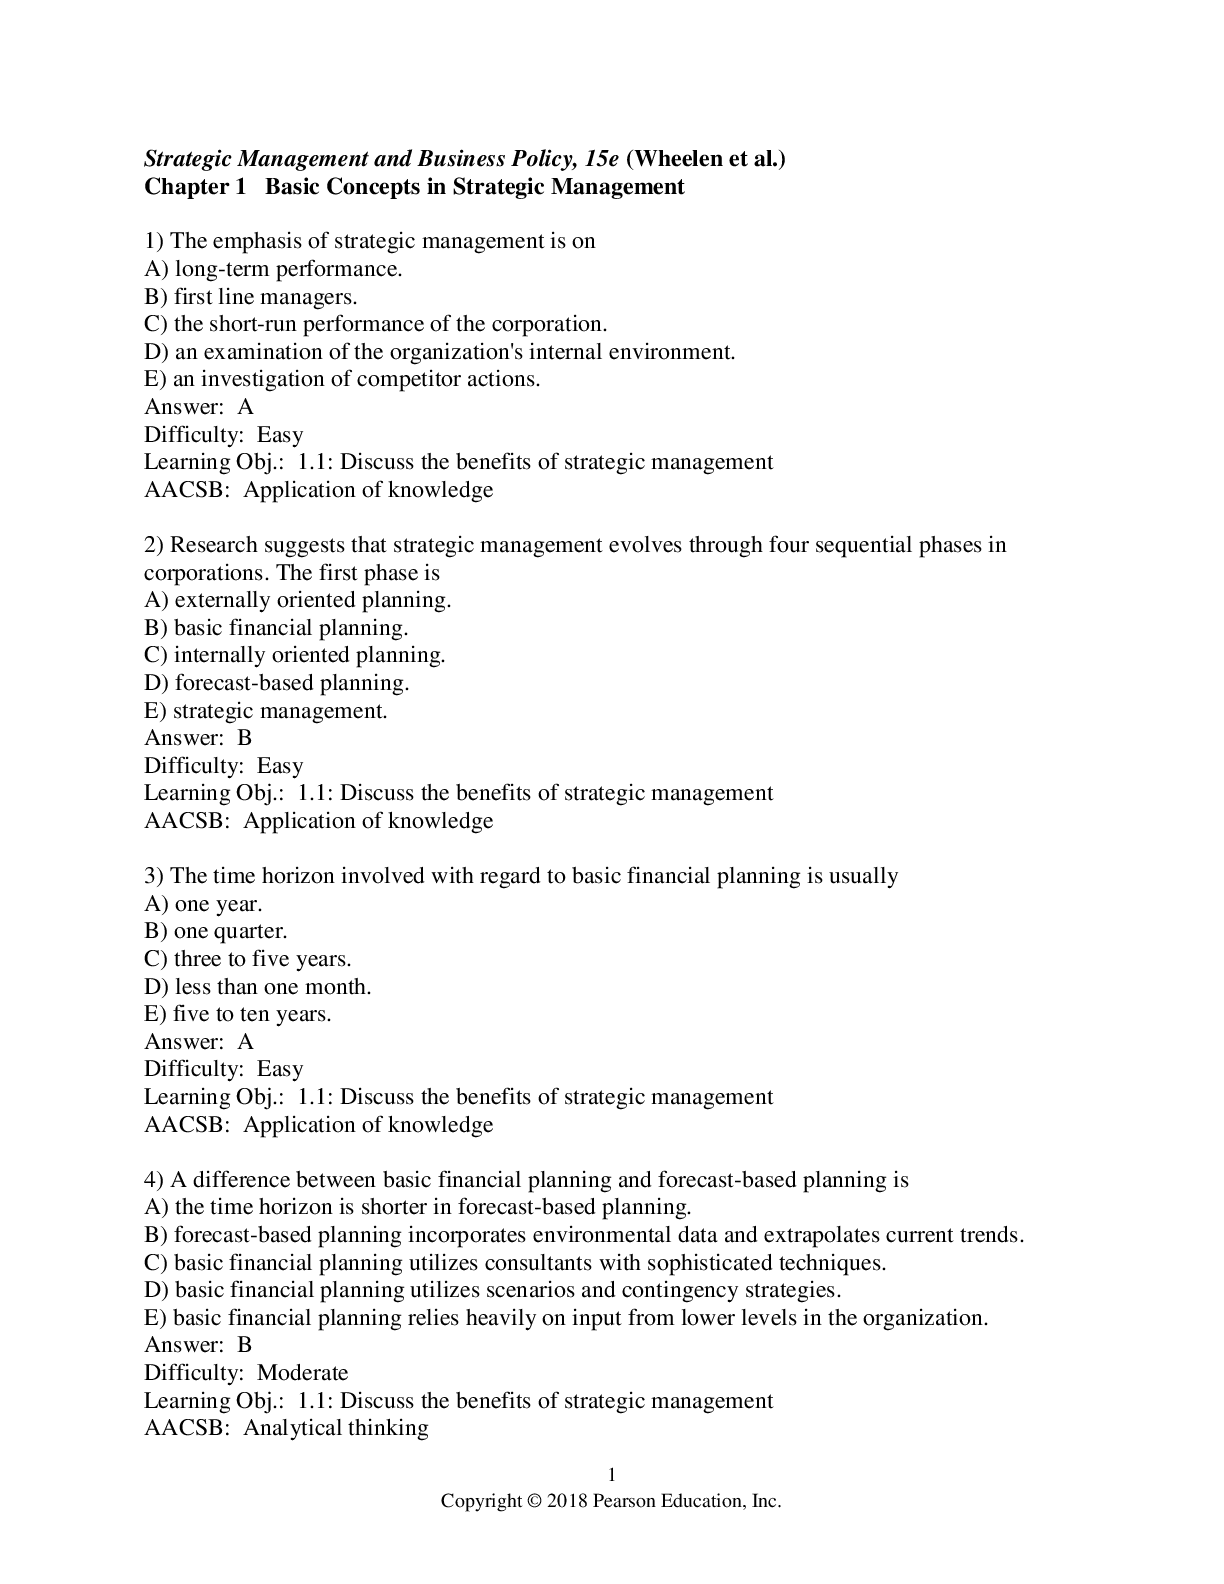
Concepts in Strategic Management and Business Policy Globaliza...


 with Complete Solution.png)
 Career Information with Complete Solution.png)


 for E-6 Career Information_watermark.png)