Business > CASE STUDY > Cash Conversion Paper.docx Cash Conversion Summary FIN/375 Cash Conversion Summary Wo (All)
Cash Conversion Paper.docx Cash Conversion Summary FIN/375 Cash Conversion Summary Wo
Document Content and Description Below
Last updated: 3 years ago
Preview 1 out of 4 pages
Instant download

Buy this Document to get the Full Access Instantly
Provided by Students Who Aced it
We Verify Document Content to Gurantee Accuracy
Reviews( 0 )
Document information
Connected school, study & course
About the document
Uploaded On
Jun 19, 2022
Number of pages
4
Written in
All

Additional information
This document has been written for:
Uploaded
Jun 19, 2022
Downloads
0
Views
75
Topic Tags
Recommended For You
Get more on CASE STUDY »
WestJet in 2009 The Fleet Expansion Decision, By Stewart Thorn...
Solution Manual for Canadian Income Taxation 20232024 26th Edi...
Solution Manual for Canadian Income Taxation (2022-2023) 25th...
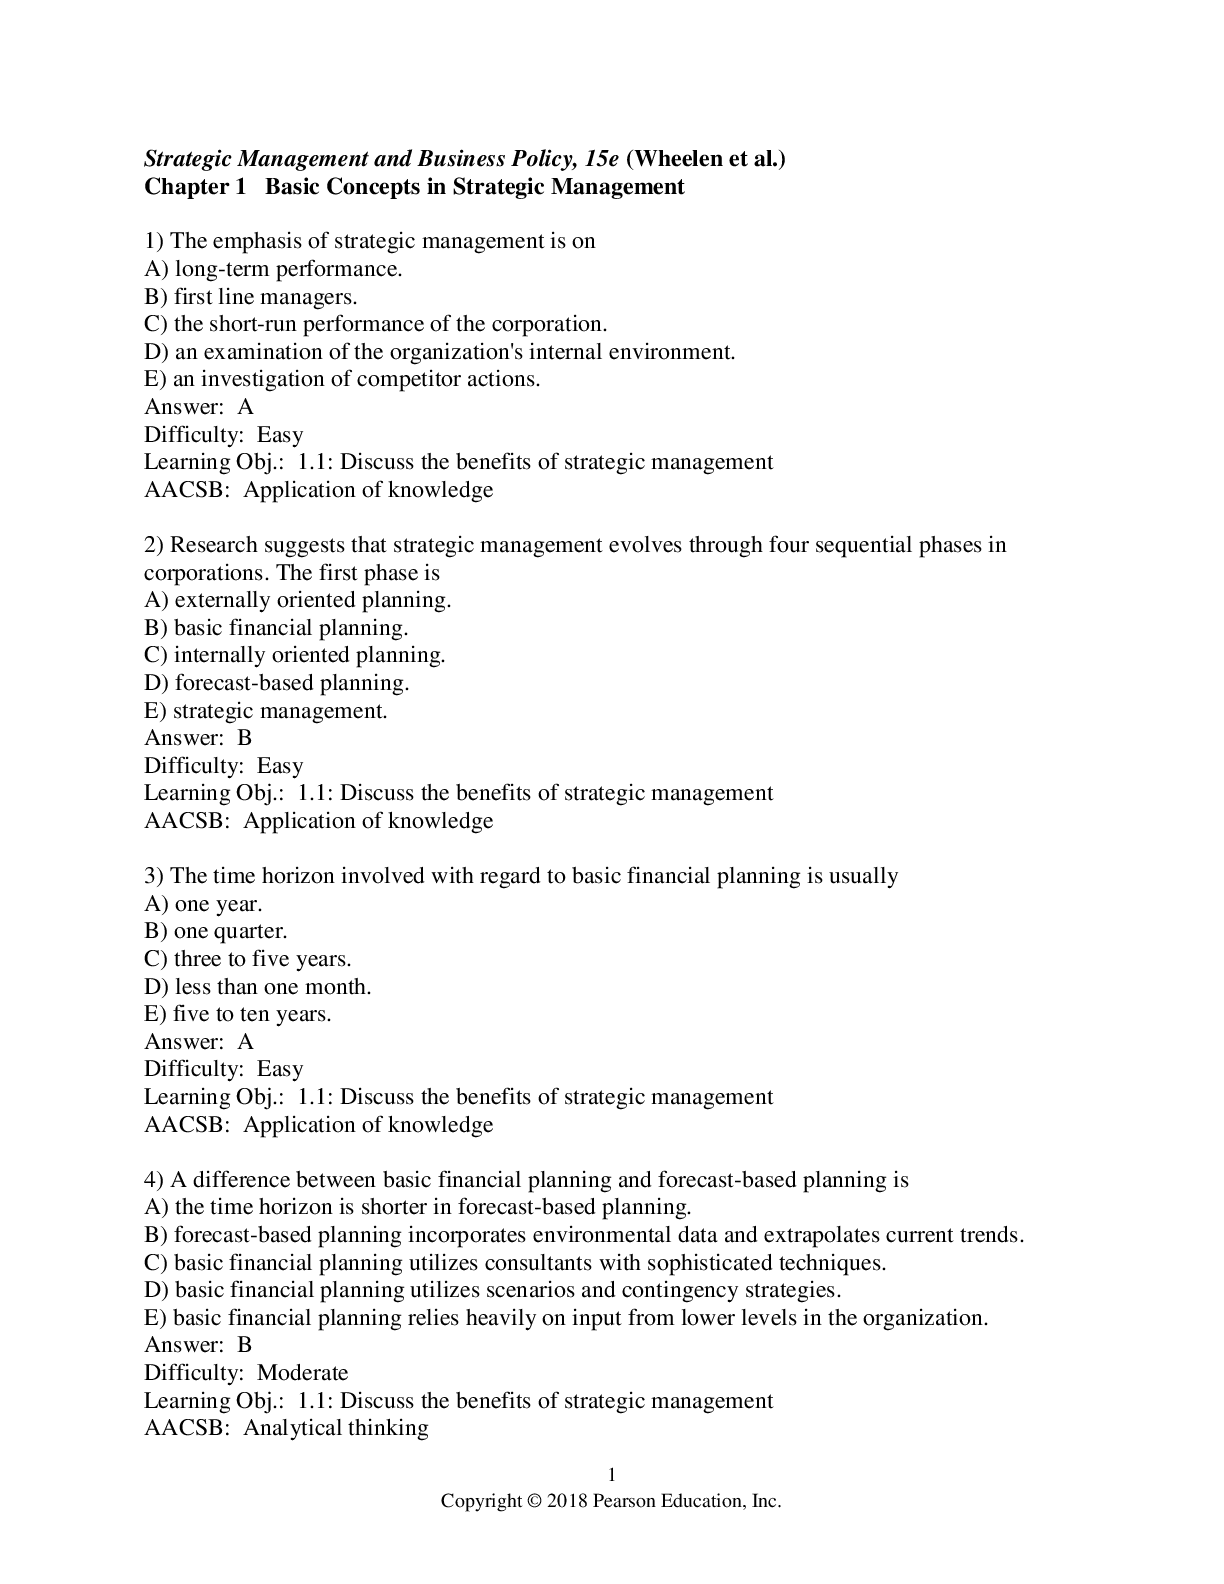
Concepts in Strategic Management and Business Policy Globaliza...

Business Law 17th Edition Langvardt Test Bank.Answers and chea...
Solutions Manual for Business Research Methods, 5th Edition By...
Yama Ribbons & Bows Co., Ltd. Where to Next, By Zhiduan Xu, Gl...